

In this guide
If you’re on the final stretch to retirement and would love to start winding back your working hours but don’t think you can afford it, listen up.
Ditto if you plan to keep working full time for a while longer and want to boost your super but haven’t got the ready cash to make extra contributions.
Help could be at hand in both cases in the form of a superannuation transition to retirement pension or income stream (TTR) that provides limited tax-free withdrawals from super while you’re still working. This tax-free income can be used to either:
- Supplement your income and facilitate a move to part-time work or cover other costs
- Make concessional contributions to super you couldn’t otherwise afford, reducing tax and boosting your super balance.
The maximum annual withdrawal from a TTR pension is 10% of its balance and the minimum is 4% of the balance.
Am I eligible?
If you’ve turned 60 but you’re not yet 65 and you’re still working, you’re good to go. You don’t need to cut back your working hours or change jobs. You’re also eligible if you’re in this age group and you’re not working right now but you haven’t retired permanently or left a job since your 60th birthday.
A retirement phase pension is available (instead of a TTR) when you’re 65 or older, you’re 60 to 64 and have permanently retired from work, or you’ve left a job after your 60th birthday.
If you’ve retired after 60, you can access all your super without a TTR. The same applies if you’re 60 or over and leave one of several jobs, because ending any job after 60 meets the retirement condition of release for the super you hold at that point. Learn more about conditions of release.
Which super pension you can start, by age and work status
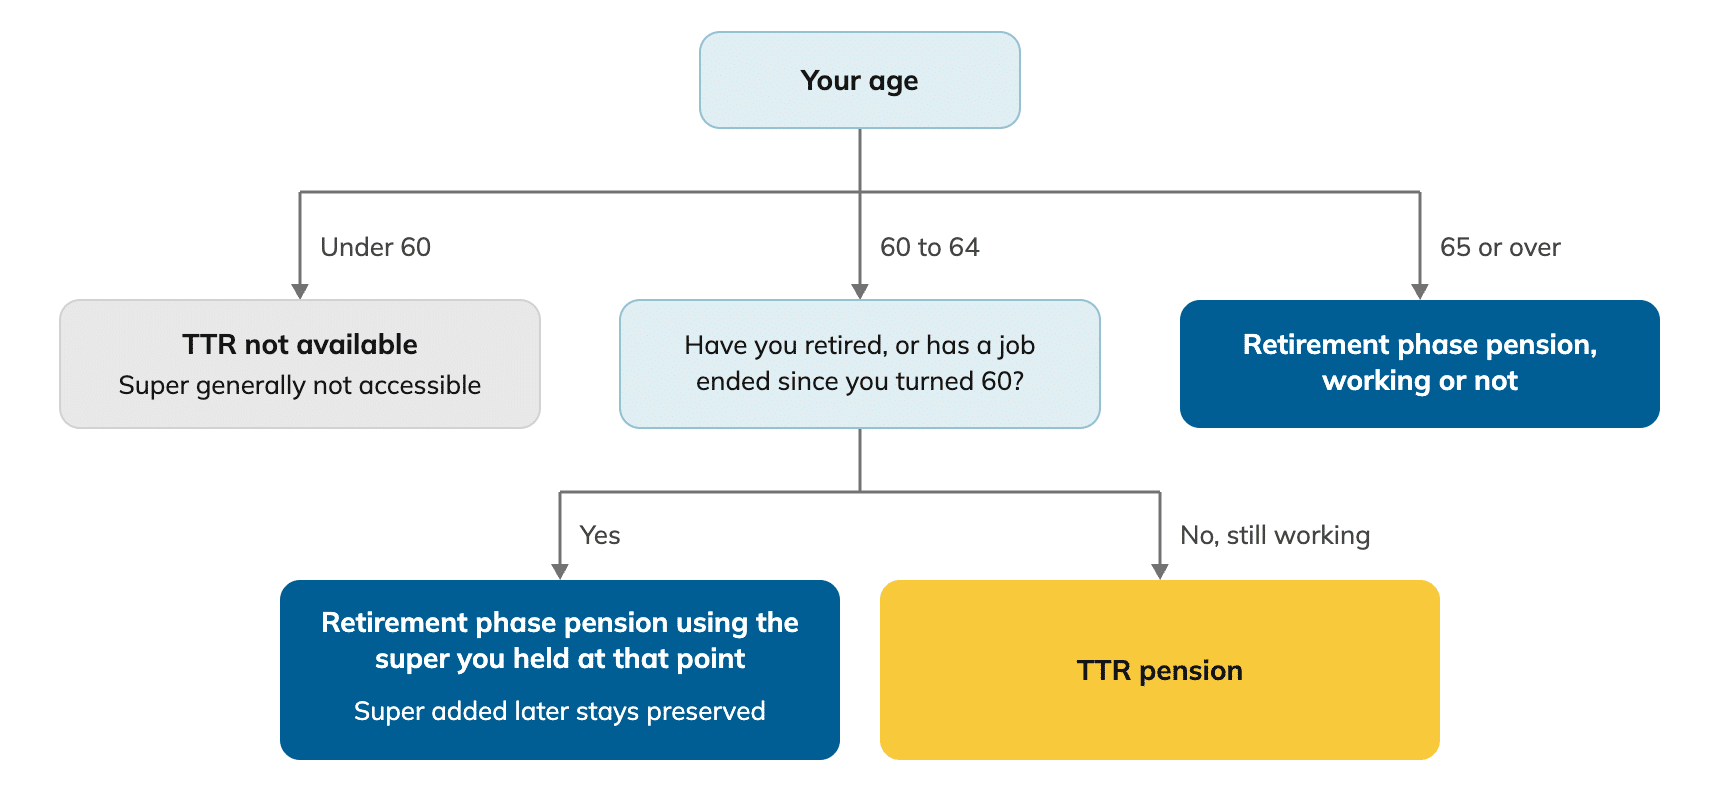
Other conditions of release, such as permanent incapacity, severe financial hardship or terminal illness, are not shown.
Source: SuperGuide
If you’re in a defined benefit fund, you may not be able to commence a TTR, or you may only be able to use a portion of your benefit. Only about 10% of Australians are members of defined benefit funds, which tend to be public sector or older corporate funds. If this is you, talk to your fund to find out your options.
Minimum and maximum withdrawals
Required minimum and maximum payments are calculated when you first open your account and then recalculated each financial year on 1 July while you still have a balance in a TTR pension.
The maximum annual payment is 10% of your balance and the minimum is 4%. The minimum is pro-rated when you start a pension partway through the financial year, but the maximum is not. You can start a TTR pension at any time of year. Withdrawals must be taken as pension payments, not lump sums.
What are the advantages?
Withdrawals from TTR pensions are tax free, while investment earnings attract a tax rate of 15% just like super accumulation accounts.
The ability to make tax-free withdrawals prior to retirement is the key benefit of TTR pensions. You can use your payments to make it affordable to reduce your working hours, contribute more to super, or for any other purpose you wish.
Here’s how a TTR pension compares with an accumulation account and a retirement phase pension.
| Feature | Accumulation account | TTR pension | Retirement phase pension |
|---|---|---|---|
| Who can have one | Anyone | Aged 60 to 64 | Anyone who has met a condition of release, such as retiring, leaving a job after turning 60, or turning 65 |
| Contributions | Allowed, with concessional contributions taxed at 15% | Not allowed | Not allowed |
| Tax rate for taxable investment income | 15% | 15% | Tax free |
| Tax on withdrawals | Tax free from 60 | Tax free | Tax free |
| Minimum withdrawal | None | 4% of the balance each year | Age-based, starting at 4% under 65 and rising with age |
| Maximum pension payment | n/a | 10% of the balance each year | No maximum |
| Lump sum withdrawals | Allowed once you meet a condition of release | Generally not allowed | Allowed |
| Counts towards your transfer balance cap | No | No | Yes |
| Social security means tests | Not assessed until you reach Age Pension age | Balance counts in the assets test and is deemed under the income test | Balance counts in the assets test and is deemed under the income test |
Tax treatment shown is for taxed super funds. Members of untaxed government funds are taxed differently. Higher-income earners may pay an extra 15% tax on concessional contributions (Division 293 tax). If your total super balance is very large, Division 296 tax applies to part of your earnings, whichever type of account they’re in.
Concessional contributions to super below the annual concessional cap ($32,500 in 2026–27) are taxed at the low rate of 15%. If your total super balance is below $500,000 on 30 June, you can also contribute more than the standard cap in the following financial year by using the carry-forward measure.
Making concessional contributions can be a valuable strategy if your marginal tax rate is higher than 15%. Combining these contributions with tax-free withdrawals from a TTR pension means you may be able to contribute more than you could otherwise afford.
Example: Using salary sacrifice and TTR to boost super
Jill is 60 and earns $100,000 a year, which puts her in the 32% tax bracket (including the Medicare Levy). She has $310,000 in super and wants to keep working full time until at least age 65, but wishes she could do more to increase her retirement savings. Since she doesn’t have the spare cash to make extra contributions, she decides to take advantage of a TTR strategy.
Jill starts a TTR pension with $300,000, leaving $10,000 in her accumulation account to keep it open for future contributions. She can withdraw a pension of up to $30,000 in the current financial year – 10% of the opening balance of her TTR. She decides to withdraw this amount and salary sacrifice back into her accumulation account to maintain the same take-home pay.
Jill has unused concessional cap space of $82,500 from prior years so she can exceed the standard annual concessional cap without generating excess contributions that are taxed at a higher rate.
To reduce her take-home pay from work by $30,000 per year (and replace it with $30,000 withdrawn tax free from super), Jill salary sacrifices $44,350 in 2026–27. After 15% contribution tax is deducted, this results in $37,697.50 being added to her super account.
The bottom line is an overall tax saving and a net boost to her retirement savings of around $7,700 for the year. This is Jill’s net additional contribution minus the pension income she has withdrawn.
After her employer’s contributions are added, Jill has used up $23,850 of her unused concessional cap space from prior years. If her balance remains under $500,000 on 30 June 2027, she can continue using her remaining available carry-forward amounts in the following financial year.
Jill’s tax and super boost, with and without a TTR, 2026–27
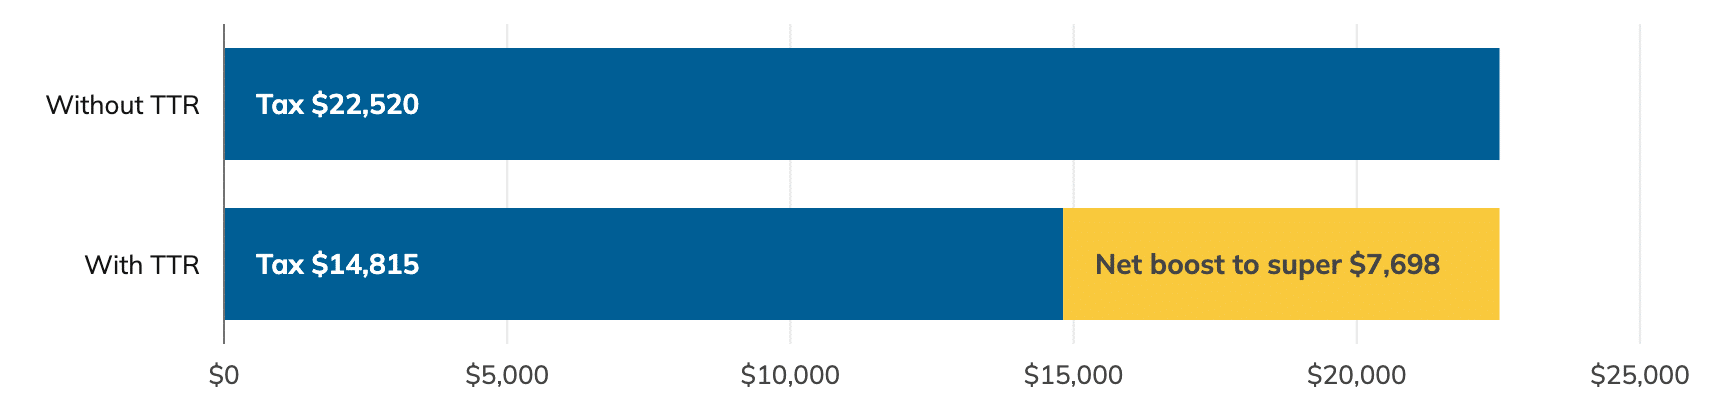
Illustrative example. Jill’s take-home pay is about $77,480 in both cases. With a TTR, she salary sacrifices $44,350 and takes $30,000 in tax-free TTR payments. Total tax is income tax and Medicare levy plus 15% contributions tax on salary sacrifice, using 2026–27 rates. Figures are rounded to the nearest dollar.
Source: SuperGuide calculations
There are also other strategies to consider, including using your pension payments to make non-concessional contributions to super as part of a recontribution strategy or to contribute to your spouse’s account.
What are the drawbacks?
Here are some things to keep in mind:
- The more of your super funds you withdraw during your TTR phase, the less money you’ll have available when you do retire – unless you replace your withdrawals with contributions.
- If you or your partner currently receives any social security payments, a TTR pension may affect your entitlements. The balance of a TTR is assessed in the assets test and used to calculate deemed income in the income test. In contrast, super held in an accumulation account by a person under age 67 is not assessable.
- Your super fund may require you to keep a minimum balance in your accumulation account to maintain any insurance cover you hold through super.
- The tax savings (and super boost) of salary-sacrifice or voluntary contributions into super may not be worthwhile for low- and high-income earners, as illustrated below.
For high-income earners, there may be limited scope to make additional concessional contributions.
How do I get started?
You start a TTR pension by transferring some of your super from your accumulation account into a transition to retirement pension account.
In practice, you contact your super fund and complete its pension application, nominating how much of your balance you want to use.
The transferred funds don’t count towards your transfer balance cap because you’re not in retirement phase. The funds in your TTR pension account will count towards your transfer balance cap once you do retire or turn 65, because the pension will convert into retirement phase. This cap is currently $2.1 million.
You must leave at least a small balance in your accumulation account so that it remains open to receive your employer’s compulsory super guarantee contributions or any voluntary contributions you may want to make.
How a TTR pension works alongside your accumulation account
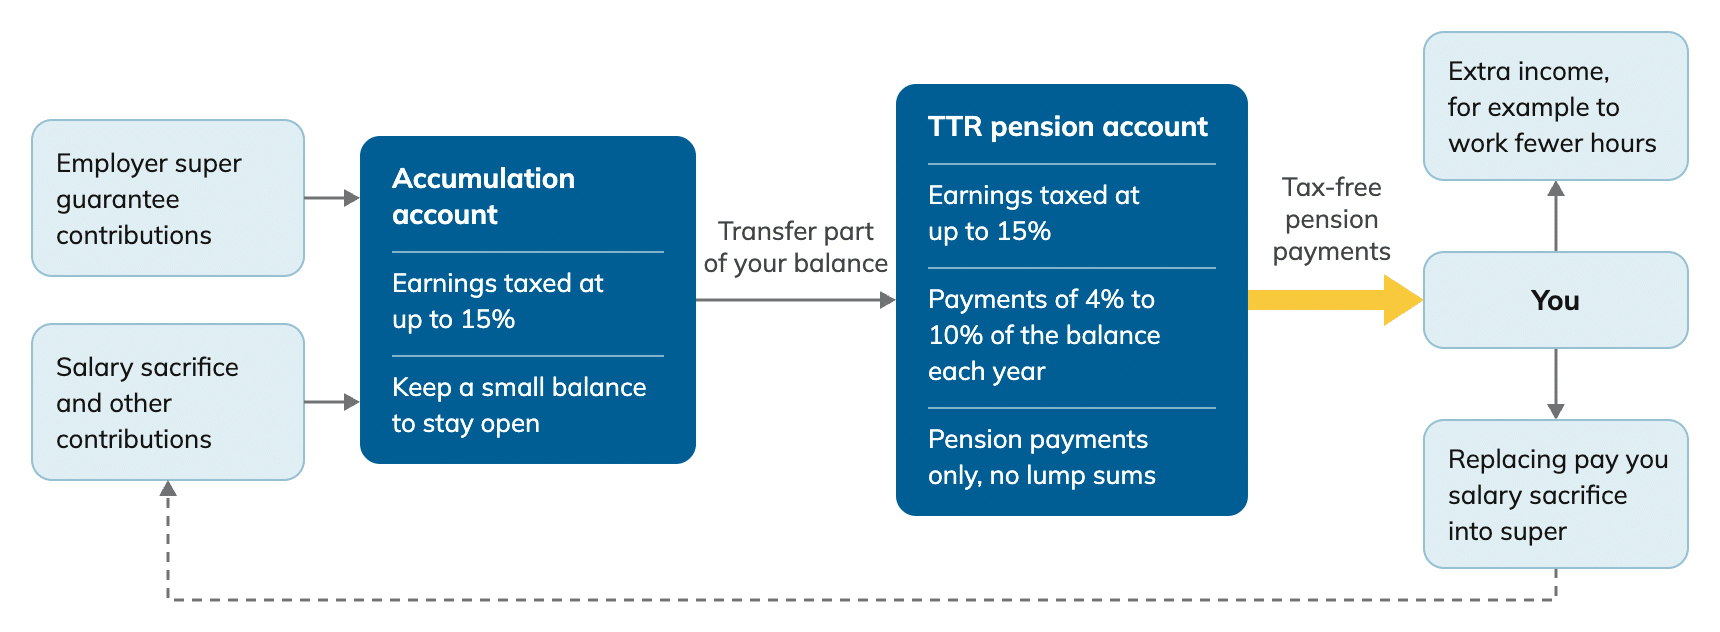
Payment limits are based on the TTR pension balance, calculated each 1 July. The minimum is pro-rated in the first year.
Source: SuperGuide
Investment earnings in both your accumulation and TTR pension accounts are taxed at 15%.
How do I stop a TTR pension?
A TTR pension converts to a retirement phase pension when you meet a superannuation condition of release – unless you choose to transfer it back into the accumulation phase and stop receiving pension payments. This happens automatically when you reach age 65. If you retire before 65, you need to tell your fund you’ve met a condition of release.
When your TTR pension becomes a retirement phase pension, you’ll be entitled to tax-free investment earnings and no upper limit to withdrawals. If you’re still working, you can continue to use the income from your retirement pension to use the same strategies you did for your TTR, but without the maximum limit on your withdrawals.
You can also transfer your pension account balance back into your accumulation account at any time. You must have made at least the pro-rated minimum withdrawal before you stop your TTR pension. For example, if you stop the pension exactly halfway through the financial year, you must have received 50% of that year’s minimum payment before stopping the pension.
How can I top up my TTR with additional contributions?
Superannuation law doesn’t allow contributions to be made into a pension account. When you have a TTR pension, you make withdrawals from the pension account and contributions to your accumulation account.
If a balance builds up in your accumulation account that you would like to use to top up your pension (and increase your maximum withdrawals), you can ask your fund to close your pension and transfer the balance back into your accumulation account.
Once all your money is combined in your accumulation account, you can start a new TTR pension with a higher balance. This is sometimes known as ‘pension refreshing’.
When you combine super accounts, the tax-free and taxable components of your super mix. Combining your accounts could make a strategy to reduce tax on your super after death more difficult or unwind steps you have already put in place.
Can I start a TTR from my self-managed super fund (SMSF)?
Yes, provided this is allowed in your SMSF’s trust deed.
As a trustee you’ll also need to follow your deed’s requirements for starting a pension, which usually include a pension application, trustee minutes or resolutions, valuing the fund’s assets and bringing the fund’s accounts up to date.
If you’re a trustee and want to start a TTR for yourself or another member of your fund, you should get independent professional advice. The rules are complex and not complying can be costly.
Look (for advice) before you leap
Transition to retirement pensions have real benefits for some people but may be less attractive for others. Deciding whether a TTR strategy is appropriate for you is an important decision and will depend on your personal financial circumstances and goals. Because the information in this article is general in nature, and the calculations around TTR pensions can be complex, we suggest you seek independent financial advice before you act.
Common questions about TTRs
TTRs can be confusing, so we’ve addressed some common questions below. Many of these questions come from our quarterly member Q&A webinars.
Q: Why have a transition to retirement strategy if you have enough income now for your means?
A: Using a TTR pension for additional income you may need for living costs or debt repayment is only one of the reasons to open one.
If you don’t need additional income, there may be other strategies to consider, including:
- Combining tax-free withdrawals with additional salary sacrifice to super to maintain the take-home pay you need while reducing tax and boosting your super balance.
- Using TTR withdrawals as part of a recontribution strategy to reduce tax for future beneficiaries.
- Withdrawing money from super using a TTR to lower your balance below $500,000 and become eligible to use the carry-forward rule to make concessional super contributions above the annual cap.
- Using TTR payments to contribute to your spouse’s account, potentially keeping both accounts below the transfer balance cap or the large super balance threshold for Division 296 tax.
Q: Can I start multiple transition to retirement pensions at the same time?
A: Yes. The super rules don’t limit how many TTR pensions you can have, although some funds only allow one pension account per member, so check with your fund.
Each TTR pension has its own minimum and maximum payments, worked out on its own balance. Splitting your money across two pensions doesn’t let you withdraw more in total, because the 10% maximum applies to each pension’s balance.
The most common reason for a second TTR pension is to move money that has built up in your accumulation account into a pension without closing your first one.
Keeping pensions separate also keeps their tax components separate, which can matter for estate planning.
Q: I’m 63. If I start a transition to retirement (TTR) pension, can I stop it before I turn 65, or must it run until then? And do I need to renew or reapply for it each year?
A: Yes. You can stop a TTR pension at any time by asking your fund to commute it, which moves the balance back to your accumulation account. It doesn’t have to keep running until you turn 65.
You also don’t need to renew or reapply each year. The pension keeps running until you stop it or until you meet a full condition of release (such as retiring from work or turning 65), when it moves into the retirement phase.
Each 1 July your fund recalculates your minimum and maximum payments for the year based on your balance on that date.
Q: I am currently 63 and I work 4 days a week as a receptionist in a doctor’s surgery. I also work 2 days a week in the local chemist. I am considering giving up my work at the chemist and then starting a transition-to-retirement pension from my superannuation fund to supplement my income. Can I commence a TTR once I cease my role at the chemist shop?
A: You may not need a TTR pension at all.
If you’re 60 or over, you meet the ‘retirement’ condition of release when any employment arrangement ends. So if you stop working at the chemist but keep your job at the doctor’s surgery, the super you hold on the day you leave the chemist becomes unrestricted non-preserved. You can use it to start a retirement phase pension rather than a TTR.
Contributions and earnings added to your super after that day are preserved. You can’t access them until you meet another condition of release, such as retiring completely or turning 65.
Q: If I retire from my work, what happens to my transition to retirement pension? Does it need to stop?
A: Generally, when you inform your fund you have retired or you turn 65, your TTR pension will enter the retirement phase. This means:
- The balance will be added to your transfer balance account and counted towards your transfer balance cap
- The 10% maximum pension limit will be removed
- You will be permitted to make lump sum withdrawals.
If you have an SMSF, you will need to check your trust deed for any fund-specific rules that apply. Some SMSF trust deeds require an existing pension to be stopped before any restriction around payment levels can be changed.
SMSF trustees will also need to consider any transfer balance account reporting requirements that need to be met when a TTR pension enters retirement phase.
If you don’t want your TTR to be converted to a retirement phase pension when you retire or turn 65, you can choose to close it in advance by transferring the balance back into an accumulation account/interest.
Combining accounts mixes their tax components, which could have an undesirable effect on any strategy you have previously put in place to minimise tax on your super after death. You may open a new (empty) accumulation account to transfer your TTR pension into if you want to avoid mixing the tax components from two accounts. Taking advice is recommended.
Q: I’m 61 and still working. If I start a transition to retirement (TTR) pension, do I need to report it for the transfer balance cap? And what happens if my TTR balance is more than my available cap when I turn 65?
A: Starting a TTR pension will not add to your transfer balance account because TTR pensions are not in the retirement phase.
When you meet a condition of release with no cashing restrictions, such as retiring or turning 65, the TTR pension moves into the retirement phase. This process is triggered automatically on your 65th birthday, or when you tell the fund you have met another condition of release.
The day your pension enters retirement phase, its value must be reported to be added to your transfer balance account and counted towards your transfer balance cap.
If you have an SMSF, you must report this to the ATO through transfer balance account reporting (TBAR). A large fund reports it for you.
If the value of the pension at that point is more than your available cap, the excess needs to be moved back to an accumulation account or cashed as a lump sum (commuted). The ATO will tell you the amount to remove, and excess transfer balance tax applies to notional earnings on the excess until it is removed.
If you want more control over the amount that is added to your transfer balance account and the timing, you can choose to close your TTR pension and move the value back into an accumulation account before meeting a relevant condition of release. Then, you will not have a credit made to your transfer balance account until you choose to start a new retirement phase pension.
Q: I plan to retire and access my super pension next year after my 60th birthday, but I’d then like to work occasionally as a casual employee in a similar role with the same employer. Is this allowed under the super rules, or is starting a transition to retirement pension my best option?
A: When you’re 60 or over and an employment arrangement ends, you meet the ‘retirement’ condition of release for the super you hold at that point. It stays accessible even if you go back to work later, so you can start a retirement phase pension with it rather than a TTR.
There are many types of retirement income products available including simple account-based pensions, traditional annuities, and investment-linked annuities/pensions.
If you plan to access super as a lump sum or retirement phase pension in these circumstances and then return to the same employer, the original job needs to have genuinely ended. Coming back on new terms such as casual work is permitted, but your fund may ask you to confirm the earlier arrangement ended.
Any contributions and earnings added to your super after you stop work are preserved. You can access them once you meet another condition of release, such as leaving another job, retiring permanently, or turning 65.
Q: If someone opens a transition to retirement account to generate tax-free income and then contributes that income to their spouse’s super as concessional contributions, what potential drawbacks could there be?
A: Withdrawals you make from a TTR pension are your money and you can use them for any purpose.
However, a contribution you make into your spouse’s super account can’t be a concessional contribution. It’s a spouse contribution, which is non-concessional. You can’t claim a tax deduction for it, although you may be able to claim the spouse contribution tax offset if your spouse’s income is low.
If the aim is to add concessional contributions to your spouse’s account there are two possibilities:
- Make concessional contributions to your own account and then split them to your spouse after the end of the financial year. Up to 85% of your concessional contributions can be split. Your spouse can receive a split if they’re under 60, or aged 60 to 64 and not retired.
- Give the money withdrawn from your TTR to your spouse to help them afford to contribute to their super. They could make a personal contribution to their account and claim a tax deduction or arrange salary sacrifice with their employer that would reduce their take home pay.
Other things to weigh up:
- Money that goes into your spouse’s super becomes theirs, and is preserved until they meet a condition of release
- The maximum spouse contribution split is 85% of your concessional contributions or the value of your concessional cap, whichever is lower
- Spouse contributions count towards your spouse’s non-concessional cap, and can only be made if their total super balance is under the general transfer balance cap
- Withdrawing from your TTR reduces your own balance
Q: I made a personal contribution and lodged a notice of intent to claim a deduction, then converted my entire super balance to a transition to retirement (TTR) pension a few days later. Can I still split part of that contribution to my working spouse after 30 June?
A: There are three important timing points in this scenario.
- The fund must acknowledge receipt of your notice of intent (NOI) to claim a tax deduction and process it before you start your pension. If it is not processed before you use any part of your balance to start a pension, it will be invalid.
- You must apply and split contributions to your spouse’s account after the NOI is processed. The NOI indicates to the fund that the contribution will be converted to a concessional amount that can be split. Non-concessional contributions are not splittable, so the fund can’t process a split before the NOI. Some funds will allow you to submit both the NOI and splitting application together, and process them in the appropriate order.
- Your contribution splitting application must be processed before you use your entire balance to start a pension or roll over to another fund. While you usually need to wait until the following financial year to split contributions, an exception applies if you are rolling over or transferring your entire benefit. It allows the fund to split contributions before the end of the financial year they were added to your account.
If you have already used your entire balance to start your pension, and did not split your contributions first, unfortunately that opportunity has been lost.
When only part of your balance is used to start a pension, a contribution splitting application may be accepted for the remaining balance in your accumulation account in the following financial year. The remaining balance would need to be sufficient to finance any split you request.
Q: Can I use the contribution splitting strategy if my spouse is already accessing benefits under a transition to retirement pension?
A: A person who is 60 or more but has not yet turned 65 is eligible to receive a contribution split from their spouse if they do not meet the retirement condition of release at the time of the split.
This condition of release can be met in two ways:
- leaving a job after turning 60
- being 60+ and permanently retired from work
If your spouse has not left a job after turning 60, is not yet 65, and is not permanently retired from work, then they can receive the split. If they left a job after 60 but have since returned to work, they may receive the split because they can’t access new superannuation contributions until they meet a condition of release again.
Receiving a TTR pension does not affect this rule, but the contribution split can’t be transferred directly into the pension. Your spouse needs an accumulation account to accept contributions transferred to them from your account.
When your spouse retires or turns 65, they will no longer be eligible to receive a contribution split.
Q: How can I determine if my SMSF allows members to access benefits through a transition to retirement pension?
A: The rules for each SMSF are set out in its trust deed. If you want to check if your fund allows TTR pensions, then you need to read your fund’s trust deed.
Your deed would usually have a section on “member benefit payments” or “pensions”, where it should set out rules that are specific to transition to retirement pensions.
The following are examples of trust deed clauses allowing TTR pensions:
Example 1: “The Trustee must pay transition to retirement pensions consistently and as defined in SIS Regulations (Regulation 6.01(2)). …..”
Example 2: The Trustee must pay a pension benefit to a Beneficiary in the form of:
- A non-commutable account-based pension (transition to retirement)
- A defined benefit pension
- A market-linked pension
Example 3: The “XYZ Superannuation Fund” trust deed permits the trustees to pay any type of pension permissible under superannuation law.
It would also be a good idea to check your trust deed for any fund-specific rules or requirements around the establishment of a pension.

Leave a Reply
You must be logged in to post a comment.