


In this guide
When you’re aged 60 or more, you have the option to open an income stream (pension) with your super that provides you with regular periodic payments.
There are many types of retirement income streams but the most common is a simple account-based pension.
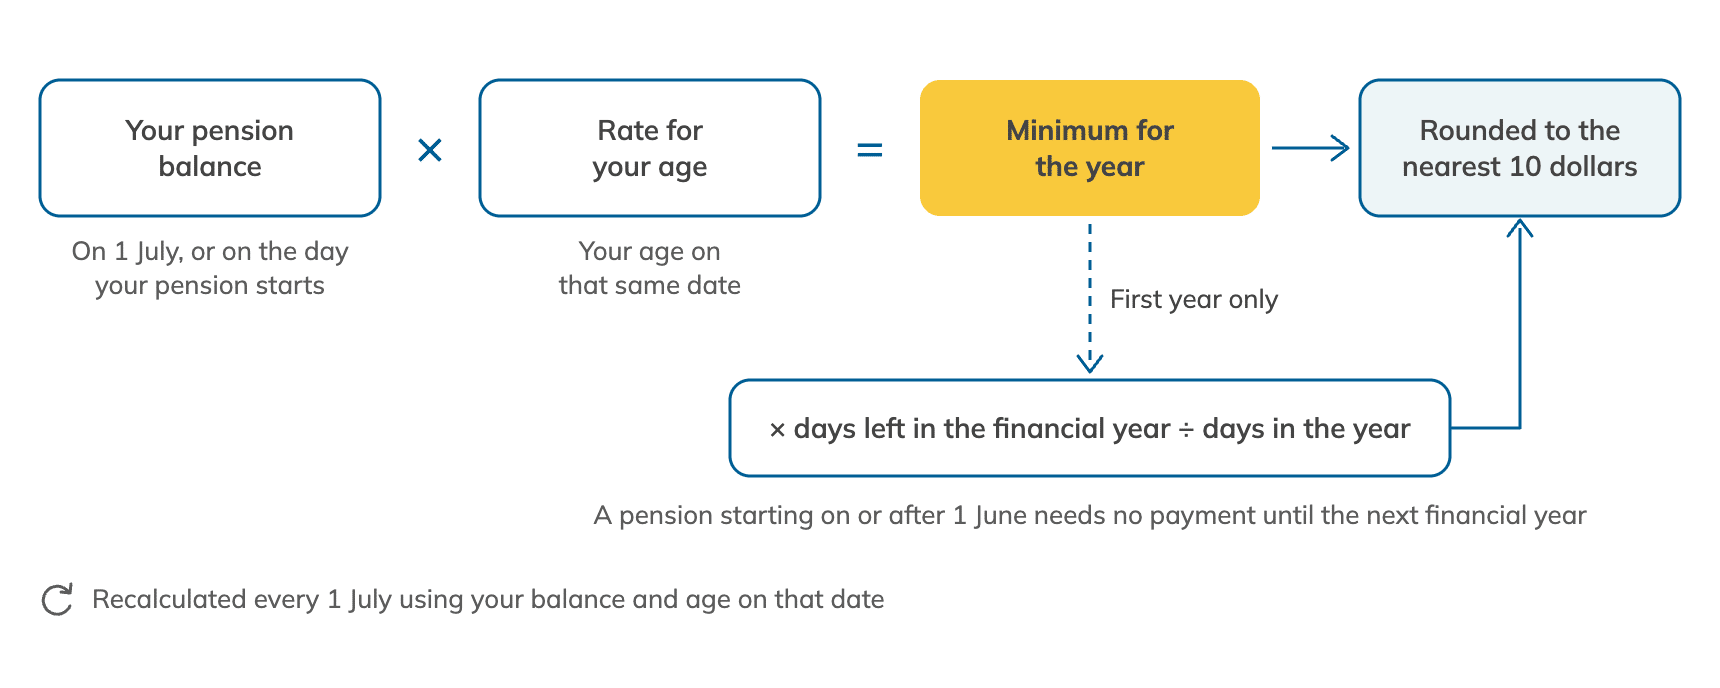
When you have an account-based pension, you are required to withdraw at least the minimum annual pension amount. The minimum is initially calculated on the start date of the pension using the opening balance and your age at the time. It is then recalculated on 1 July each year.
In the financial year you open your pension, the minimum payment is pro-rated to reflect the number of days remaining in that year.
How your minimum pension payment is worked out
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7
Retirement phase account-based pensions have no maximum annual withdrawal.
If you’re under 65 and have not left a job after your 60th birthday or retired permanently, you can open a transition to retirement (TTR) pension. The minimum annual withdrawal for a TTR pension is the same as for a retirement phase pension but an annual maximum of 10% also applies. When you turn 65 or retire, your transition to retirement pension converts into a retirement phase pension with no maximum withdrawal.
Minimum pension payment rates
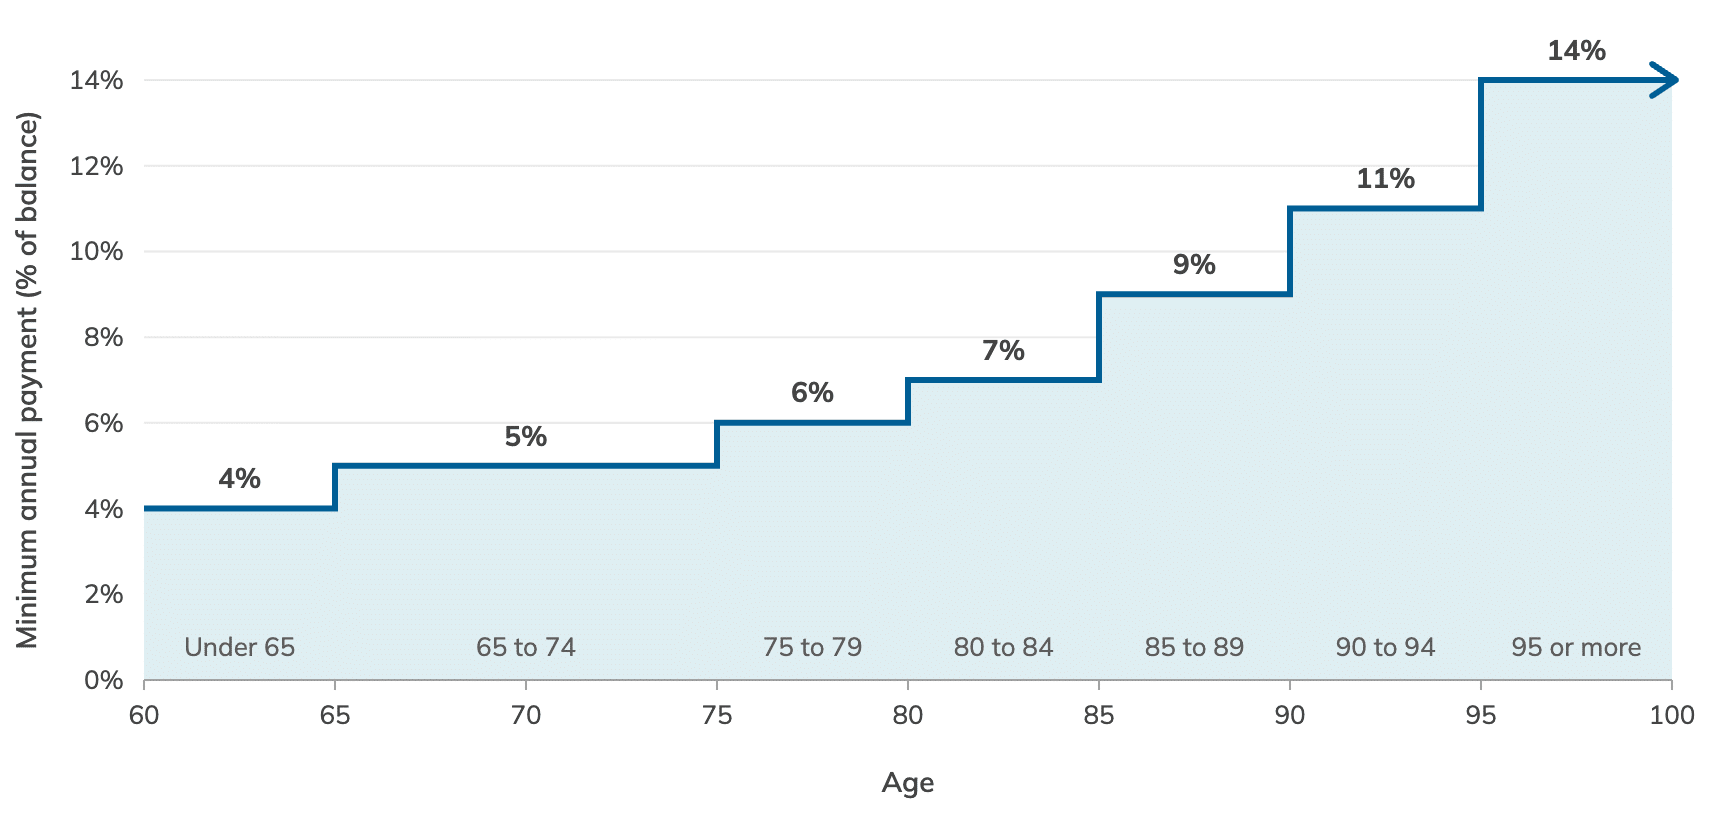
To calculate the annual minimum pension amount, your pension balance is multiplied by a percentage factor that increases as you age. The chart and table below show the minimum pension percentage factor for each age group.
Minimum annual pension payment by age
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7
| Age of beneficiary | Percentage factor |
|---|---|
| Under 65 | 4% |
| 65 to 74 | 5% |
| 75 to 79 | 6% |
| 80 to 84 | 7% |
| 85 to 89 | 9% |
| 90 to 94 | 11% |
| 95 or more | 14% |
Source: SIS Act
Payments must be received at least annually between 1 July and 30 June each financial year, although many retirees opt to receive fortnightly, monthly, or quarterly payments. Annual minimum payment amounts are rounded to the nearest ten whole dollars. If the amount ends in an exact five dollars, it is rounded up to the next whole ten dollars.
Calculating the first payment
If you start a simple account-based pension after 1 July, the minimum amount for the first year is calculated on a pro-rata basis according to the number of days remaining in the financial year, including the start day (see example below).
If your super pension commences on or after 1 June, no payment is required in that financial year.
First-year minimum pension payment by start date
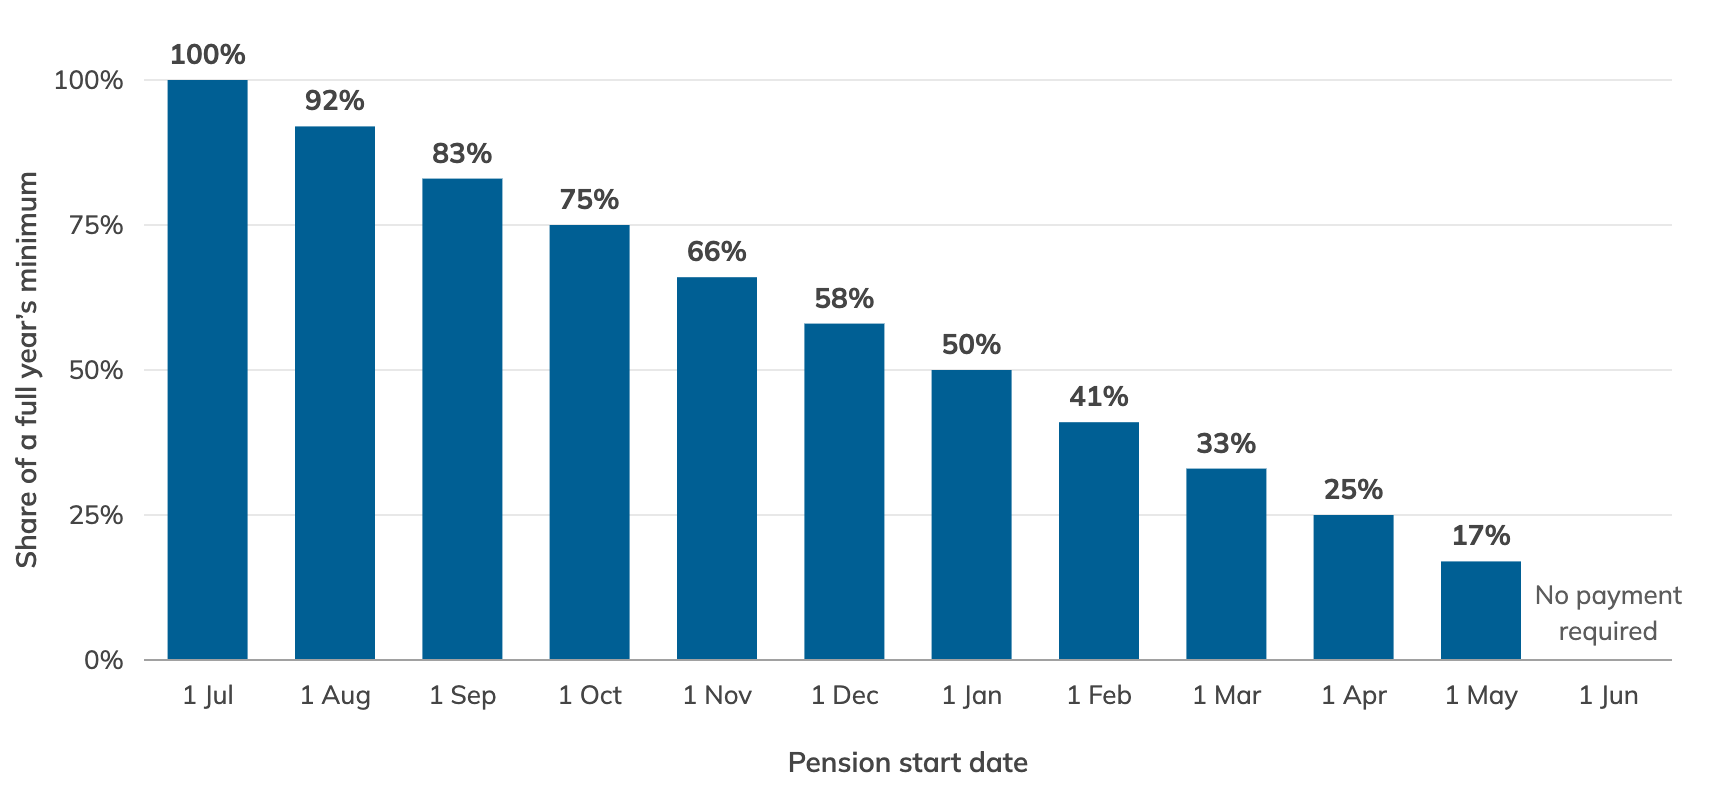
Shown as a share of a full year’s minimum. Based on a 365-day financial year, counting the start date.
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7. SuperGuide calculations
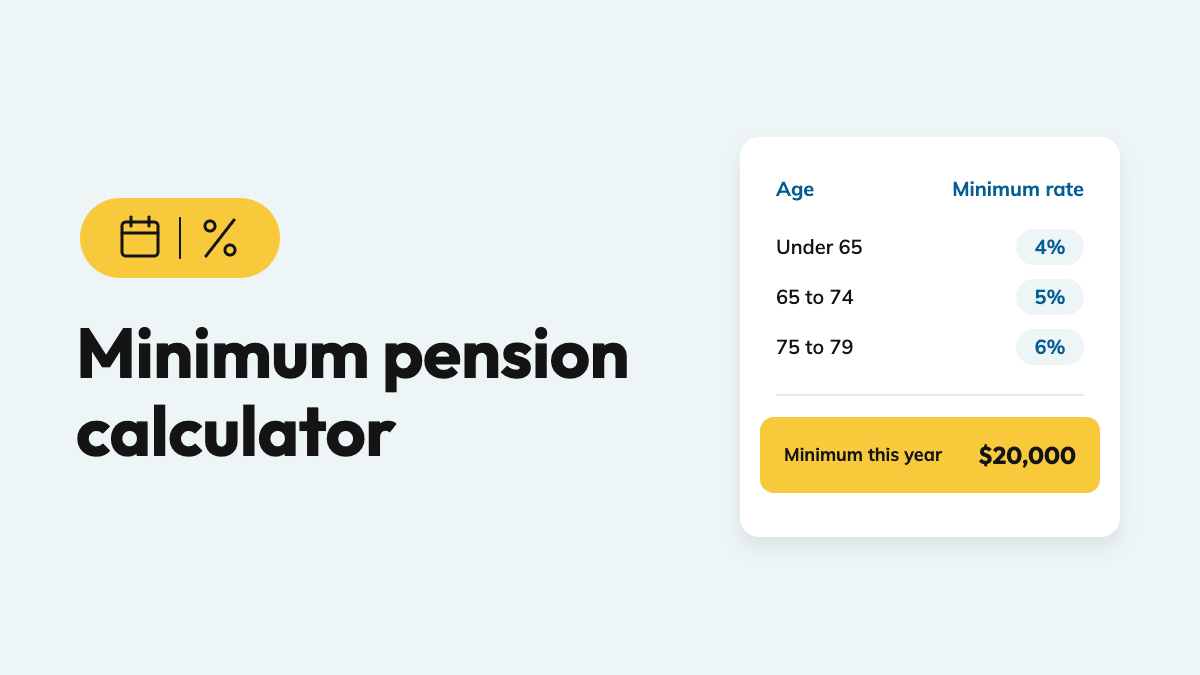
Minimum pension drawdown calculator
Work out your minimum pension payment for a full year, or for the first year of a new pension. Available to SuperGuide members.
Common questions about the minimum pension drawdown rules
Q: What’s the difference between an account-based pension and a non-account-based pension?
A: Currently, most super pensions are account-based, so called because the pension is paid from a super account held in your name. An account-based pension stops when the balance runs out.
Some account-based products are available that guarantee to pay income for life by imposing restrictions on your withdrawals and adding insurance (at additional cost).
For SMSFs with account-based pensions, the amount supporting the pension must be allocated to a separate account for each member.
Defined benefit pensions, as well as some lifetime pensions offered by super funds and annuities paid by life insurance companies, are non-account-based pensions.
In a non-account-based pension, assets are pooled among all members and the provider pays you a regular income over a fixed period or for life. Unlike account-based pensions, these income streams do not have an identifiable account balance in the member’s name.
All pensions except deferred annuities must make payments at least annually.
Q: I understand I need to draw down 5% of my super at some point, but when does that start? I’m 66 and retired.
A: The requirement to make withdrawals is triggered when you start a pension (income stream) with your super balance.
Any money kept in the accumulation phase of super can stay there indefinitely with no requirement to make minimum withdrawals. Once you have met a condition of release, such as turning 65, you can also withdraw lump sums from your accumulation account without starting a pension.
The pension (retirement) phase is attractive because investment earnings are tax free. Many people choose to start pensions even if they don’t need the minimum withdrawals for spending.
The 5% minimum you have mentioned applies to people aged 65 to 74 who have a simple account-based pension.
Different withdrawal rates and payment settings apply to other types of pensions. A deferred annuity even allows you to purchase an income stream that will not start making payments until you reach a set age.
Q: Why does the government set a minimum pension payment?
A: The minimum percentage factor for simple account-based pensions is set to satisfy the sole purpose test. That is, that super (and the generous tax concessions it receives) is designed to provide retirement income. It’s not intended to be used as a tax-effective way to transfer wealth to the next generation.
The minimum ensures a reasonable amount of income is withdrawn each year, and in exchange the account-holder is granted tax-free investment earnings on the assets supporting the pension.
The requirement to make withdrawals does not exist in accumulation accounts, where investment earnings remain taxable.
There is no maximum annual drawdown other than the balance of your account, unless it is a transition-to-retirement (TTR) pension that is not in retirement phase, in which case the maximum is 10% of your pension account balance.
Q: What happens if I don’t meet the minimum pension requirement? Can I fix it at the start of the next financial year?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: How does the minimum work if I have more than one account-based pension?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: If I’m 74 on 1 July and turn 75 before the end of the financial year, does the rate for 65 to 74 still apply for that year?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: I moved part of my super into a pension and left the rest in accumulation, which still receives contributions. Is the minimum worked out on my pension balance only, and does that balance change each year?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: If my minimum pension is $15,000 and I take it in three payments of $5,000, but take $7,000 on the last withdrawal, is the extra $2,000 a lump sum or part of my minimum?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: I receive my minimum pension payment fortnightly but don’t need the money. Can I have it paid as a single payment at the end of the financial year instead?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: If I start a retirement phase pension on 1 July with a minimum of $50,000 for the year, then move it back to accumulation in December, do I need to draw the full $50,000 or only half?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: I’m in pension phase and have to withdraw 4% before the end of the financial year. What are my options with the share market so volatile?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: My 4% withdrawal from my new pension is about $50,000 a year, but I don’t need that income as I have gone back to work. What is the best way to invest it? I have already used up my three-year bring-forward.
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: Does the amount I withdraw from my super pension affect my Age Pension?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
The bottom line
Under the super rules, people with account-based super pensions are required to withdraw a minimum amount each financial year. The minimum amount is expressed as a percentage of your pension account balance, beginning at 4% when you’re aged under 65 and gradually increasing to a rate of 14% from age 95.
Failure to withdraw the minimum amount could result in your super pension losing its tax-free status.
There is no maximum withdrawal amount unless you are under 65 and using a transition to retirement pension. If you are unsure about how much you could safely withdraw each year without running the risk of your savings not lasting the distance, we recommend you seek independent financial advice.


Leave a Reply
You must be logged in to post a comment.