


In this guide
If you’re on the final stretch to retirement and would love to start winding back your working hours but don’t think you can afford it, listen up.
Ditto if you plan to keep working full time for a while longer and want to boost your super but haven’t got the ready cash to make extra contributions.
Help could be at hand in both cases in the form of a superannuation transition to retirement pension or income stream (TTR) that provides limited tax-free withdrawals from super while you’re still working. This tax-free income can be used to either:
- Supplement your income and facilitate a move to part-time work or cover other costs
- Make concessional contributions to super you couldn’t otherwise afford, reducing tax and boosting your super balance.
The maximum annual withdrawal from a TTR pension is 10% of its balance and the minimum is 4% of the balance.
Am I eligible?
If you’ve turned 60 but you’re not yet 65 and you’re still working, you’re good to go. You don’t need to cut back your working hours or change jobs. You’re also eligible if you’re in this age group and you’re not working right now but you haven’t retired permanently or left a job since your 60th birthday.
A retirement phase pension is available (instead of a TTR) when you’re 65 or older, you’re 60 to 64 and have permanently retired from work, or you’ve left a job after your 60th birthday.
If you’ve retired after 60, you can access all your super without a TTR. The same applies if you’re 60 or over and leave one of several jobs, because ending any job after 60 meets the retirement condition of release for the super you hold at that point. Learn more about conditions of release.
Which super pension you can start, by age and work status
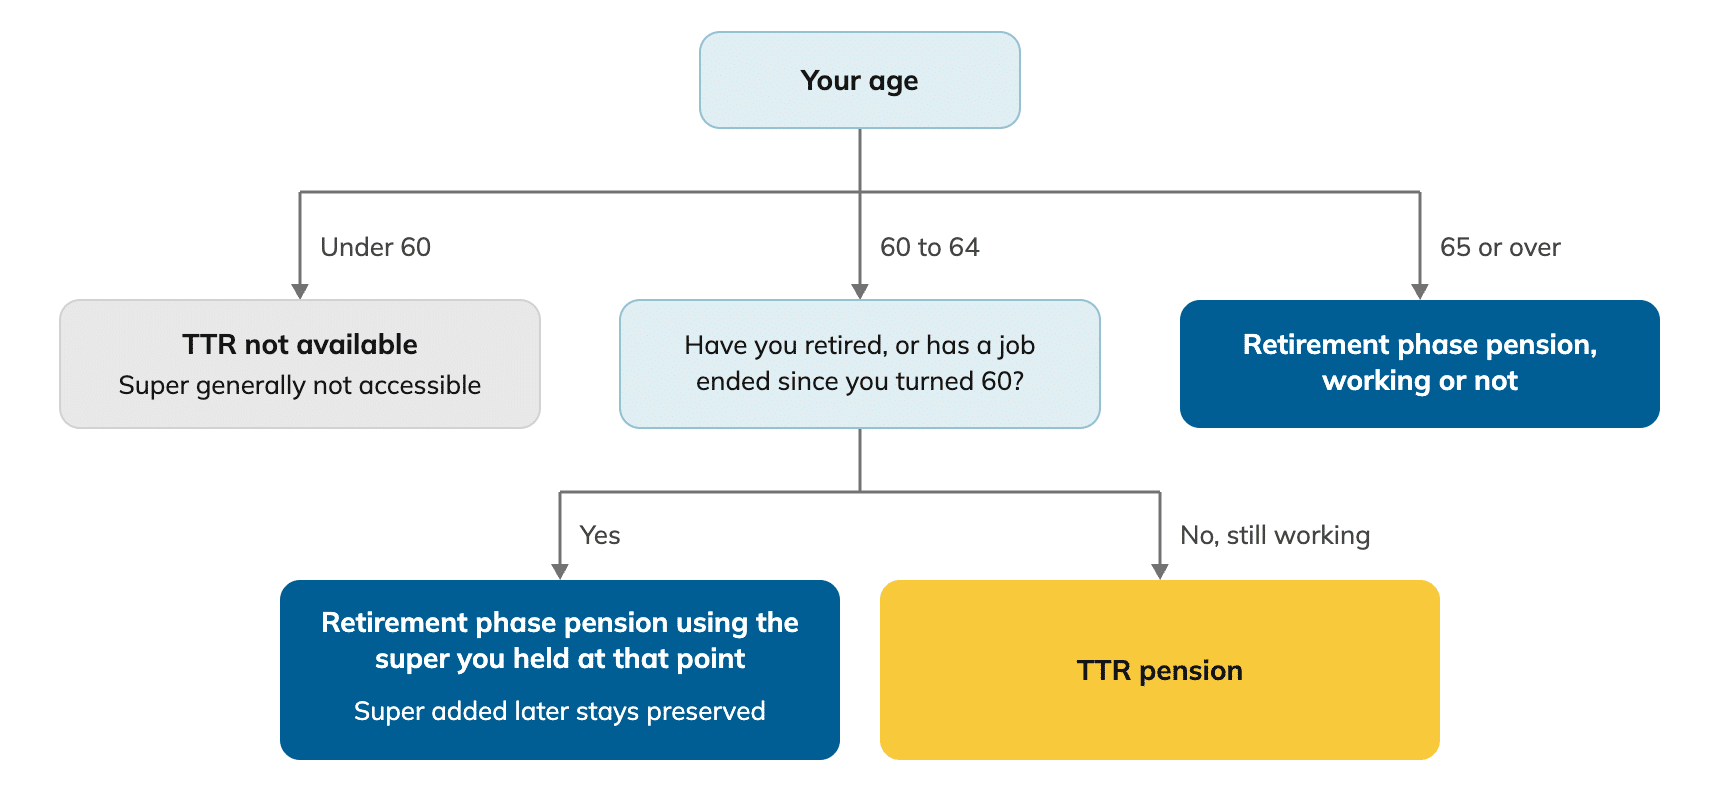
Other conditions of release, such as permanent incapacity, severe financial hardship or terminal illness, are not shown.
Source: SuperGuide
If you’re in a defined benefit fund, you may not be able to commence a TTR, or you may only be able to use a portion of your benefit. Only about 10% of Australians are members of defined benefit funds, which tend to be public sector or older corporate funds. If this is you, talk to your fund to find out your options.
Minimum and maximum withdrawals
Required minimum and maximum payments are calculated when you first open your account and then recalculated each financial year on 1 July while you still have a balance in a TTR pension.
The maximum annual payment is 10% of your balance and the minimum is 4%. The minimum is pro-rated when you start a pension partway through the financial year, but the maximum is not. You can start a TTR pension at any time of year. Withdrawals must be taken as pension payments, not lump sums.
What are the advantages?
Withdrawals from TTR pensions are tax free, while investment earnings attract a tax rate of 15% just like super accumulation accounts.
The ability to make tax-free withdrawals prior to retirement is the key benefit of TTR pensions. You can use your payments to make it affordable to reduce your working hours, contribute more to super, or for any other purpose you wish.
Here’s how a TTR pension compares with an accumulation account and a retirement phase pension.
| Feature | Accumulation account | TTR pension | Retirement phase pension |
|---|---|---|---|
| Who can have one | Anyone | Aged 60 to 64 | Anyone who has met a condition of release, such as retiring, leaving a job after turning 60, or turning 65 |
| Contributions | Allowed, with concessional contributions taxed at 15% | Not allowed | Not allowed |
| Tax rate for taxable investment income | 15% | 15% | Tax free |
| Tax on withdrawals | Tax free from 60 | Tax free | Tax free |
| Minimum withdrawal | None | 4% of the balance each year | Age-based, starting at 4% under 65 and rising with age |
| Maximum pension payment | n/a | 10% of the balance each year | No maximum |
| Lump sum withdrawals | Allowed once you meet a condition of release | Generally not allowed | Allowed |
| Counts towards your transfer balance cap | No | No | Yes |
| Social security means tests | Not assessed until you reach Age Pension age | Balance counts in the assets test and is deemed under the income test | Balance counts in the assets test and is deemed under the income test |
Tax treatment shown is for taxed super funds. Members of untaxed government funds are taxed differently. Higher-income earners may pay an extra 15% tax on concessional contributions (Division 293 tax). If your total super balance is very large, Division 296 tax applies to part of your earnings, whichever type of account they’re in.
Concessional contributions to super below the annual concessional cap ($32,500 in 2026–27) are taxed at the low rate of 15%. If your total super balance is below $500,000 on 30 June, you can also contribute more than the standard cap in the following financial year by using the carry-forward measure.
Making concessional contributions can be a valuable strategy if your marginal tax rate is higher than 15%. Combining these contributions with tax-free withdrawals from a TTR pension means you may be able to contribute more than you could otherwise afford.
Example: Using salary sacrifice and TTR to boost super
Jill is 60 and earns $100,000 a year, which puts her in the 32% tax bracket (including the Medicare Levy). She has $310,000 in super and wants to keep working full time until at least age 65, but wishes she could do more to increase her retirement savings. Since she doesn’t have the spare cash to make extra contributions, she decides to take advantage of a TTR strategy.
Jill starts a TTR pension with $300,000, leaving $10,000 in her accumulation account to keep it open for future contributions. She can withdraw a pension of up to $30,000 in the current financial year – 10% of the opening balance of her TTR. She decides to withdraw this amount and salary sacrifice back into her accumulation account to maintain the same take-home pay.
Jill has unused concessional cap space of $82,500 from prior years so she can exceed the standard annual concessional cap without generating excess contributions that are taxed at a higher rate.
To reduce her take-home pay from work by $30,000 per year (and replace it with $30,000 withdrawn tax free from super), Jill salary sacrifices $44,350 in 2026–27. After 15% contribution tax is deducted, this results in $37,697.50 being added to her super account.
The bottom line is an overall tax saving and a net boost to her retirement savings of around $7,700 for the year. This is Jill’s net additional contribution minus the pension income she has withdrawn.
After her employer’s contributions are added, Jill has used up $23,850 of her unused concessional cap space from prior years. If her balance remains under $500,000 on 30 June 2027, she can continue using her remaining available carry-forward amounts in the following financial year.
Jill’s tax and super boost, with and without a TTR, 2026–27
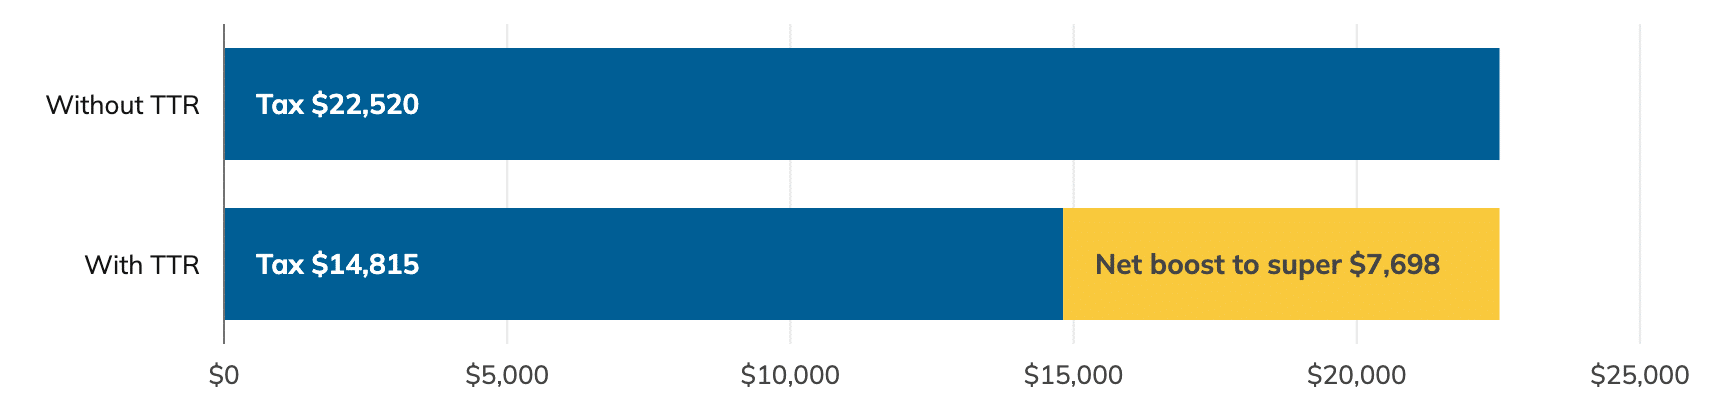
Illustrative example. Jill’s take-home pay is about $77,480 in both cases. With a TTR, she salary sacrifices $44,350 and takes $30,000 in tax-free TTR payments. Total tax is income tax and Medicare levy plus 15% contributions tax on salary sacrifice, using 2026–27 rates. Figures are rounded to the nearest dollar.
Source: SuperGuide calculations
There are also other strategies to consider, including using your pension payments to make non-concessional contributions to super as part of a recontribution strategy or to contribute to your spouse’s account.
What are the drawbacks?
Here are some things to keep in mind:
- The more of your super funds you withdraw during your TTR phase, the less money you’ll have available when you do retire – unless you replace your withdrawals with contributions.
- If you or your partner currently receives any social security payments, a TTR pension may affect your entitlements. The balance of a TTR is assessed in the assets test and used to calculate deemed income in the income test. In contrast, super held in an accumulation account by a person under age 67 is not assessable.
- Your super fund may require you to keep a minimum balance in your accumulation account to maintain any insurance cover you hold through super.
- The tax savings (and super boost) of salary-sacrifice or voluntary contributions into super may not be worthwhile for low- and high-income earners, as illustrated below.
For high-income earners, there may be limited scope to make additional concessional contributions.
How do I get started?
You start a TTR pension by transferring some of your super from your accumulation account into a transition to retirement pension account.
In practice, you contact your super fund and complete its pension application, nominating how much of your balance you want to use.
The transferred funds don’t count towards your transfer balance cap because you’re not in retirement phase. The funds in your TTR pension account will count towards your transfer balance cap once you do retire or turn 65, because the pension will convert into retirement phase. This cap is currently $2.1 million.
You must leave at least a small balance in your accumulation account so that it remains open to receive your employer’s compulsory super guarantee contributions or any voluntary contributions you may want to make.
How a TTR pension works alongside your accumulation account
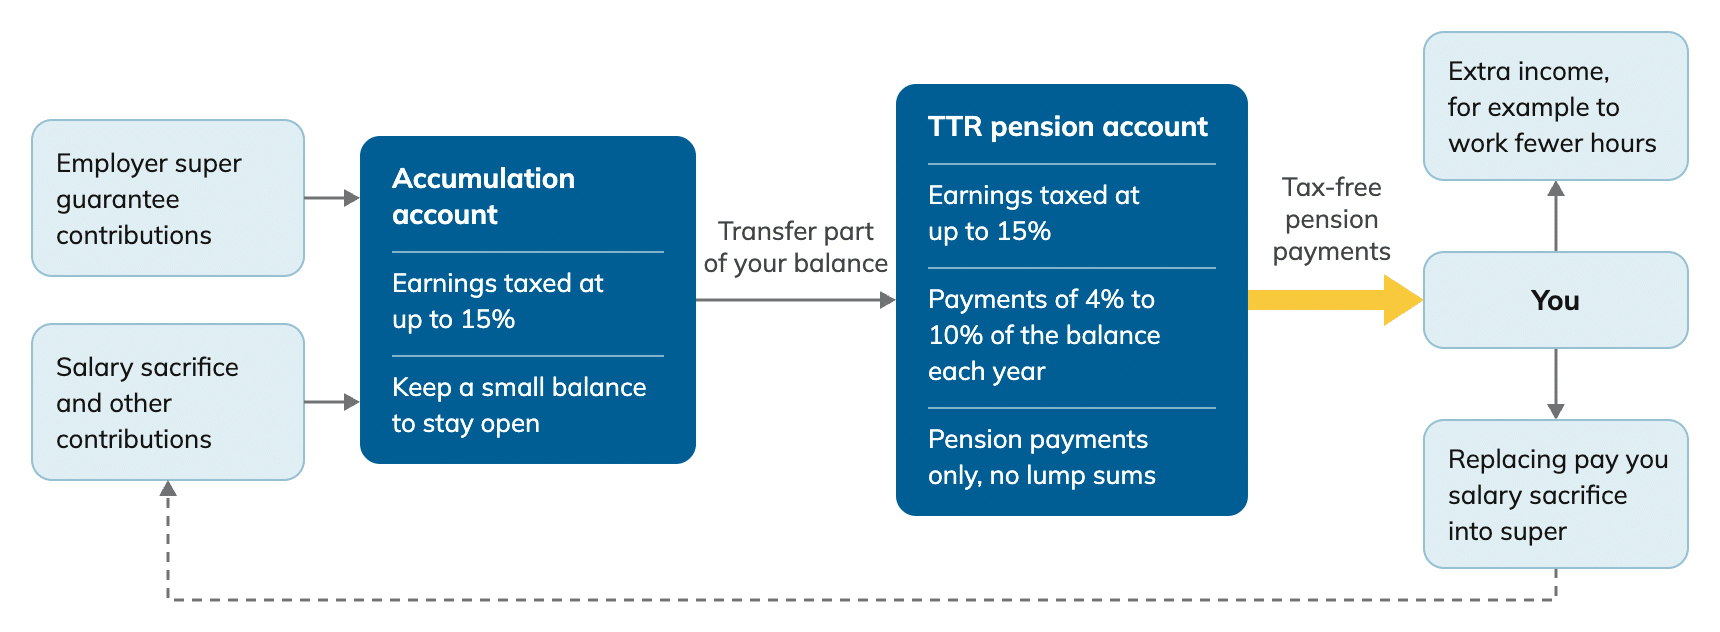
Payment limits are based on the TTR pension balance, calculated each 1 July. The minimum is pro-rated in the first year.
Source: SuperGuide
Investment earnings in both your accumulation and TTR pension accounts are taxed at 15%.
How do I stop a TTR pension?
A TTR pension converts to a retirement phase pension when you meet a superannuation condition of release – unless you choose to transfer it back into the accumulation phase and stop receiving pension payments. This happens automatically when you reach age 65. If you retire before 65, you need to tell your fund you’ve met a condition of release.
When your TTR pension becomes a retirement phase pension, you’ll be entitled to tax-free investment earnings and no upper limit to withdrawals. If you’re still working, you can continue to use the income from your retirement pension to use the same strategies you did for your TTR, but without the maximum limit on your withdrawals.
You can also transfer your pension account balance back into your accumulation account at any time. You must have made at least the pro-rated minimum withdrawal before you stop your TTR pension. For example, if you stop the pension exactly halfway through the financial year, you must have received 50% of that year’s minimum payment before stopping the pension.
How can I top up my TTR with additional contributions?
Superannuation law doesn’t allow contributions to be made into a pension account. When you have a TTR pension, you make withdrawals from the pension account and contributions to your accumulation account.
If a balance builds up in your accumulation account that you would like to use to top up your pension (and increase your maximum withdrawals), you can ask your fund to close your pension and transfer the balance back into your accumulation account.
Once all your money is combined in your accumulation account, you can start a new TTR pension with a higher balance. This is sometimes known as ‘pension refreshing’.
When you combine super accounts, the tax-free and taxable components of your super mix. Combining your accounts could make a strategy to reduce tax on your super after death more difficult or unwind steps you have already put in place.
Can I start a TTR from my self-managed super fund (SMSF)?
Yes, provided this is allowed in your SMSF’s trust deed.
As a trustee you’ll also need to follow your deed’s requirements for starting a pension, which usually include a pension application, trustee minutes or resolutions, valuing the fund’s assets and bringing the fund’s accounts up to date.
If you’re a trustee and want to start a TTR for yourself or another member of your fund, you should get independent professional advice. The rules are complex and not complying can be costly.
Look (for advice) before you leap
Transition to retirement pensions have real benefits for some people but may be less attractive for others. Deciding whether a TTR strategy is appropriate for you is an important decision and will depend on your personal financial circumstances and goals. Because the information in this article is general in nature, and the calculations around TTR pensions can be complex, we suggest you seek independent financial advice before you act.
Common questions about TTRs
TTRs can be confusing, so we’ve addressed some common questions. Many of these questions come from our quarterly member Q&A webinars.
Q: Why have a transition to retirement strategy if you have enough income now for your means?
A: Using a TTR pension for additional income you may need for living costs or debt repayment is only one of the reasons to open one.
If you don’t need additional income, there may be other strategies to consider, including:
- Combining tax-free withdrawals with additional salary sacrifice to super to maintain the take-home pay you need while reducing tax and boosting your super balance.
- Using TTR withdrawals as part of a recontribution strategy to reduce tax for future beneficiaries.
- Withdrawing money from super using a TTR to lower your balance below $500,000 and become eligible to use the carry-forward rule to make concessional super contributions above the annual cap.
- Using TTR payments to contribute to your spouse’s account, potentially keeping both accounts below the transfer balance cap or the large super balance threshold for Division 296 tax.
Q: Can I start multiple transition to retirement pensions at the same time?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: I’m 63. If I start a transition to retirement (TTR) pension, can I stop it before I turn 65, or must it run until then? And do I need to renew or reapply for it each year?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: I am currently 63 and I work 4 days a week as a receptionist in a doctor’s surgery. I also work 2 days a week in the local chemist. I am considering giving up my work at the chemist and then starting a transition-to-retirement pension from my superannuation fund to supplement my income. Can I commence a TTR once I cease my role at the chemist shop?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: If I retire from my work, what happens to my transition to retirement pension? Does it need to stop?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: I’m 61 and still working. If I start a transition to retirement (TTR) pension, do I need to report it for the transfer balance cap? And what happens if my TTR balance is more than my available cap when I turn 65?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: I plan to retire and access my super pension next year after my 60th birthday, but I’d then like to work occasionally as a casual employee in a similar role with the same employer. Is this allowed under the super rules, or is starting a transition to retirement pension my best option?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: If someone opens a transition to retirement account to generate tax-free income and then contributes that income to their spouse’s super as concessional contributions, what potential drawbacks could there be?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: I made a personal contribution and lodged a notice of intent to claim a deduction, then converted my entire super balance to a transition to retirement (TTR) pension a few days later. Can I still split part of that contribution to my working spouse after 30 June?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: Can I use the contribution splitting strategy if my spouse is already accessing benefits under a transition to retirement pension?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: How can I determine if my SMSF allows members to access benefits through a transition to retirement pension?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.


Leave a Reply
You must be logged in to post a comment.