


In this guide
- Income tax rates for 2026–27 (Australian residents)
- Where are you on the road to retirement?
- Income tax rates for 2025–26 (Australian residents)
- How income tax is calculated
- What is the tax-free threshold?
- Tax offsets and deductions
- What is included in assessable income?
- What deductions are you allowed?
- What is taxable income?
- Income tax offsets, levies and surcharges
- Get more guides like this with a free account
The Australian Taxation Office (ATO) collects income tax from working Australians each financial year. In Australia, financial years run from 1 July to 30 June the following year, so we are currently in the 2026–27 financial year (1 July 2026 to 30 June 2027).
The key changes for the 2026–27 year are:
- Reduction of the 16% tax bracket (for income between $18,201 and $45,000) to 15%
- Introduction of a standard deduction (also called the instant tax deduction) of up to $1,000 for work-related expenses
Combined, these changes can mean savings of up to $568 a year for workers earning $46,000 to $135,000 who currently claim little or nothing in work-related expenses, and more at higher tax rates. The benefit of the standard deduction arrives when you lodge your 2026–27 tax return, from July 2027.
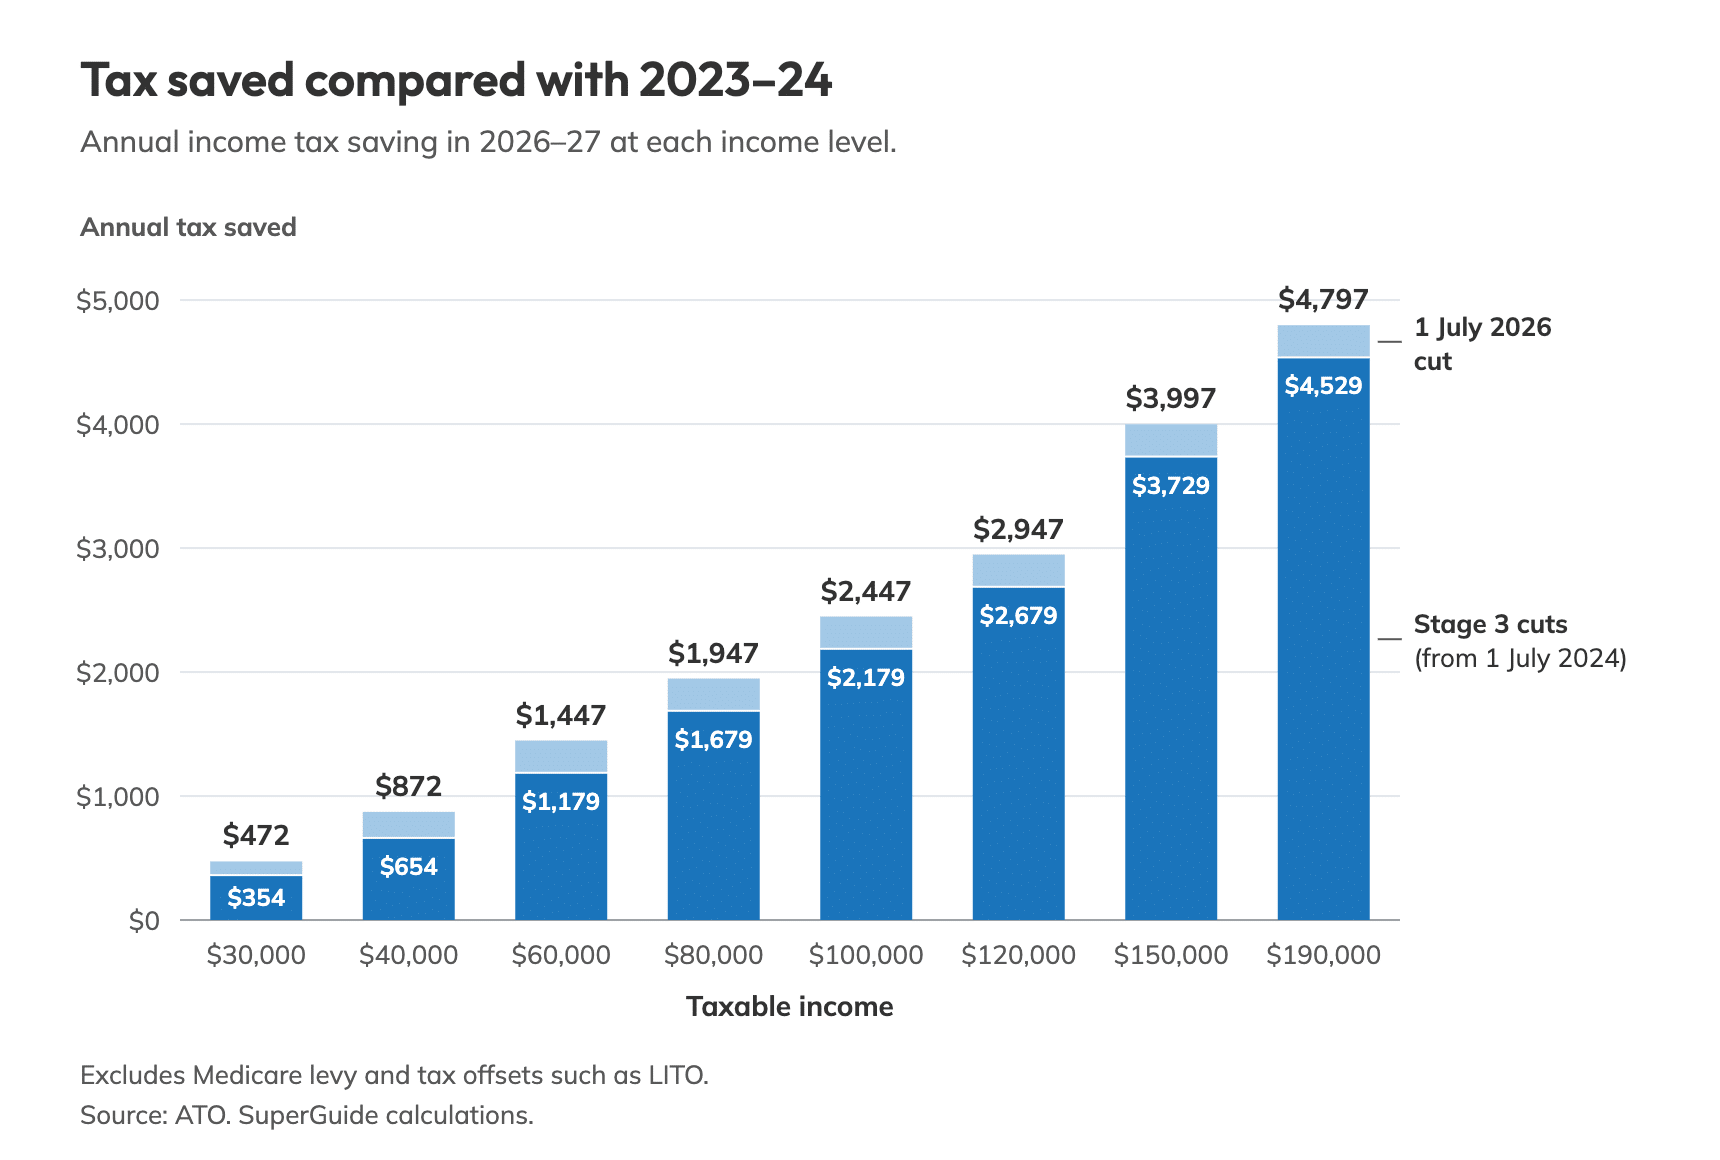
The income tax brackets and rates for Australian residents for this financial year and the previous financial year are listed below.
Income tax rates for 2026–27 (Australian residents)
| Income thresholds | Tax rate | Tax payable on this income |
|---|---|---|
| $0 – $18,200 | 0% | Nil |
| $18,201 – $45,000 | 15% | 15c for each $1 over $18,200 |
| $45,001 – $135,000 | 30% | $4,020 plus 30c for each $1 over $45,000 |
| $135,001 – $190,000 | 37% | $31,020 plus 37c for each $1 over $135,000 |
| $190,001 and over | 45% | $51,370 plus 45c for each $1 over $190,000 |
Where are you on the road to retirement?
Retirement planning isn’t the same for everyone.
Take our 2-minute quiz to find out which stage you’re at and what you could focus on next.
Income tax rates for 2025–26 (Australian residents)
| Income thresholds | Tax rate | Tax payable on this income |
|---|---|---|
| $0 – $18,200 | 0% | Nil |
| $18,201 – $45,000 | 16% | 16c for each $1 over $18,200 |
| $45,001 – $135,000 | 30% | $4,288 plus 30c for each $1 over $45,000 |
| $135,001 – $190,000 | 37% | $31,288 plus 37c for each $1 over $135,000 |
| $190,001 and over | 45% | $51,638 plus 45c for each $1 over $190,000 |
Note: The above amounts do not include the Medicare levy or the impact of tax offsets such as the Low Income Tax Offset (LITO).
Over the last few years both the Coalition and Labor governments have announced income tax cuts that have been applied in stages since 2018. The latest cut took effect from 1 July 2026, with a further cut due from 1 July 2027.
Continue reading to learn how Australian income tax is calculated, including offsets, levies and surcharges that may reduce or increase your income tax.
- How income tax is calculated
- Tax offsets and deductions
- What is included in assessable income?
- What deductions are you allowed?
- What is taxable income?
- Income tax offsets, levies and surcharges
- Low Income Tax Offset (LITO)
- Seniors and Pensioners Tax Offset (SAPTO)
- Medicare levy
- Medicare levy surcharge
- Lifetime Health Cover loading
- Private health insurance rebate
How income tax is calculated
The formula for calculating income tax payable is outlined below:
Assessable income minus Allowable deductions
equals
TAXABLE INCOME
apply tax rates
equals
GROSS TAX PAYABLE
minus tax offsets
equals
NET TAX PAYABLE
plus Medicare levy
minus tax credits and refundable offsets
equals
AMOUNT OWING OR REFUND
A common misunderstanding is that once your income hits a tax bracket, your whole income is taxed at that rate. Rather, once your income reaches a higher tax bracket, only the amount of income above that threshold is taxed at the higher rate.
For example, if you earn $50,000 in 2026–27 you are in the 30% tax bracket, which applies to income between $45,001 and $135,000. However, your whole income is not taxed at 30% – just the amount over $45,000 – which in this case is $5,000.
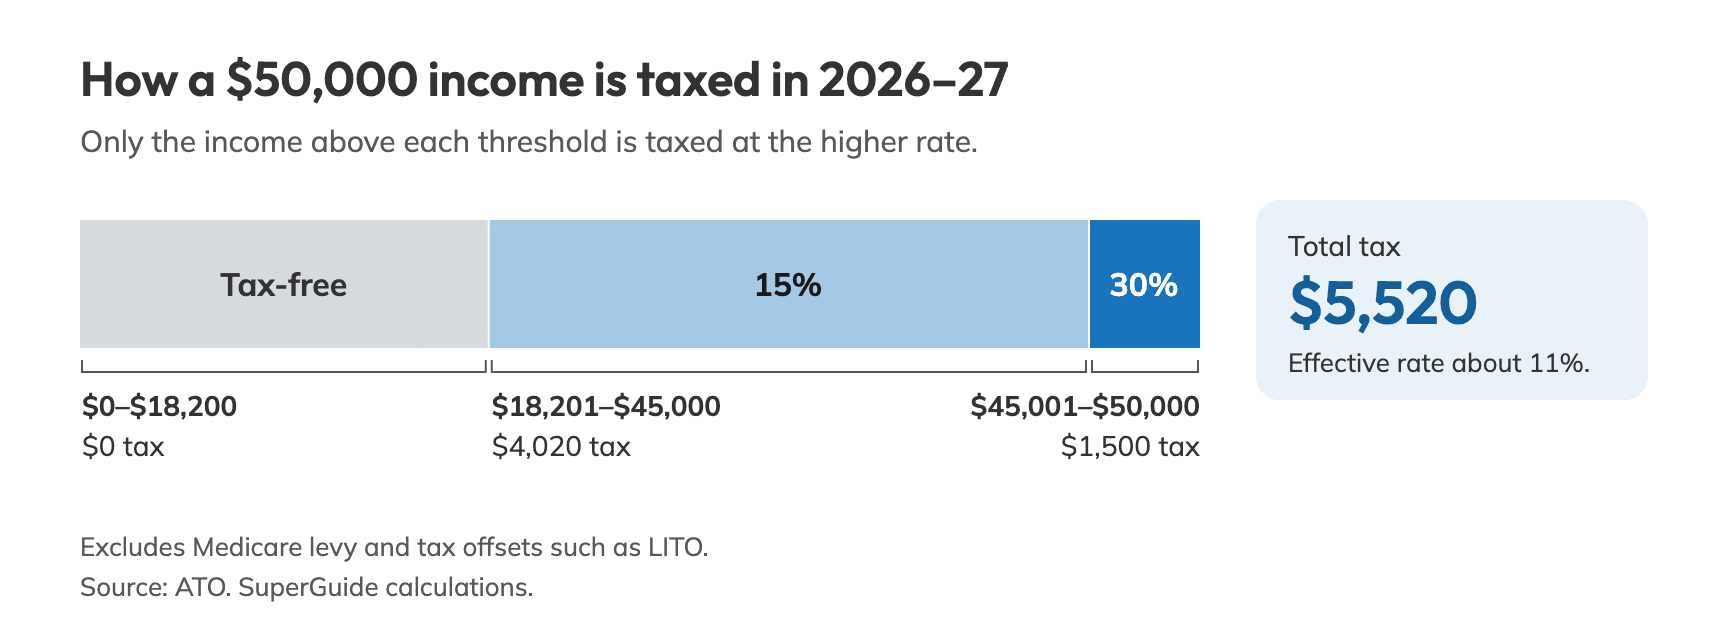
- The first $18,200 is tax free
- Then the amount earned between $18,201 and $45,000 is taxed at 15%. This equals $4,020 in tax.
- Then the amount earned between $45,001 and $50,000 is taxed at 30%. This equals $1,500 in tax.
- This totals $5,520 in tax – which amounts to an effective tax rate of approximately 11% on your total income of $50,000.
Note that this does not include offsets such as LITO, or the Medicare levy. All of these are explained below.
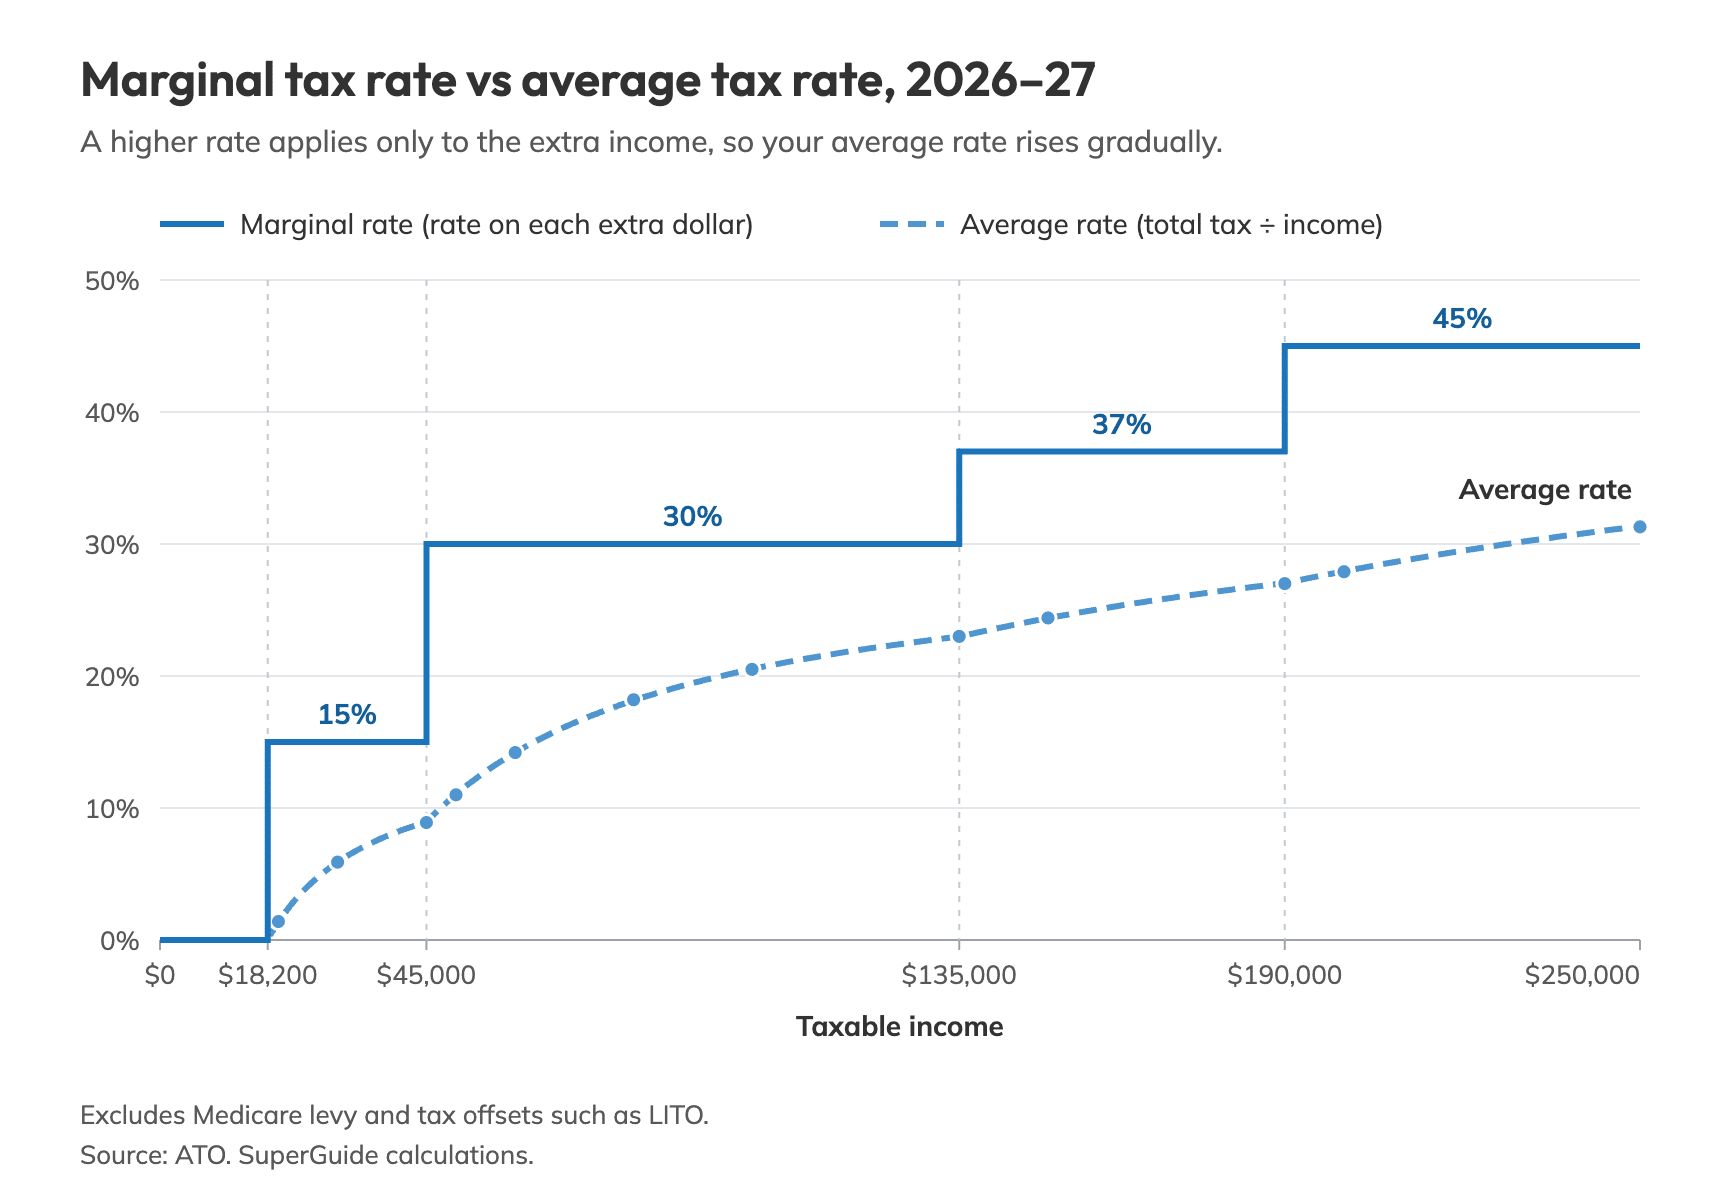
 to 0,000 in 2026–27. The marginal rate steps up from 0% to 15% at ,200, 30% at ,000, 37% at 5,000 and 45% at 0,000. The average rate rises smoothly, from 1.4% at ,000 to 11.0% at ,000, 20.5% at 0,000, 27.0% at 0,000 and 31.3% at 0,000, and always stays below the marginal rate." class="has-border-color has-primary-tint-20-border-color" style="border-width:1px;border-top-left-radius:20px;border-top-right-radius:20px;border-bottom-left-radius:20px;border-bottom-right-radius:20px" data-lazy-src="https://www.superguide.com.au/wp-content/uploads/2026/09/2-marginal-vs-average-rate-2026-27.png"/>
What is the tax-free threshold?
The tax-free threshold refers to how much you can earn in a financial year before you are liable to pay tax. For Australian residents the tax-free threshold is currently $18,200, meaning the first $18,200 of your income is tax free, but you are taxed progressively on income above that amount. This is why Australia has what is called a progressive tax system.
Tax offsets and deductions
Tax offsets or credits reduce the tax payable on taxable income, but tax offsets should not be confused with deductions.
Deductions reduce a taxpayer’s assessable income while tax offsets directly reduce the amount of tax payable.
What is included in assessable income?
Your assessable income must be declared on your tax return each year. It includes any of the following:
1. Employment income
This includes any income you receive for full-time, part-time or casual work. Examples of employment income are:
- Salary, wages, commissions, bonuses, parental leave pay and payments from a work-related insurance scheme (such as income protection, sickness or accident payments or workers compensation).
- Any allowances that you may receive from your employer, such as car, travel, clothing, laundry, meal, working conditions or special duties or qualifications allowances.
- Any other income (like tips, awards or discounted employee shares).
- Any lump sum payments, such as when you leave a job and are paid out for any unused leave.
Note: Reportable fringe benefits, such as private use of a company car or private expenses paid under a salary packaging arrangement, are not assessable income and you don’t pay income tax on them. They appear on your income statement if the total taxable value of certain fringe benefits you receive in the fringe benefits tax (FBT) year (1 April to 31 March) is more than $2,000. They are taken into account for some income tests, including the Medicare levy surcharge and some government benefits.
2. Super pensions and annuities
If you’re receiving a pension from your super fund, it may have three different components:
- A taxed element (where your fund has already paid tax)
- An untaxed element (where tax still needs to be paid)
- A tax-free element (where no tax is payable).
Depending on your age, you may need to declare both the taxed and untaxed elements as income in the financial year you receive the payments, so that your overall tax obligation (or refund) can be determined by the ATO.
If you’re receiving regular income from an annuity, it will also usually have taxable and tax-free components. You’ll need to declare the taxable components.
3. Government payments
If you receive government payments such as the Age Pension or Carer Payment, taxable payments must be declared on your tax return. Some tax-free government payments may also need to be declared because they can affect your eligibility for tax offsets and other benefits.
4. Investment income
This can include:
- Interest you receive from accounts you have with banks or other financial institutions
- Share dividends or returns from managed funds
- Rent from an investment property
- Capital gains you make on the sale of an asset.
5. Business, partnership and trust income
Any income you receive from running a business must be declared. If you’re a sole trader, you don’t need to lodge a separate business tax return.
If you’re in business in partnership with others, you must declare your share of the partnership’s income or loss as assessable income on your tax return.
If you’re a beneficiary of a trust, you must declare your share of the trust’s income in your tax return, even if it remained in the trust and you didn’t actually receive it.
6. Foreign income
If you’re an Australian resident for tax purposes, you must declare any foreign income you receive, even if it’s already been taxed overseas. The ATO uses a system of credits and exemptions to work out if Australian tax is payable on any foreign income you’ve earned.
7. Crowdfunding income
If you’ve raised any income for a project or venture via crowdfunding, some of it may be taxable if you’re carrying on a business or other profit-making scheme.
Some of the seven types of assessable income listed above will be automatically provided to the ATO each year by your employers and financial institutions where you have money invested.
There are also other payments you might receive that aren’t included in your assessable income. Common examples include:
- Lump sum payments from insurance policies, such as for total and permanent disability
- The tax-free component of any eligible termination payments you receive when you leave an employer
- Genuine redundancy payments (up to certain limits based on your length of service)
- Child support or maintenance payments.
What deductions are you allowed?
Eligible deductions reduce your assessable income and therefore the amount of tax you have to pay. The most common deductions are:
1. Work-related expenses
These include:
- Vehicle and travel. You can claim vehicle and travel expenses if you personally incur them as part of carrying out your work duties and you aren’t reimbursed by your employer (for example, if you do deliveries using your own vehicle). You can also claim for any private costs of travelling between your employer’s different locations. However, you can’t claim the cost of travelling to and from work and your home.
- Clothing, laundry and dry-cleaning. You can claim for the cost of buying and cleaning work clothing provided the clothing falls into at least one of the following categories:
- It’s occupation-specific
- It’s protective
- It’s a compulsory uniform.
- Home office. If you regularly work from home, you can claim the cost for work-related home office expenses, including a portion of your home’s running expenses (like phone, electricity and internet costs) based on your dedicated work area, as well as any work-related equipment you buy.
- Phone and internet. If you’re paying for your own phone and internet connections and you use them for work, you can claim the percentage that relates to work use.
- Overtime meals. If you get an overtime meal allowance as part of your employment conditions (and which you must include in your assessable income), you can claim up to that amount as an expense if you’ve used it.
- Self-education. You can claim the cost of self-education expenses, such as costs associated with a course that leads to a formal qualification, provided they relate directly to your current employment. But you can’t claim repayments for any government assistance you receive to take a course (such as the Higher Education Loan Program).
- Tools and equipment. If you need to buy tools and other equipment to earn an income, you can claim a deduction for all or some of the cost, depending on the percentage of work-related and personal use.
- Other work-related expenses. This includes items like income protection insurance premiums (but not if you hold and pay for the insurance inside your super fund), union fees and any personal costs associated with attending work-related seminars or workshops.
2. The cost of managing your tax affairs
You can claim the cost of managing your tax affairs, including the cost of advice for preparing and lodging your tax return and business activity statements (BAS).
3. Gifts and donations
You can claim the cost of any charitable gifts or donations you make to ‘deductible gift recipients’. You can’t claim a donation if you received a personal benefit in exchange for your gift or donation, even if it’s a ticket to win a prize.
4. Interest, dividend and other investment income deductions
Expenses associated with earning assessable interest, dividends, rent or other investment income (like bank fees, interest on money borrowed to buy shares that have provided you with dividends, or investment management fees).
5. Personal super contributions
If you make a personal tax-deductible contribution to your super fund, up to the annual limit of $32,500 in 2026–27, you can claim a tax deduction provided you complete an ATO form and send it to your super fund. Your super fund will tax your contribution at the concessional super rate of 15%, instead of your marginal tax rate.
When claiming any tax deduction, it’s important to keep records so that you can substantiate your claim if you’re ever audited by the ATO.
What is taxable income?
Your taxable income can be minimised by reducing your assessable income or increasing your deductions. For example, a negative gearing investment strategy relies on offsetting an investment loss (after deducting loan interest and other costs from your investment income) against other income. In this case, the investor is increasing their deductions to reduce their taxable income and tax payable.
Similarly, salary sacrificing some of your pre-tax income into super reduces your assessable income. Salary-sacrifice contributions are deducted at the time you are paid, which reduces your gross (assessable) income. This in turn indirectly reduces your taxable income. Moreover, the super contribution (up to an annual cap of $32,500 in 2026–27) is generally taxed at a concessional rate of 15% on the way into your super fund, instead of your marginal tax rate.
Income tax offsets, levies and surcharges
Income tax offsets help lower income earners who are Australian residents reduce their tax bill. Combined with the tax-free threshold of $18,200, the Low Income Tax Offset (LITO) effectively allows you to earn up to $22,866 in 2026–27 before any income tax is payable.
Low Income Tax Offset (LITO)
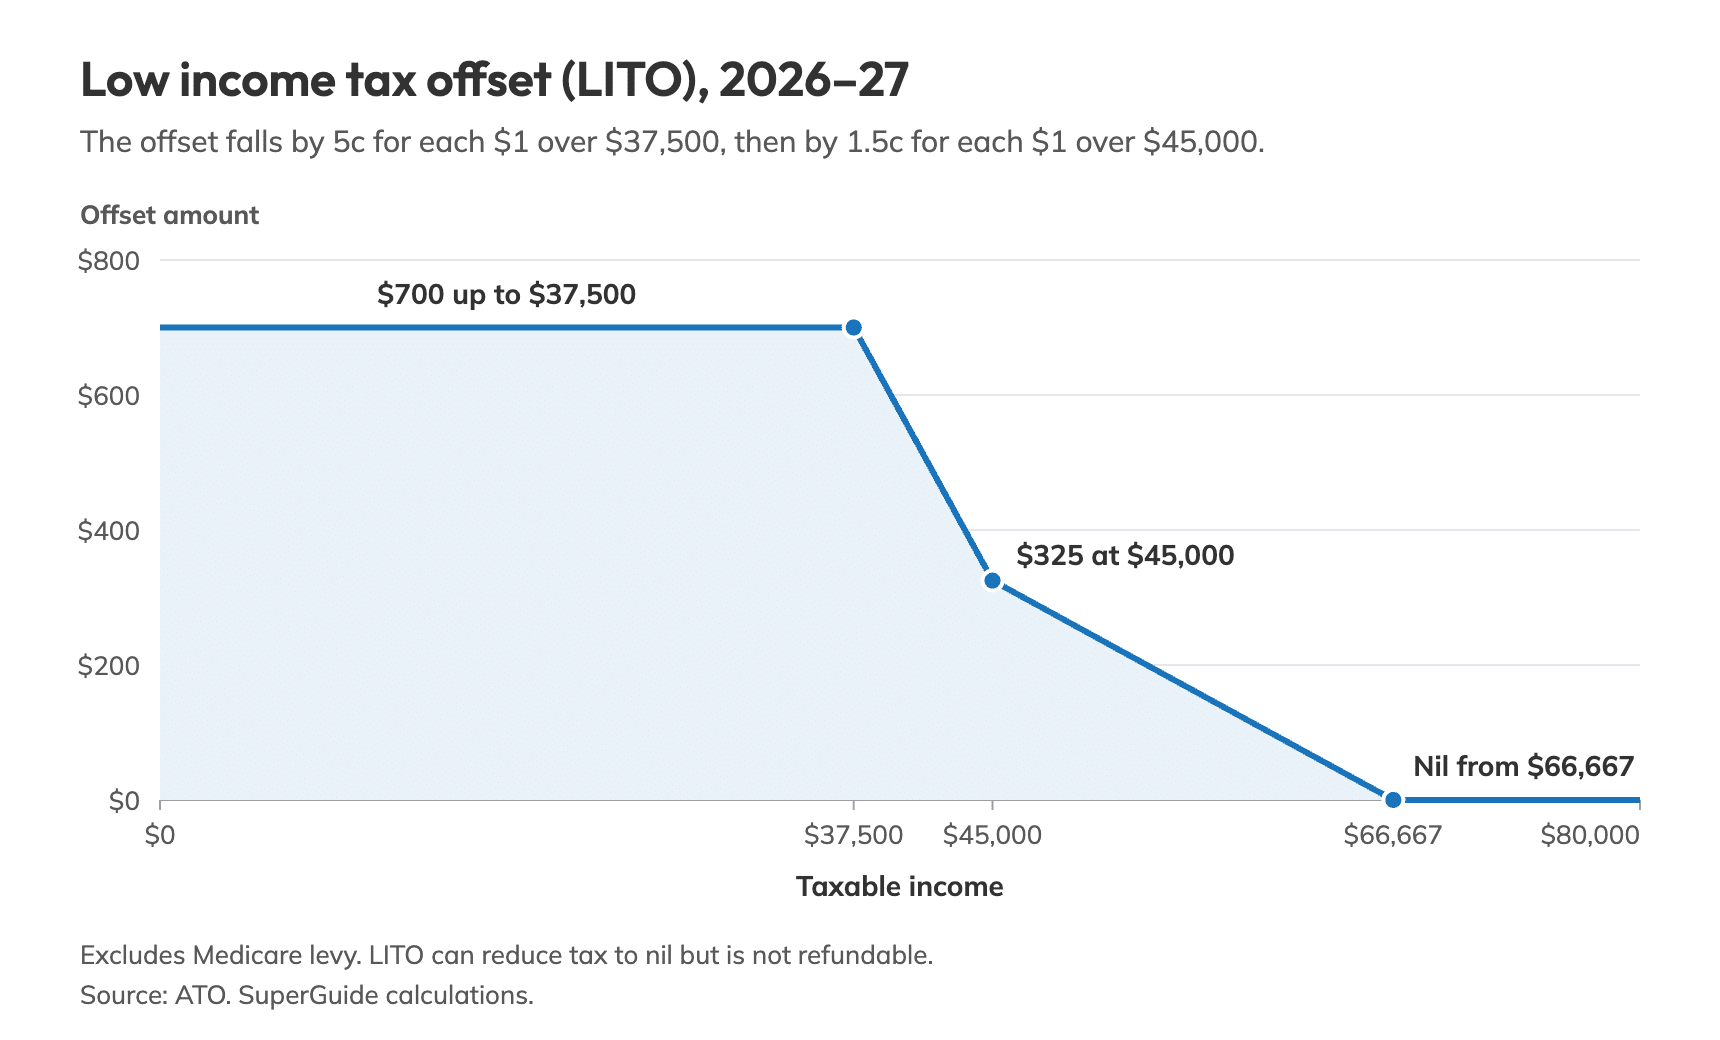
The Low Income Tax Offset (LITO) is available to Australian residents with annual taxable income not more than $66,667.
The maximum offset of $700 applies to taxable incomes below $37,500 and gradually reduces to nil for incomes above $66,667.
Seniors and Pensioners Tax Offset (SAPTO)
As the name implies, SAPTO is a tax offset available to eligible Australian seniors and pensioners. In some cases, it can eliminate a recipient’s tax liability and their need to lodge a tax return.
Medicare levy
Medicare gives Australian residents access to universal health care. It is partly funded by the Medicare levy, which is 2% of your taxable income. You pay this levy in addition to the tax you pay on your taxable income.
Your employer will generally withhold enough tax to cover the levy, but the exact amount will be determined by the ATO when you submit your tax return. Australian residents for tax purposes generally pay the Medicare levy, although reductions and exemptions can apply.
For 2025–26, you do not have to pay the Medicare levy if your taxable income is $28,011 or less, and the amount of Medicare levy you pay will be reduced if your taxable income is $35,013 or less. For families, the thresholds are $47,238 and $59,047 respectively. The thresholds for 2026–27 had not been announced at the time of writing.
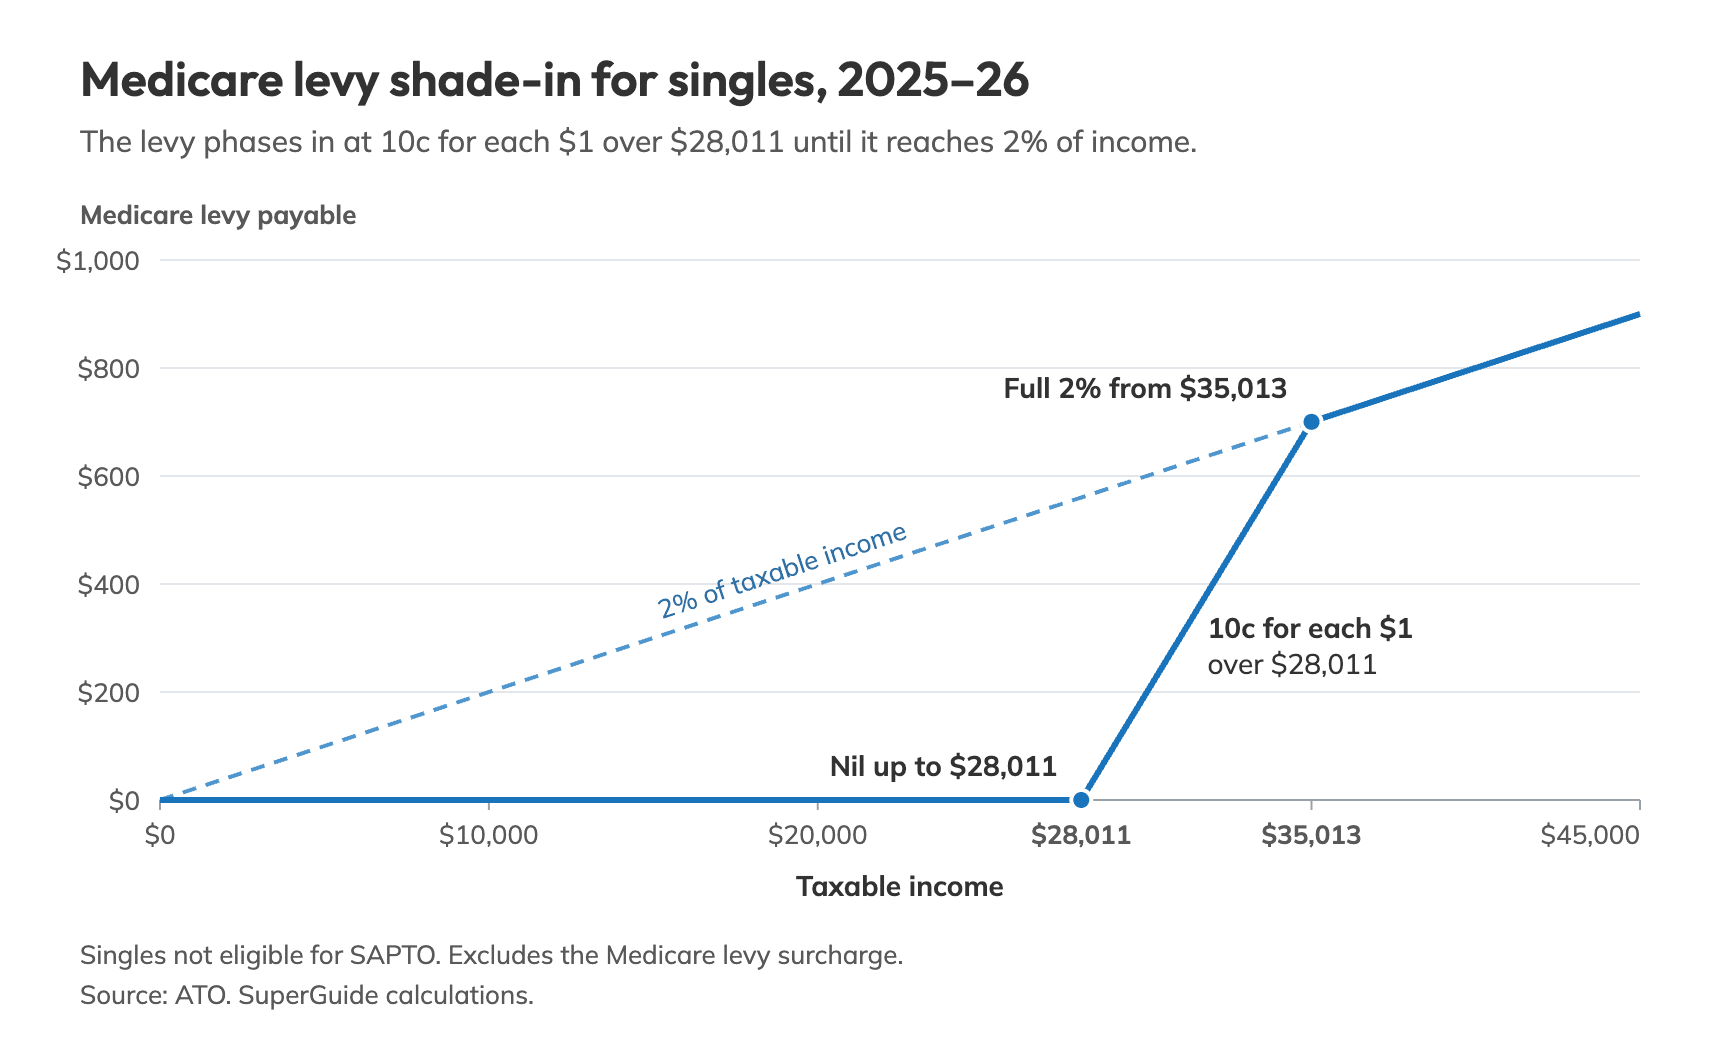
If you are entitled to the Seniors and Pensioners Tax Offset (SAPTO) you do not have to pay the Medicare levy if your taxable income is $44,268 or less, and the amount of Medicare levy you pay will be reduced if your taxable income is $55,335 or less. For families eligible for SAPTO, the thresholds are $61,623 and $77,028 respectively.
Medicare levy surcharge
An additional Medicare levy surcharge (MLS) is payable if your income for MLS purposes is above a certain threshold and you don’t have an appropriate level of private hospital cover. Your income for MLS purposes, which decides whether you pay the MLS and at what rate, includes:
- Taxable income
- Total reportable fringe benefits
- Any amount on which family trust distribution tax has been paid
- Total net investment losses (such as negative gearing deductions)
- Reportable super contributions.
The surcharge itself is calculated at 1%, 1.25% or 1.5% of your taxable income, total reportable fringe benefits and any amount on which family trust distribution tax has been paid. Net investment losses and reportable super contributions count towards the income test but are not surcharged.
Medicare levy surcharge income thresholds
The Medicare levy surcharge (MLS) thresholds are as follows:
| Tiers for 2026–27 | Income threshold for individuals | Income threshold for families | Medicare levy surcharge |
|---|---|---|---|
| Tier 0 | Up to $105,000 | Up to $210,000 | 0% |
| Tier 1 | $105,001 – $123,000 | $210,001 – $246,000 | 1% |
| Tier 2 | $123,001 – $164,000 | $246,001 – $328,000 | 1.25% |
| Tier 3 | $164,001 and above | $328,001 and above | 1.5% |
Lifetime Health Cover loading
A person who does not have private health (hospital cover) insurance on their Lifetime Health Cover base day (usually 1 July following the 31st birthday) but who later in life decides to take out private hospital cover will pay a 2% Lifetime Health Cover (LHC) loading on top of their premium for every year they are aged over 30.
The LHC loading also applies if a person aged over 30 cancels their private health insurance and then later decides to take out private health insurance again. There is an exception, known as ‘days of absence’, which permits you to be without hospital cover for periods totalling 1,094 days (three years less one day) during your lifetime, without affecting your loading. This covers small gaps, such as switching from one fund to another.
However, if the total gap period exceeds 1,094 days, you will pay a 2% loading on rejoining private hospital cover. The loading increases by 2% for every year without cover after that. The LHC is removed after ten continuous years of private health insurance cover. The private health insurance rebate (see below) has not applied to the Lifetime Health Cover loading since 1 July 2013.
Private health insurance rebate
The private health insurance rebate is an amount the government contributes towards the cost of private health insurance premiums. The rebate can be claimed for premiums paid for a private health insurance policy that provides private patient hospital cover or combined hospital and general cover. The rebate is income tested, which means eligibility depends on your income.
The income thresholds and rebate rates that apply from 1 July 2026 to 31 March 2027 are listed in the tables below. The rebate is higher if the oldest person covered by the policy is aged 65 or over. New rebate rates will apply from 1 April 2027.
The government has introduced legislation that would reduce the higher rebate for people aged 65 and over to the rate for those under 65, from 1 April 2027. This change is not yet law.
Rebate income thresholds for 2026–27
| Family status | Base tier | Tier 1 | Tier 2 | Tier 3 |
|---|---|---|---|---|
| Singles | Up to $105,000 | $105,001–$123,000 | $123,001–$164,000 | $164,001 or more |
| Families | Up to $210,000 | $210,001–$246,000 | $246,001–$328,000 | $328,001 or more |
Rebate rates from 1 July 2026 to 31 March 2027
| Age of oldest person covered | Base tier | Tier 1 | Tier 2 | Tier 3 |
|---|---|---|---|---|
| Under 65 | 24.118% | 16.079% | 8.038% | 0% |
| 65 to 69 | 28.139% | 20.098% | 12.058% | 0% |
| 70 and over | 32.158% | 24.118% | 16.079% | 0% |
The family income threshold increases by $1,500 for each dependent child after the first. Source: ATO
Get more guides like this with a free account
better super and retirement decisions.


Leave a Reply
You must be logged in to post a comment.