


In this guide
In the old days, staying in a full-time job until you retired was the norm, but in the brave new world of employment working full-time until you’re age 65 – or even 60 – is becoming much more of a challenge.
More and more employers seem unwilling to retain or hire older employees. Many workers are finding staying in paid employment once you’re in your sixties is a big ask, despite discriminating against someone on the basis of age being illegal.
If you lose your job in your 50s, you could find yourself living up to another 30 or 40 years without paid employment. This can leave you facing a scary financial chasm if your career ends unexpectedly.
The situation is made more challenging as most people can’t access their super tax free until age 60 and eligibility for government financial support through the Age Pension is now set at age 67.
What is age discrimination?
Age discrimination in the workplace is unlawful and occurs if a person is treated less favourably than another person in a similar situation because of their age. According to the Australian Human Rights Commission (AHRC), examples of age discrimination include:
- Not considering an older applicant for a job because it’s assumed they aren’t as up to date with technology as a younger person
- Not offering training opportunities at work to an older employee as it’s assumed they will retire soon
- Requiring an older person to meet a physical fitness test for a job where their physical fitness has nothing to do with their ability to perform the essential duties of the job
- Targeting older employees for redundancies.
Research commissioned by Australian Seniors in March 2026 found close to 2 in 5 (39%) Australians over 50 say they have definitely (16%) or possibly (24%) experienced age discrimination at work. That is down from 60% when the same survey asked the question in 2021, but few see it as progress. Only 19% believe ageism in the workforce has improved over the past five years, 39% say it hasn’t changed and 29% think it has worsened.
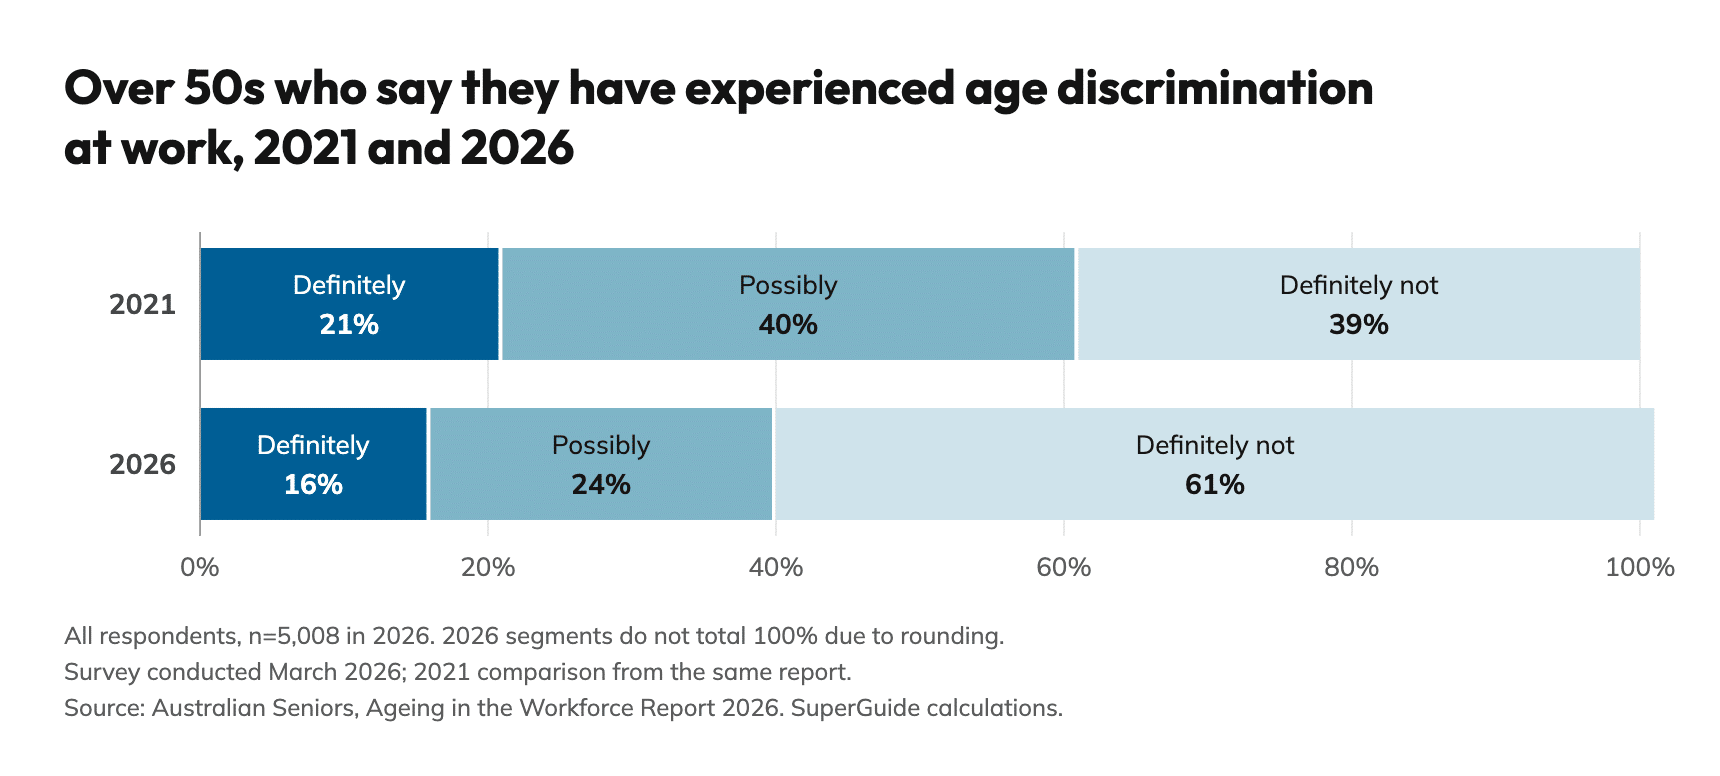
Among workers who had encountered age discrimination in the past 12 months, half (50%) reported assumptions about their capability, energy or adaptability, a third (33%) experienced negative workplace culture such as comments, jokes or exclusion, and 3 in 10 reported fewer promotion opportunities (30%) or being excluded from consideration for new internal roles (30%). Only 30% of workers over 50 feel very or extremely comfortable raising concerns about ageism in their workplace.
Source: Australian Seniors, Ageing in the Workforce Report 2026
Too old to work: Who is an older worker?
These findings about ageism tally with other research. The 2025 Australian HR Institute (AHRI) and AHRC survey of HR professionals, Older and Younger Workers: What Do Employers Think?, found 18% of employers were not open to hiring people aged 65 and over ‘at all’.
Only 28% of HR respondents were open to hiring people aged 65 and over ‘to a large extent’, and 56% to hiring people in the 50–64 years age group, compared with 80% for those aged 25–34. Just 57% had recruited anyone aged 55 and over in the previous 12 months, down from 68% in 2023.
The perception of what constitutes an ‘older’ worker has been shifting to younger ages. Nearly a quarter (24%) of HR professionals in the 2025 survey classed workers aged 51–55 as older, more than double the 10% who said so in 2023 and up from 17% in 2021. Where 61–65 was once the most commonly chosen range, responses in 2025 were spread almost evenly across 51–55 (24%), 56–60 (23%) and 61–65 (25%).
Job seekers tell the same story. In the Australian Seniors survey, more than half (51%) of over 50s who had applied for a role in the past five years felt they had or possibly had been treated unfairly because of their age, and 47% believed they had been turned down for a job after 40 for that reason. The most common experiences were not being shortlisted despite meeting the requirements (53%) and assumptions about being overqualified or too expensive (39%) or slower to learn technology (39%). Nearly 9 in 10 (86%) agreed that the older you get, the harder it is to find a job, and 29% had decided not to apply for a role at all because they thought their age would count against them.
Despite the survey findings, older workers continue to face discrimination and often feel discouraged when it comes to seeking employment. Australian Bureau of Statistics (ABS) data from February 2026 found that among people aged 55 and over who wanted to work and were available but were not actively looking, 14% said employers considered them too old, and for 10% it was the main reason they had stopped looking.
At the same time, most Aussies still want to be working in their 60s. According to the latest Australian Bureau of Statistics (ABS) data on retirement intentions, the average age people plan to retire is 65.6 years old. The actual average retirement age of all retirees, however, is more than eight years earlier, at 57.3 years.
What are my rights when it comes to age discrimination in employment?
In Australia, everyone has the right to continue working without being discriminated against because of their age.
In most cases it’s unlawful to treat a person unfairly because of their age but, in some circumstances, treating someone differently because of their age is not against the law. According to the AHRC these circumstances include things done:
- In compliance with Commonwealth, state and territory laws
- As part of certain health programs
- As part of ‘positive discrimination’, where a genuine benefit is provided to people of a particular age group, or something is done that helps to meet an identified need of people of a certain age group
- If the discrimination is reasonably based on statistical data or other relevant factors in relation to insurance and super.
Several government agencies may be able to help if you believe you have been unfairly discriminated against because of your age:
- Fair Work Commission – contact the FWC on 1300 799 675 if you believe you have suffered age discrimination.
- Fair Work Ombudsman – the ombudsman is able to hear complaints relating to discrimination in employment through the Fair Work Infoline on 131 394.
- Australian Human Rights Commission – you may be able to make a complaint about discrimination in employment by ringing the AHRC National Information Service on 1300 656 419.
Is age discrimination the end of the road?
Although 2024–25 ABS data on retirement intentions shows the average retirement age of all retirees is currently 57.3 years, many people remain in the workforce at older ages. The participation rate for Aussies aged 55 to 64 was 70.6% in June 2026, the largest annual rise of any age group.
It’s worth remembering entering retirement is not always the end of your career, with some people finding they return to employment after retiring.
According to 2024–25 ABS data, around 138,500 Australians aged 45 and over had returned to work after retiring, and the main reasons were boredom and financial necessity. Nearly a third (32%) came out of retirement because they were bored or needed something to do, 28% cited financial need and 13% said an interesting opportunity came up. A further 8% were asked back by a former employer and 6% returned because their health had improved.
More recent research points the same way. The Australian Seniors survey found more than 1 in 3 (35%) over 50s who were retired, semi-retired or looking for work had returned to the workforce, changed career or tried to since turning 50, with the rising cost of living (55%), wanting to stay active (46%) and rebuilding savings or super (44%) the main motivations. It isn’t easy. Only 1 in 5 (20%) of those actively looking for work were confident of finding a suitable role within six months, and half said repeated rejections or subtle exclusion had eroded their professional confidence.
So, just because you are forced into retirement due to age discrimination, it’s important to remember it may not be a one-way trip.
What it means for your super
When you experience discrimination based on your age at work, it can have a significant impact on your retirement savings. If you’re unable to find or remain in paid employment until a time of your choosing, you’re less likely to accrue sufficient savings to be fully self-funded in your retirement years.
The worry is widespread. In the Australian Seniors survey, close to 3 in 5 (59%) over 50s were concerned their super or savings would not be enough to fund the retirement they want, and 43% of those still working expected to retire later than planned because of cost-of-living pressures.
Additionally, you may find yourself caught in the difficult position of having no income but being too young to qualify for any financial support from the Age Pension.
Eligibility rules for both unemployment and disability benefits are increasingly strict, so you may need to exhaust all your financial resources to support yourself before you qualify for government financial assistance.
If you’re eligible to access your super, you may find yourself being forced to use your retirement savings for everyday expenses until you reach Age Pension age and qualify for Age Pension support.
5 tips to help protect your retirement finances
1. Start saving for your nest egg early
A key message from studies into employment-related age discrimination is it’s not a great idea to assume you will have 40 or 50 years of paid employment to save for your retirement. Many people leave saving for their retirement until the decade or so before they plan to retire, but if you’re forced out of the workforce earlier than you expect, you may not get that opportunity.
Starting to add a bit extra to your super as early as possible in your working life is sensible and it also means you will enjoy the benefits of compound interest, giving your nest egg a real boost. You also get to do so in the tax-efficient environment surrounding the super system.
2. Keep contributing after you’re retired
Although you may find yourself forced out of the workforce by age discrimination, that does not mean you’re totally excluded from the super system.
Even if you don’t have an employer making regular super guarantee (SG) contributions on your behalf, there are other super contributions you are able to make when you’re not working but under age 75. These include non-concessional (after-tax) contributions and downsizer contributions (from age 55) from the sale of your home.
3. Forget about the work test
Fortunately there is one thing you don’t need to worry about anymore when it comes to age discrimination, and that’s the dreaded work test for eligibility to make super contributions in your 60s and 70s.
From 1 July 2022, you no longer need to meet the requirements of the work test (being ‘gainfully’ employed for 40 hours or more in any 30-day period in a financial year) if you’re aged between 67 and 74 to qualify to make non-concessional (after-tax) contributions, or have salary-sacrifice contributions made on your behalf.
This means in most cases you are free to continue making super contributions to top up your super account until you turn 75 if you meet all the other eligibility criteria for that type of contribution.
The one situation where the work test is still applied is if you’re aged between 67 and 74 and wish to make a personal contribution for which you intend to claim a tax deduction.
4. Take advantage of the Age Pension Work Bonus
Although employer attitudes can make it tough to stay in the workforce, if you do remain employed the government is willing to help out a bit through its Age Pension Work Bonus.
The Work Bonus reduces the amount of employment income or eligible self-employment income applied to your rate of Age Pension entitlement under the income test. If you’re of Age Pension age and receiving a form of pension other than the single Parenting Payment and have income from employment or self-employment, you may be eligible for the Work Bonus. Services Australia automatically applies the Work Bonus to your income when you meet the eligibility requirements.
5. Apply for some of your super benefit
Even if you haven’t reached your preservation age and don’t qualify for one of the normal conditions of release for your super benefit, you can apply for access to some of your super savings.
There are some special, very restrictive conditions of release that may allow you to receive some of your super benefit if you are unable to find paid employment. These conditions include severe financial hardship, compassionate grounds, a terminal medical condition, temporary incapacity and permanent incapacity.

Leave a Reply
You must be logged in to post a comment.