


In this guide
When you’re aged 60 or more, you have the option to open an income stream (pension) with your super that provides you with regular periodic payments.
There are many types of retirement income streams but the most common is a simple account-based pension.
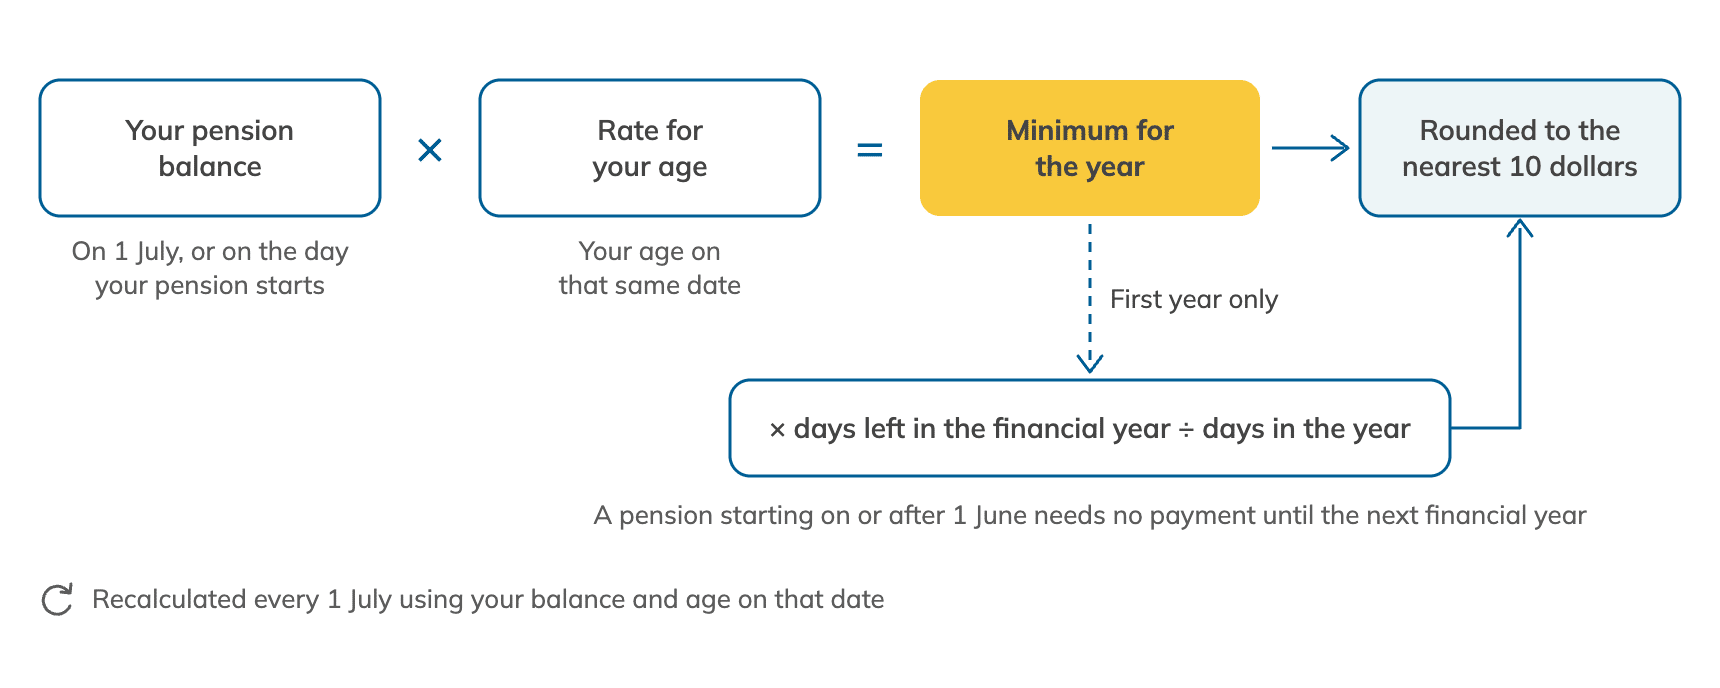
When you have an account-based pension, you are required to withdraw at least the minimum annual pension amount. The minimum is initially calculated on the start date of the pension using the opening balance and your age at the time. It is then recalculated on 1 July each year.
In the financial year you open your pension, the minimum payment is pro-rated to reflect the number of days remaining in that year.
How your minimum pension payment is worked out
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7
Retirement phase account-based pensions have no maximum annual withdrawal.
If you’re under 65 and have not left a job after your 60th birthday or retired permanently, you can open a transition to retirement (TTR) pension. The minimum annual withdrawal for a TTR pension is the same as for a retirement phase pension but an annual maximum of 10% also applies. When you turn 65 or retire, your transition to retirement pension converts into a retirement phase pension with no maximum withdrawal.
Minimum pension payment rates
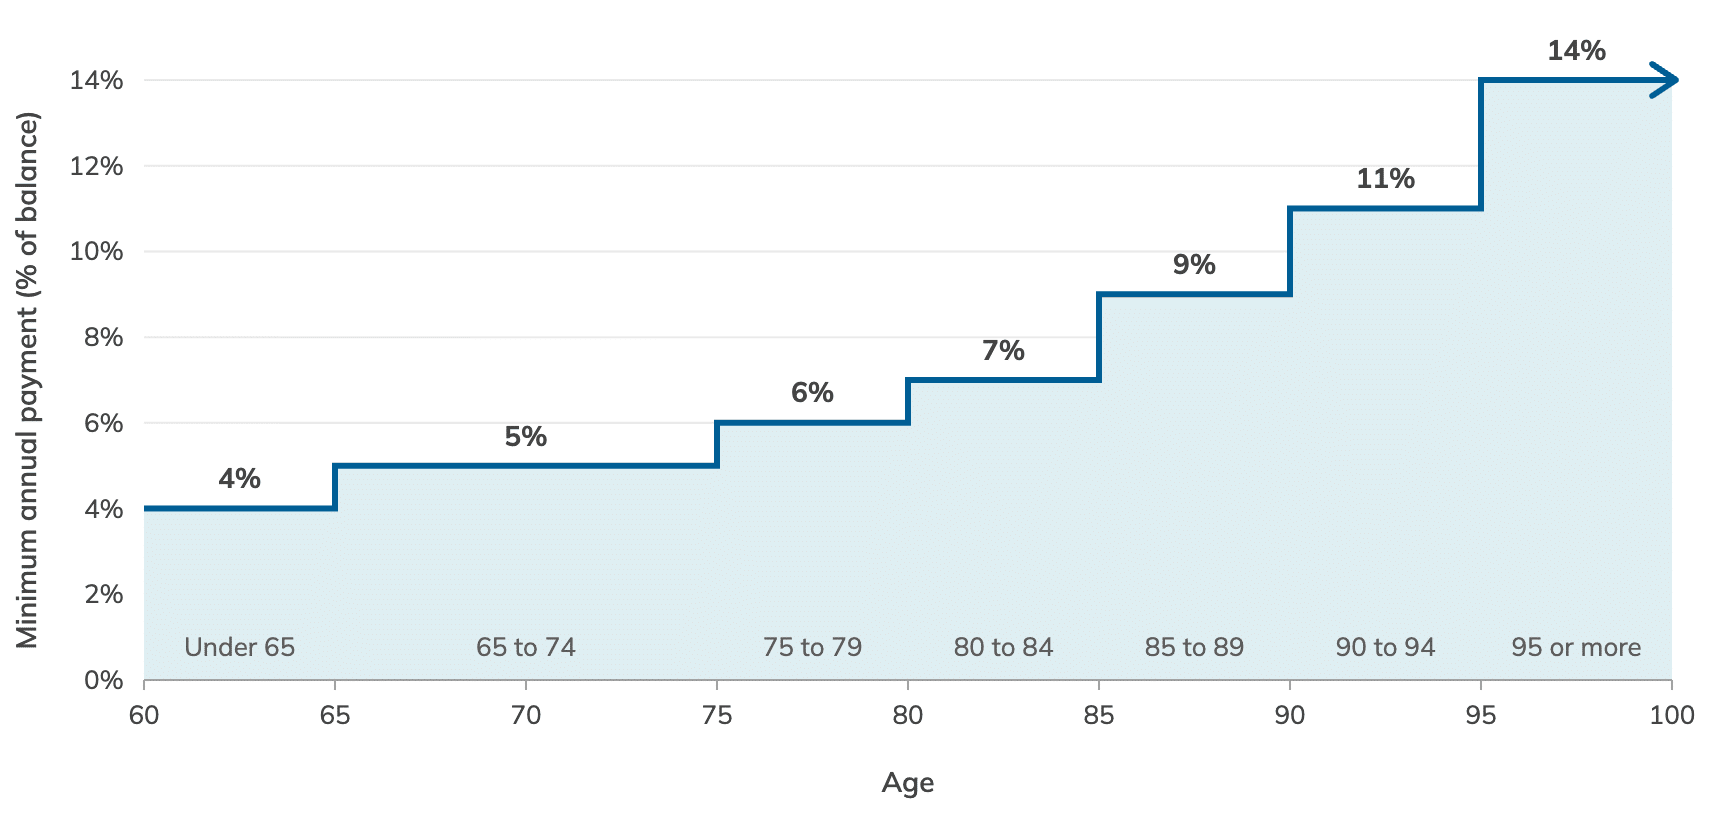
To calculate the annual minimum pension amount, your pension balance is multiplied by a percentage factor that increases as you age. The chart and table below show the minimum pension percentage factor for each age group.
Minimum annual pension payment by age
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7
| Age of beneficiary | Percentage factor |
|---|---|
| Under 65 | 4% |
| 65 to 74 | 5% |
| 75 to 79 | 6% |
| 80 to 84 | 7% |
| 85 to 89 | 9% |
| 90 to 94 | 11% |
| 95 or more | 14% |
Source: SIS Act
Payments must be received at least annually between 1 July and 30 June each financial year, although many retirees opt to receive fortnightly, monthly, or quarterly payments. Annual minimum payment amounts are rounded to the nearest ten whole dollars. If the amount ends in an exact five dollars, it is rounded up to the next whole ten dollars.
Calculating the first payment
If you start a simple account-based pension after 1 July, the minimum amount for the first year is calculated on a pro-rata basis according to the number of days remaining in the financial year, including the start day (see example below).
If your super pension commences on or after 1 June, no payment is required in that financial year.
First-year minimum pension payment by start date
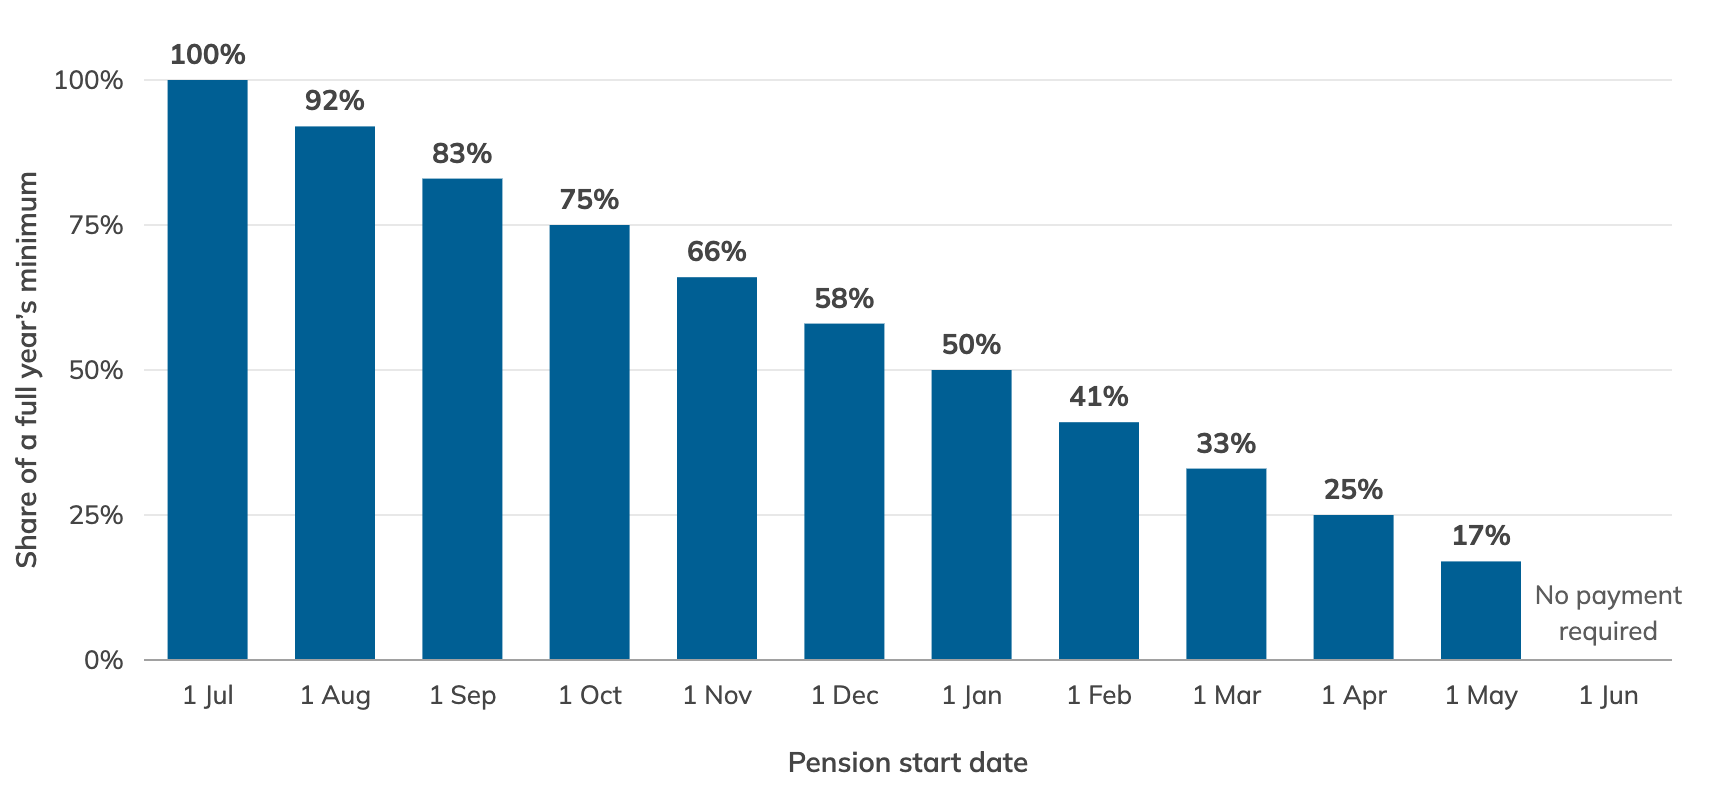
Shown as a share of a full year’s minimum. Based on a 365-day financial year, counting the start date.
Source: Superannuation Industry (Supervision) Regulations 1994, Schedule 7. SuperGuide calculations
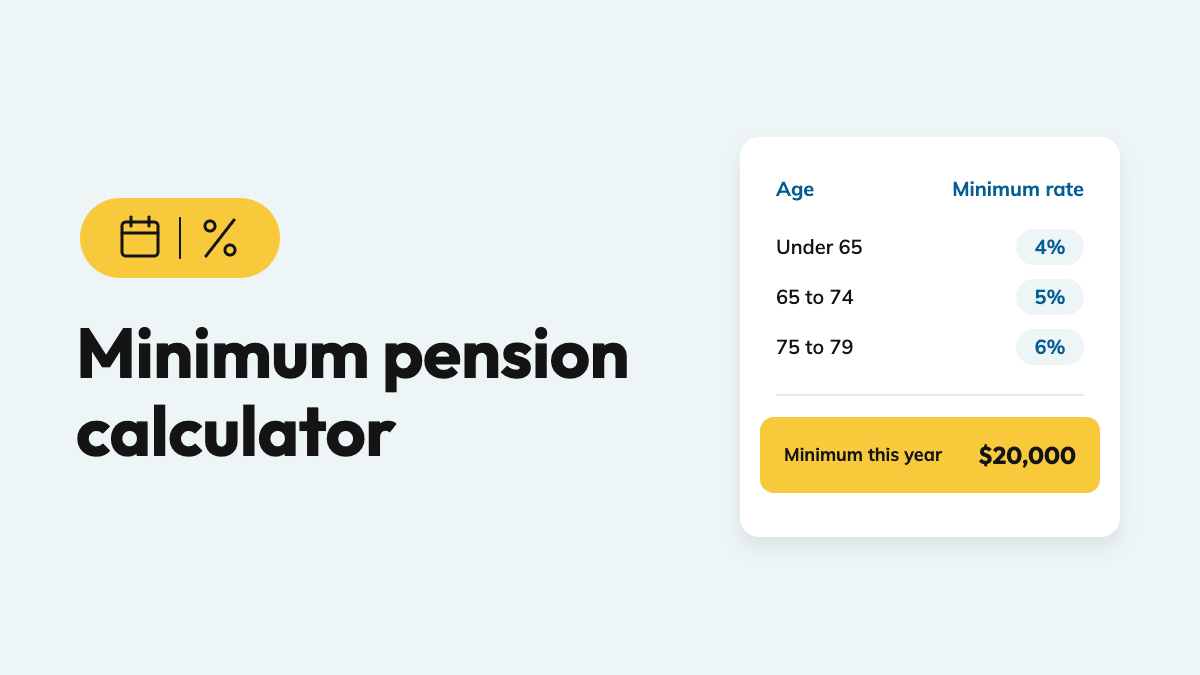
Minimum pension drawdown calculator
Work out your minimum pension payment for a full year, or for the first year of a new pension. Available to SuperGuide members.
Common questions about the minimum pension drawdown rules
Q: What’s the difference between an account-based pension and a non-account-based pension?
A: Currently, most super pensions are account-based, so called because the pension is paid from a super account held in your name. An account-based pension stops when the balance runs out.
Some account-based products are available that guarantee to pay income for life by imposing restrictions on your withdrawals and adding insurance (at additional cost).
For SMSFs with account-based pensions, the amount supporting the pension must be allocated to a separate account for each member.
Defined benefit pensions, as well as some lifetime pensions offered by super funds and annuities paid by life insurance companies, are non-account-based pensions.
In a non-account-based pension, assets are pooled among all members and the provider pays you a regular income over a fixed period or for life. Unlike account-based pensions, these income streams do not have an identifiable account balance in the member’s name.
All pensions except deferred annuities must make payments at least annually.
Q: I understand I need to draw down 5% of my super at some point, but when does that start? I’m 66 and retired.
A: The requirement to make withdrawals is triggered when you start a pension (income stream) with your super balance.
Any money kept in the accumulation phase of super can stay there indefinitely with no requirement to make minimum withdrawals. Once you have met a condition of release, such as turning 65, you can also withdraw lump sums from your accumulation account without starting a pension.
The pension (retirement) phase is attractive because investment earnings are tax free. Many people choose to start pensions even if they don’t need the minimum withdrawals for spending.
The 5% minimum you have mentioned applies to people aged 65 to 74 who have a simple account-based pension.
Different withdrawal rates and payment settings apply to other types of pensions. A deferred annuity even allows you to purchase an income stream that will not start making payments until you reach a set age.
Q: Why does the government set a minimum pension payment?
A: The minimum percentage factor for simple account-based pensions is set to satisfy the sole purpose test. That is, that super (and the generous tax concessions it receives) is designed to provide retirement income. It’s not intended to be used as a tax-effective way to transfer wealth to the next generation.
The minimum ensures a reasonable amount of income is withdrawn each year, and in exchange the account-holder is granted tax-free investment earnings on the assets supporting the pension.
The requirement to make withdrawals does not exist in accumulation accounts, where investment earnings remain taxable.
There is no maximum annual drawdown other than the balance of your account, unless it is a transition-to-retirement (TTR) pension that is not in retirement phase, in which case the maximum is 10% of your pension account balance.
Q: What happens if I don’t meet the minimum pension requirement? Can I fix it at the start of the next financial year?
A: If your super is with a large fund, your minimum payments will be adjusted automatically each year and your fund will make sure you withdraw at least the minimum.
If you have an SMSF, you need to be vigilant and arrange for the minimum pension payment to be made each year or risk losing the tax-free status of your pension.
If your SMSF fails to make the required minimum payments by the end of a financial year:
- The pension will be deemed to have ended for tax purposes at the start of the financial year, which means the SMSF will no longer receive a tax exemption on the pension earnings or capital gains in that year.
- Any payments made during the year will be treated as super lump sums for both tax and super purposes, and not pension payments; and
- The SMSF trustees must report the cessation of the pension to the ATO using a transfer balance account report.
To start receiving pension payments again, you would need to take steps to start a new pension.
There can be instances where the ATO Commissioner may allow the super fund to continue an income stream, but it depends on various conditions being satisfied.
Q: How does the minimum work if I have more than one account-based pension?
A: When you have more than one account-based pension, the minimum withdrawal for each account is calculated separately based on the balance of that account and your age. You must withdraw at least the required minimum from every account-based pension you hold.
Q: If I’m 74 on 1 July and turn 75 before the end of the financial year, does the rate for 65 to 74 still apply for that year?
A: No, minimum pension payments do not change during the financial year.
When your pension has continued from a previous year, your age on 1 July determines the minimum pension requirement you need to meet in that financial year.
In the year a pension starts, your age on the day you started your pension is used to calculate your minimum.
Q: I moved part of my super into a pension and left the rest in accumulation, which still receives contributions. Is the minimum worked out on my pension balance only, and does that balance change each year?
A: The minimum is calculated using the balance of your pension account only. Money you have in an accumulation account is not counted and has no minimum withdrawal.
The minimum is recalculated each 1 July using your pension account balance on that date.
If you have more than one pension account, a separate minimum applies to each.
Pension accounts can’t accept contributions, but there are options to use your additional contributions to start a second pension or ‘refresh’ your existing pension by combining its balance with new contributions to start a new pension with a larger amount.
Q: If my minimum pension is $15,000 and I take it in three payments of $5,000, but take $7,000 on the last withdrawal, is the extra $2,000 a lump sum or part of my minimum?
A: You may withdraw additional income above the minimum from an account-based pension. This additional income does not need to be treated as a lump sum unless you wish to do so. If you do want to treat the payment as a lump sum, you must ensure the right paperwork is submitted to your fund to request payment as a lump sum.
Any additional income withdrawn above the minimum is not ‘part of your minimum’ because it is over and above the minimum, but it can still be an income payment.
The minimum simply means you must withdraw at least that amount as income during the year. You may withdraw any higher amount of income you wish. For example, if your minimum is $15,000, you could withdraw $100,000 of income payments for the year because this is above the minimum requirement.
Remember that transition to retirement pensions have maximum withdrawal rules that must also be complied with.
Q: I receive my minimum pension payment fortnightly but don’t need the money. Can I have it paid as a single payment at the end of the financial year instead?
A: Yes, you can take your payment annually. Many funds let you choose fortnightly, monthly, quarterly, half-yearly or annual payments, and some allow you to set the payment date.
Taking one payment late in the year keeps the money invested in the tax-free retirement phase for longer. The trade-off is that the full amount must be paid before 30 June, whatever markets have done in the meantime.
If you have an SMSF, you set your chosen payment date and frequency in line with any rules in your fund’s trust deed.
Q: If I start a retirement phase pension on 1 July with a minimum of $50,000 for the year, then move it back to accumulation in December, do I need to draw the full $50,000 or only half?
A: If you transfer an account-based pension back to accumulation part way through the financial year, only a proportional amount of the year’s minimum payment needs to be made.
In the example of a $50,000 annual minimum payment and a transfer back to accumulation after half a financial year, the approximate payment required would be $25,000.
If you close the pension, the pro-rata minimum needs to be paid before it is commuted (cashed or rolled over to accumulation), even if this takes place only a day or two into the financial year. If you commute only part of the pension, the full minimum for the year still applies, and enough must remain in the pension to pay it.
If the required minimum is not paid, the pension standards have not been complied with and the earnings on the funds supporting the pension before the commutation cannot be treated as tax-free pension income.
The Superannuation Industry (Supervision) Regulations govern how super funds operate, and the regulation that confirms this proportioning rule is here, should you be interested.
Q: I’m in pension phase and have to withdraw 4% before the end of the financial year. What are my options with the share market so volatile?
A: The minimum has to be paid by 30 June whatever markets are doing, so the practical question is which investments the money comes from.
Many large funds let you choose which investment options your pension payments are drawn from, such as a cash option, so you aren’t forced to sell growth investments after a fall. Some retirees hold a year or two of payments in cash for this reason, often called a cash buffer or bucket strategy.
In an SMSF, minimum pension payments must be made in cash. Transferring shares or other assets to yourself (an in-specie payment) does not count towards the minimum, so the fund needs enough cash available before 30 June.
The government has reduced the minimum rates during severe market disruption in the past, such as the halving from 2019–20 to 2022–23, but no reduction applies now and none is automatic.
Q: My 4% withdrawal from my new pension is about $50,000 a year, but I don’t need that income as I have gone back to work. What is the best way to invest it? I have already used up my three-year bring-forward.
A: You have indicated that you have already maximised your non-concessional contributions but you may be eligible to make additional concessional contributions to super. Remember that both your employer’s contributions and your personal concessional contributions are counted towards your cap.
If you have reached both contribution caps or you would prefer not to make further super contributions, you can choose to invest excess withdrawals anywhere you choose outside the super system.
We are not licensed to provide personal advice and therefore can’t recommend how or where you should invest.
An alternative is to reduce or eliminate the minimum you are required to withdraw by moving some or all of your pension back into an accumulation account.
If you roll over part of your pension back into an accumulation account, your minimum withdrawal for the following financial year will be based on a lower balance.
If you stop the pension entirely, and move the whole balance into accumulation, you will no longer be required to make withdrawals at all. You may also choose to start a new pension with a lower balance and lower minimum withdrawal.
If you close the pension, the pro-rated minimum for the year must be paid first. If you take a lump sum or roll part of the pension back to accumulation, the full minimum for the year still applies, and enough must remain in the pension to pay it.
It is important to consider that if your current pension is in retirement phase the investment earnings are tax-free. Accumulation accounts and transition to retirement pensions are taxed on investment earnings at the rate of 15%.
Care is required when consolidating pension and accumulation accounts because the tax components of the accounts will mix, which can have estate planning consequences.
Personalised financial advice is recommended before any action.
Q: Does the amount I withdraw from my super pension affect my Age Pension?
A: The amount of Age Pension you receive is determined by the income test and assets test.
Whether the withdrawals you make from your super pension affect your Age Pension entitlements depends on the type of product you have and how long you’ve held it.
Simple account-based pensions
The income test is not usually affected directly by the amount you withdraw, because Centrelink applies the deeming rules to assess the income from these products based on your balance. The actual income you withdraw is not assessable.
The exception to this rule is if you have continuously held your pension and received Age Pension or another Centrelink income support payment since 1 January 2015. In this case, Centrelink uses the actual income you withdraw less a deductible amount in the income test, so the level of income you choose to withdraw can affect your Age Pension.
The assets test includes the balance of your pension. Withdrawing more (and spending it) reduces the value of your balance, and therefore your assets, and could increase your Age Pension if you are most affected by the assets test.
Similarly, a lower pension balance will lead to smaller deemed income and could increase your Age Pension if you are most affected by the income test.
Other super pensions
Other pension products are assessed differently in Centrelink’s means tests.
For example, lifetime products purchased from 1 January 2019 have 60% of their purchase price counted in the assets test until a threshold day, then 30% of the purchase price is assessed. In the income test, 60% of the income paid is assessed. Changing the amount withdrawn from one of these products can affect the Age Pension because the income assessed in the income test would also change.
The bottom line
Under the super rules, people with account-based super pensions are required to withdraw a minimum amount each financial year. The minimum amount is expressed as a percentage of your pension account balance, beginning at 4% when you’re aged under 65 and gradually increasing to a rate of 14% from age 95.
Failure to withdraw the minimum amount could result in your super pension losing its tax-free status.
There is no maximum withdrawal amount unless you are under 65 and using a transition to retirement pension. If you are unsure about how much you could safely withdraw each year without running the risk of your savings not lasting the distance, we recommend you seek independent financial advice.


Leave a Reply
You must be logged in to post a comment.