


In this guide
Gifting some of your assets or savings to assist family, friends or worthy causes can be an excellent way to aid younger members of your social circle or society at large. However, planning is key to make sure you understand the financial consequences.
For example, giving away assets or selling them for less than they’re worth reduces the money you will have for retirement. Centrelink’s gifting rules also mean your Age Pension may not increase as much as you expect, and it could even be cut.
What is gifting?
For Centrelink purposes, gifting refers to selling or transferring savings or an asset for less than its value or without receiving anything in return. If you receive adequate compensation, it is not considered a gift.
Gifting limits
While you can give away as much as you like, there are limits within which a gift can immediately lower the amount you have being assessed in Centrelink’s means tests.
The limits are $10,000 per financial year and $30,000 over five financial years. They apply together, and Centrelink calls this the ‘gifting-free area’. Anything you give away above either limit is a ‘deprived asset’.
The limits are the same whether you’re single or part of a couple. For a couple, they apply to the total you both give away, not to each of you.
In the example below, the $5,000 gift in year 4 is under the yearly limit but is still a deprived asset, because $30,000 has already been given in the previous three years.
How the gifting limits work
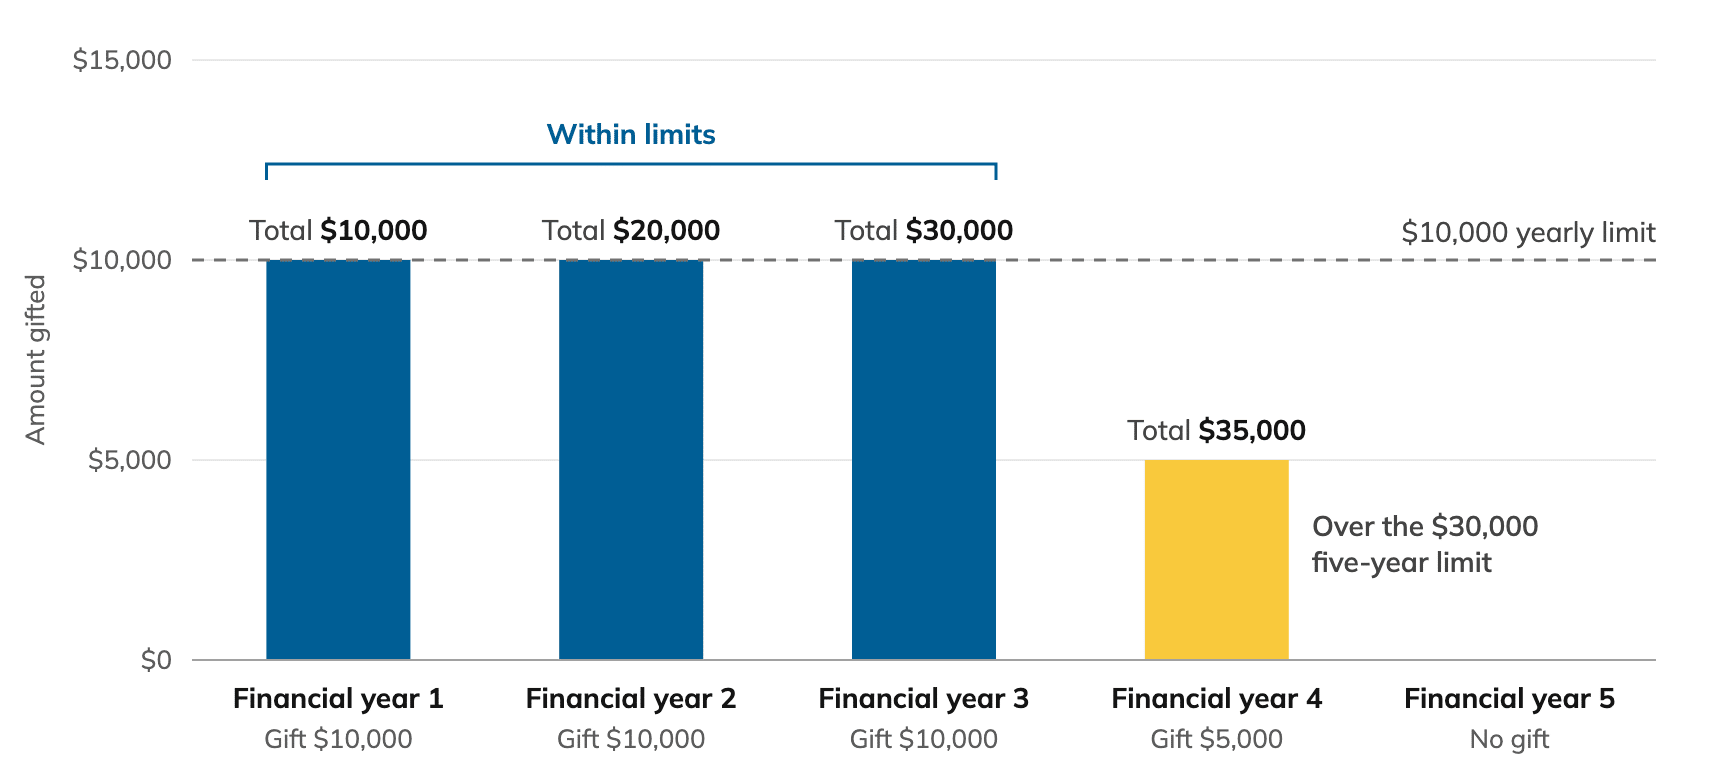
Illustrative gifts.
Source: Services Australia
Deprived assets are counted in the assets test and generate deemed income under the income test for five years from the date of the excess gift. The rate of Age Pension you get is the amount calculated by the assets test or the income test, whichever is lower.
This arrangement is designed to limit the potential for someone to reduce their assets for the purpose of increasing their Age Pension.
If you gift something above the limits that was already being assessed, your payment rate will not go down, but it also won’t increase significantly until the deprived asset stops being counted when the five-year period ends.
If you gift an asset that was not included in the means tests, such as your home, your payment may reduce immediately because you will have a deprived asset counted that was not assessed before. An alternative to simply giving away all or part of your home is to create a ‘granny flat interest’ by exchanging the value you’re giving away for the right to continue to live in the property for life. Granny flat interests are assessed differently by Centrelink.
Gifting $300,000: savings compared with your home
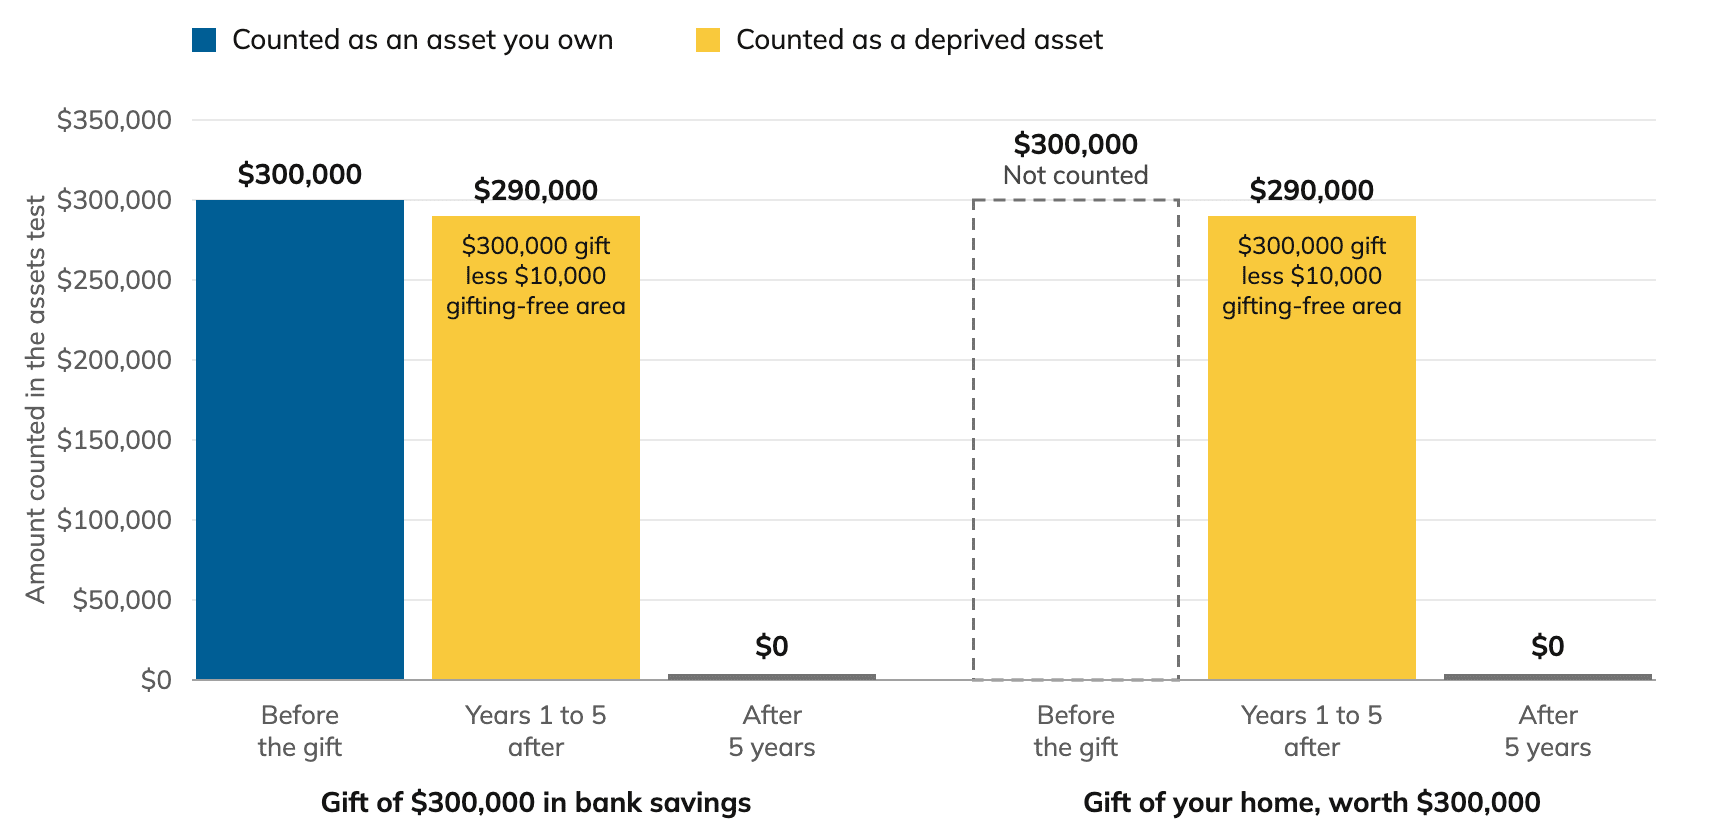
Illustrative example assuming no earlier gifts. Giving away your home can also change your homeowner status, which changes the assets test thresholds.
Source: Services Australia. SuperGuide calculations
When applying for payments from Centrelink or the Department of Veterans’ Affairs (DVA), you must disclose gifts made in the last five years. Once you’re receiving a payment, you must tell Centrelink or the DVA about any significant change to your circumstances (including giving a gift) within 14 days.
What counts as gifting?
As mentioned earlier, for social security purposes, gifting is not simply about giving away your money or savings. Examples include:
- Transferring the ownership of investments for less than their market value (the difference between the market value and the payment you receive is a gift)
- Giving up control of a company or a family trust that holds assets inside it
- Forgiving a loan someone owes you, in part or in full
- Paying your grandchildren’s school fees.
What does not count as gifting?
In addition to the transfer of assets where you receive fair market value, other transactions that don’t count as gifting include:
- Selling assets or spending savings to cover regular living expenses, such as home improvements or a holiday
- Transfers between spouses, such as contributions to your partner’s super account
- Gifts made to the Special Disability Trust of an immediate family member (within limits)
- Assets given or construction costs paid for a ‘granny flat’ interest*
*If the amount paid for a granny flat interest is more than the cost of purchasing the property or paying for required renovations to accommodate your residency, Centrelink will apply a reasonableness test to determine if you have deprived assets.
Is it a gift, and is it assessed?
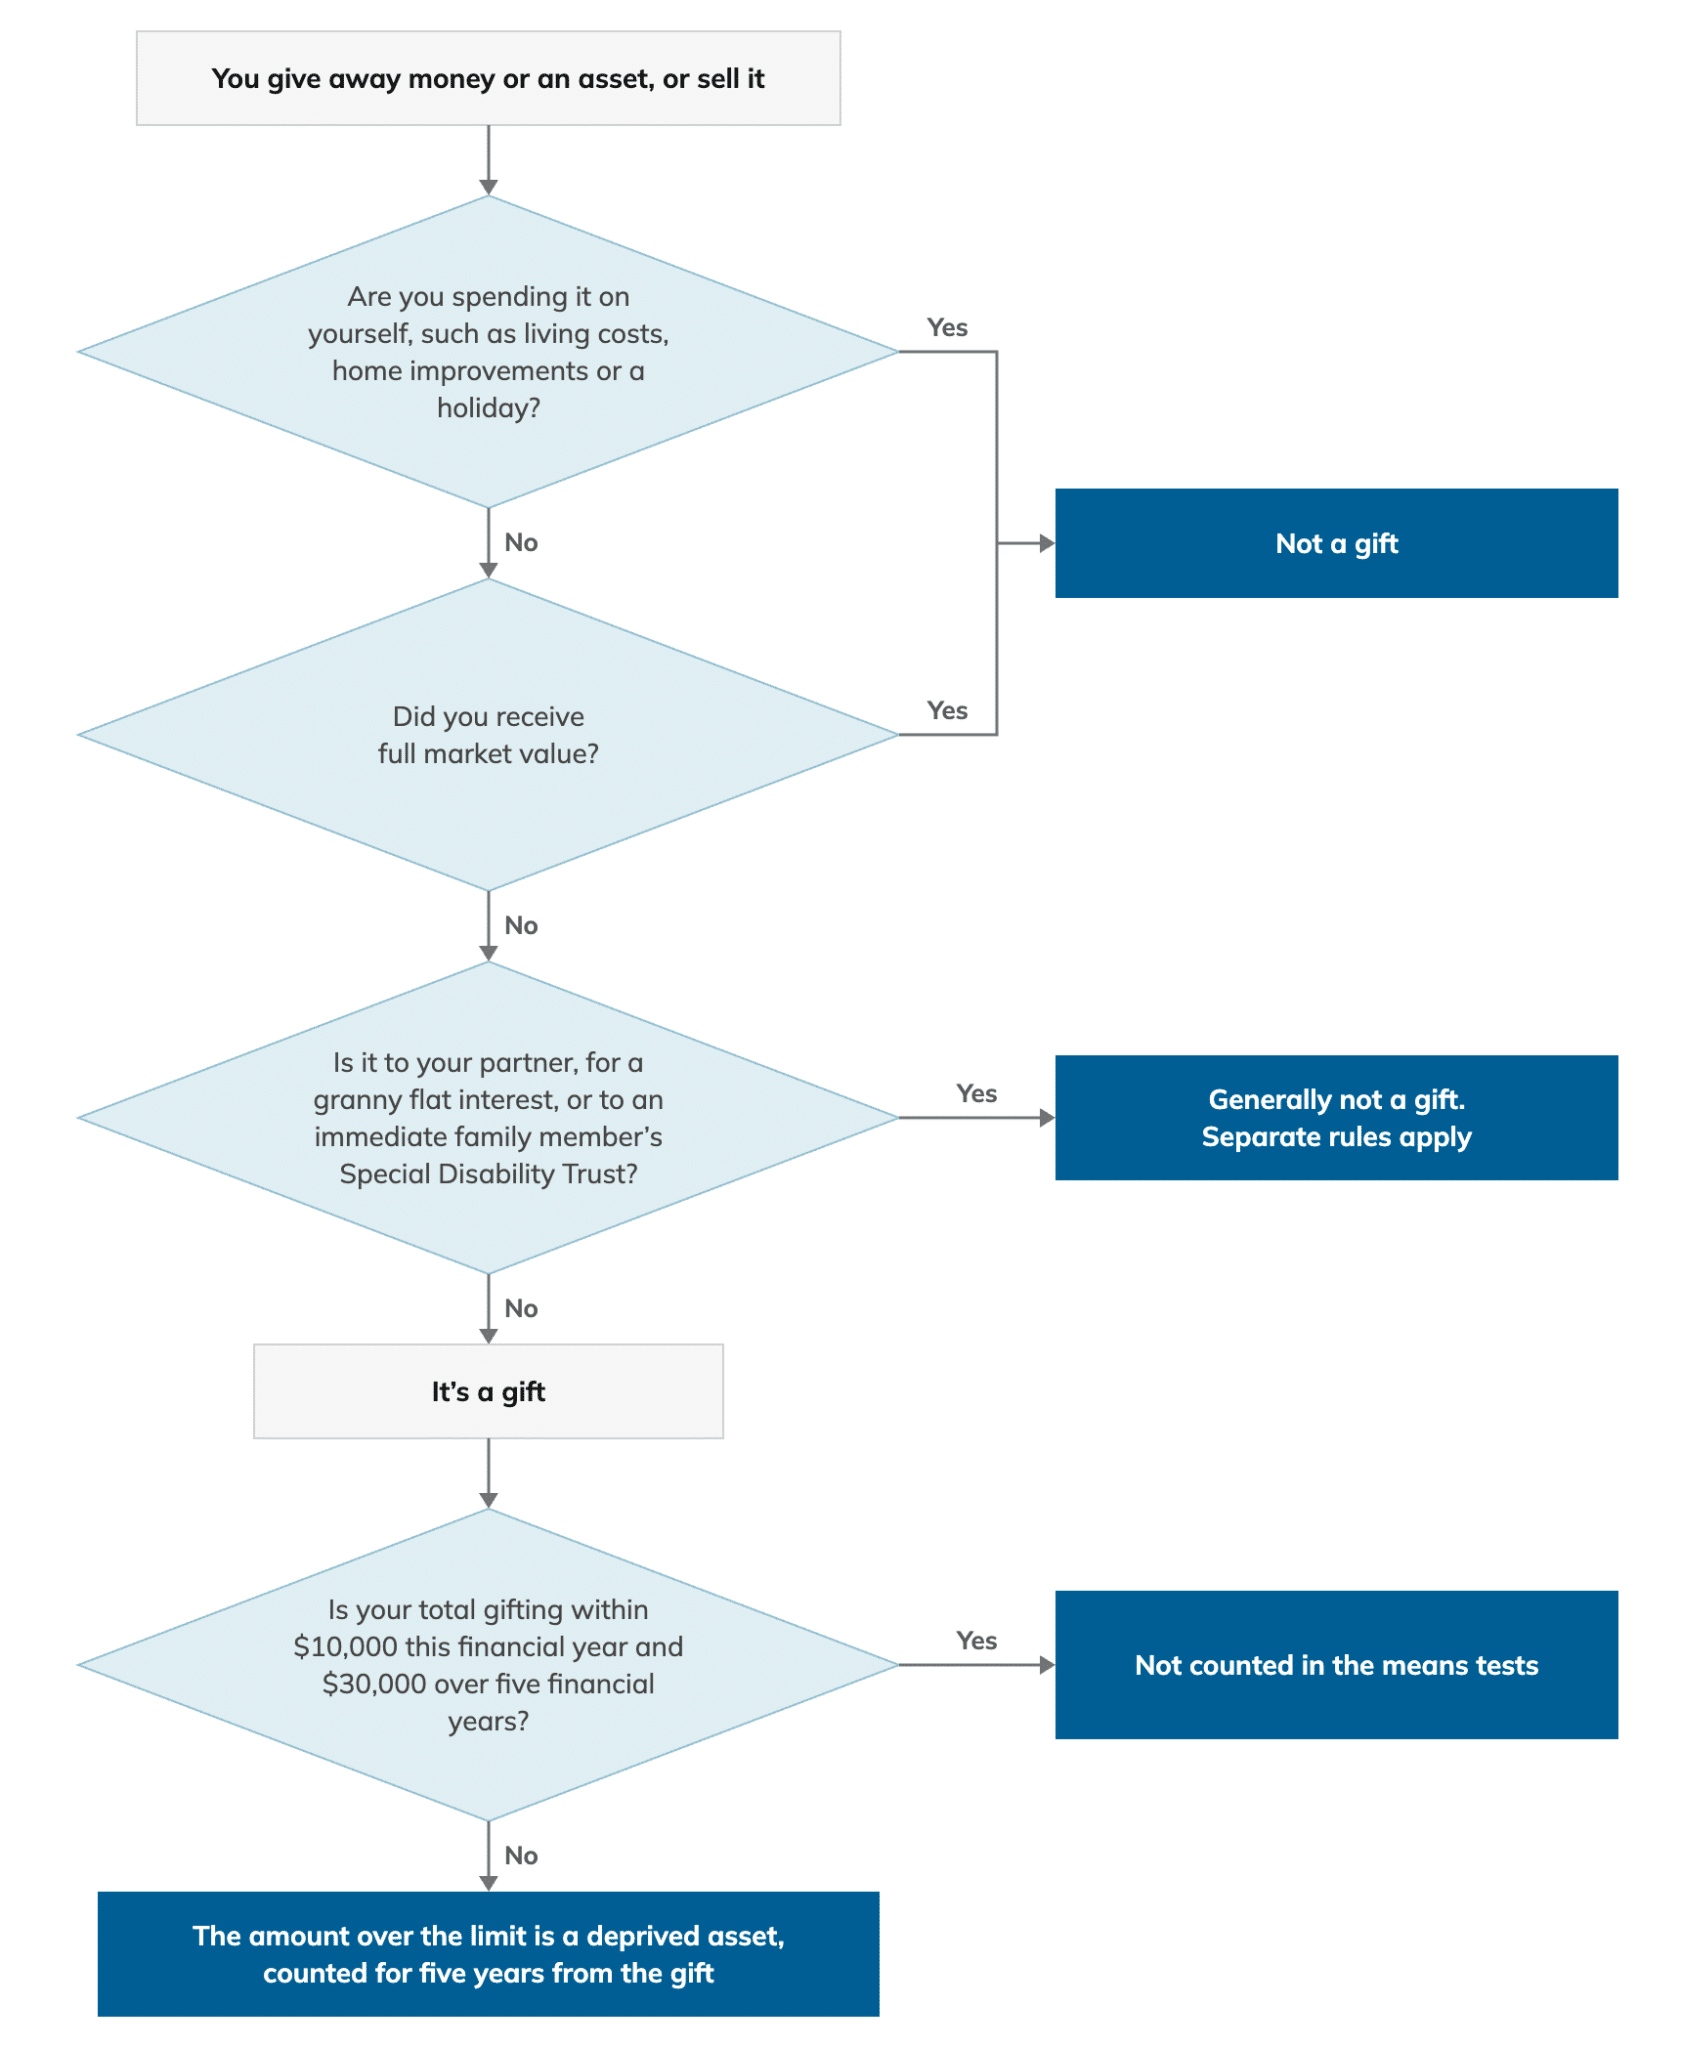
Granny flat interests and Special Disability Trusts have their own limits and conditions, so part of the amount can still be treated as a gift.
Source: Services Australia
Timing of the gift
An important thing to consider with gifting is timing. Centrelink only looks back at the last five years. If you gift away your holiday house at the age of 61, then when you turn 67 and claim the pension, that gift will not be assessed.
When deciding whether you have given away amounts above the limit, the rules are not simple because there are adjustments in place to avoid double counting where gifts are above both the $10,000 per financial year and $30,000 over five financial years thresholds.
Before making a gift, it is important to confirm whether any gifts have already been made in the current financial year or the previous four financial years.
Example 1: Regular gifts
Adam gives $1,000 per month to his son to help with his mortgage payments between 1 January and 31 December 2026. Adam has gifted $6,000 in the 2025–26 financial year and $6,000 in 2026–27.
This does not exceed the $10,000 limit in one financial year rule, so none of the gifts will be treated as a deprived asset. Adam’s assessable assets are reduced by $12,000.
Adam’s gifts across two financial years
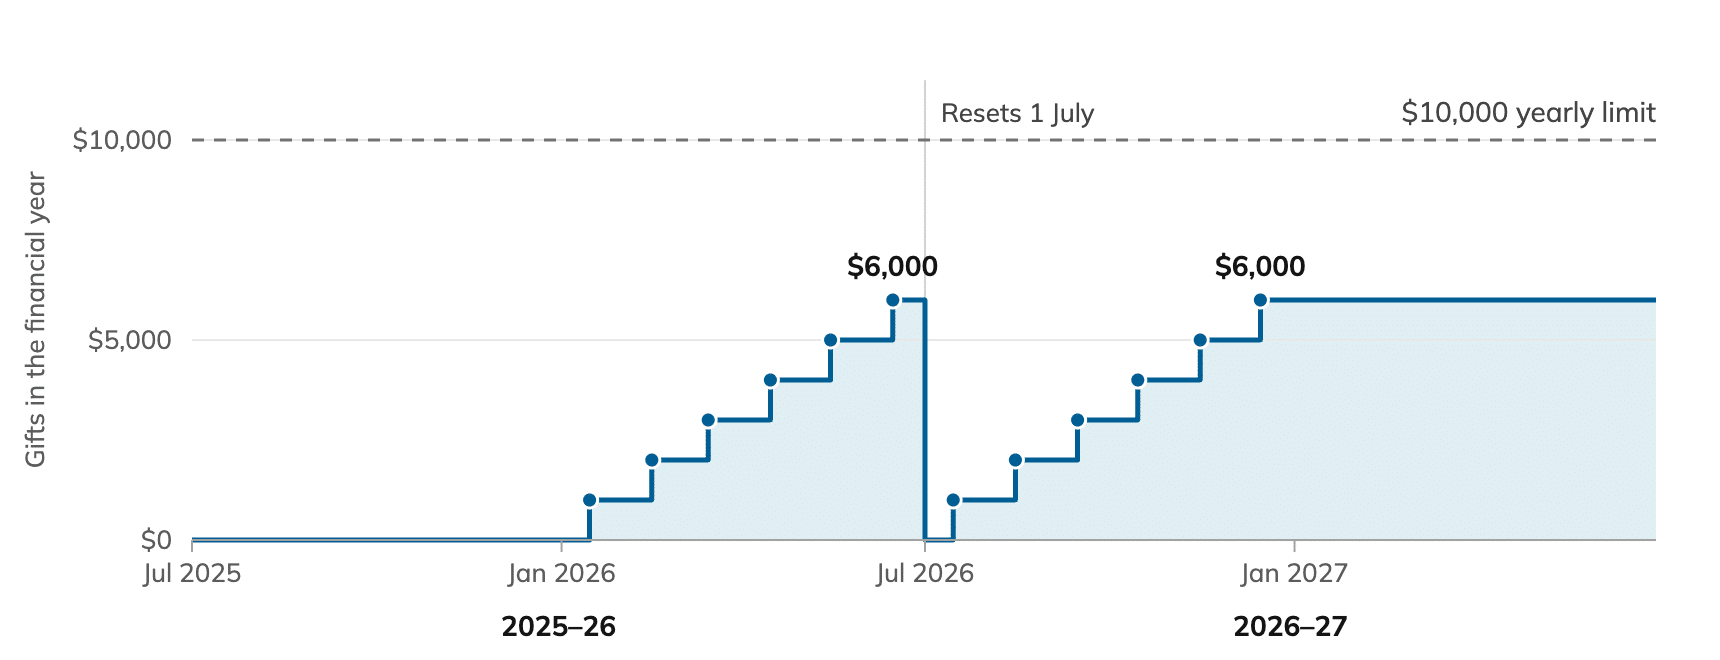
Assumes each $1,000 gift is made mid-month. The $10,000 yearly limit applies to each financial year (1 July to 30 June), so the running total resets on 1 July. Adam gives $12,000 in calendar year 2026 but no more than $6,000 in either financial year.
Source: Services Australia. SuperGuide calculations
Example 3: Continued gifting
The $30,000 over five years rule can get more complicated because information about the last five years of gifting needs to be considered.
Consider the example of Joanne, who makes several gifts over a period of many years.
On 15 December 2022, Joanne gave away $20,000. The first $10,000 is not assessed because it’s in the gifting-free area. The other $10,000 is assessed as a deprived asset for five years from the date of the gift.
Then, on 10 September 2023, Joanne gave another $20,000. The first $10,000 is not assessed – it goes towards the gifting-free area. The other $10,000 is assessed as a deprived asset for five years. At this point, there is $20,000 in the gifting-free area, and $20,000 is being assessed as deprived.
On 15 July 2024, Joanne gave away a further $50,000. The first $10,000 is not assessed but forms part of the gifting-free area. The additional $40,000 is assessed as a deprived asset for five years. After making this gift, there was $30,000 in the gifting-free area and $60,000 being assessed as a deprived asset.
Joanne gives $10,000 more on 5 July 2025. The entire amount is assessed as a deprived asset because she has already reached $30,000 of unassessed gifting in the previous five-year period. She now has $70,000 being assessed as a deprived asset.
Assume she makes no gift in financial year 2026–27.
On 1 July 2027, due to the rolling five-year rule, the first year of the gifting-free area has dropped off, meaning there is now $20,000 there. Joanne could give away another $10,000 in 2027–28 and it would not be assessed, but would send the gifting-free area back to $30,000.
However, the original excess gift that was assessed ($10,000 on 15 December 2022) will not be removed until five years have passed since it was given – on 15 December 2027. At that time, the total amount assessed as a deprived asset will reduce to $60,000.
How Joanne’s gifts are counted
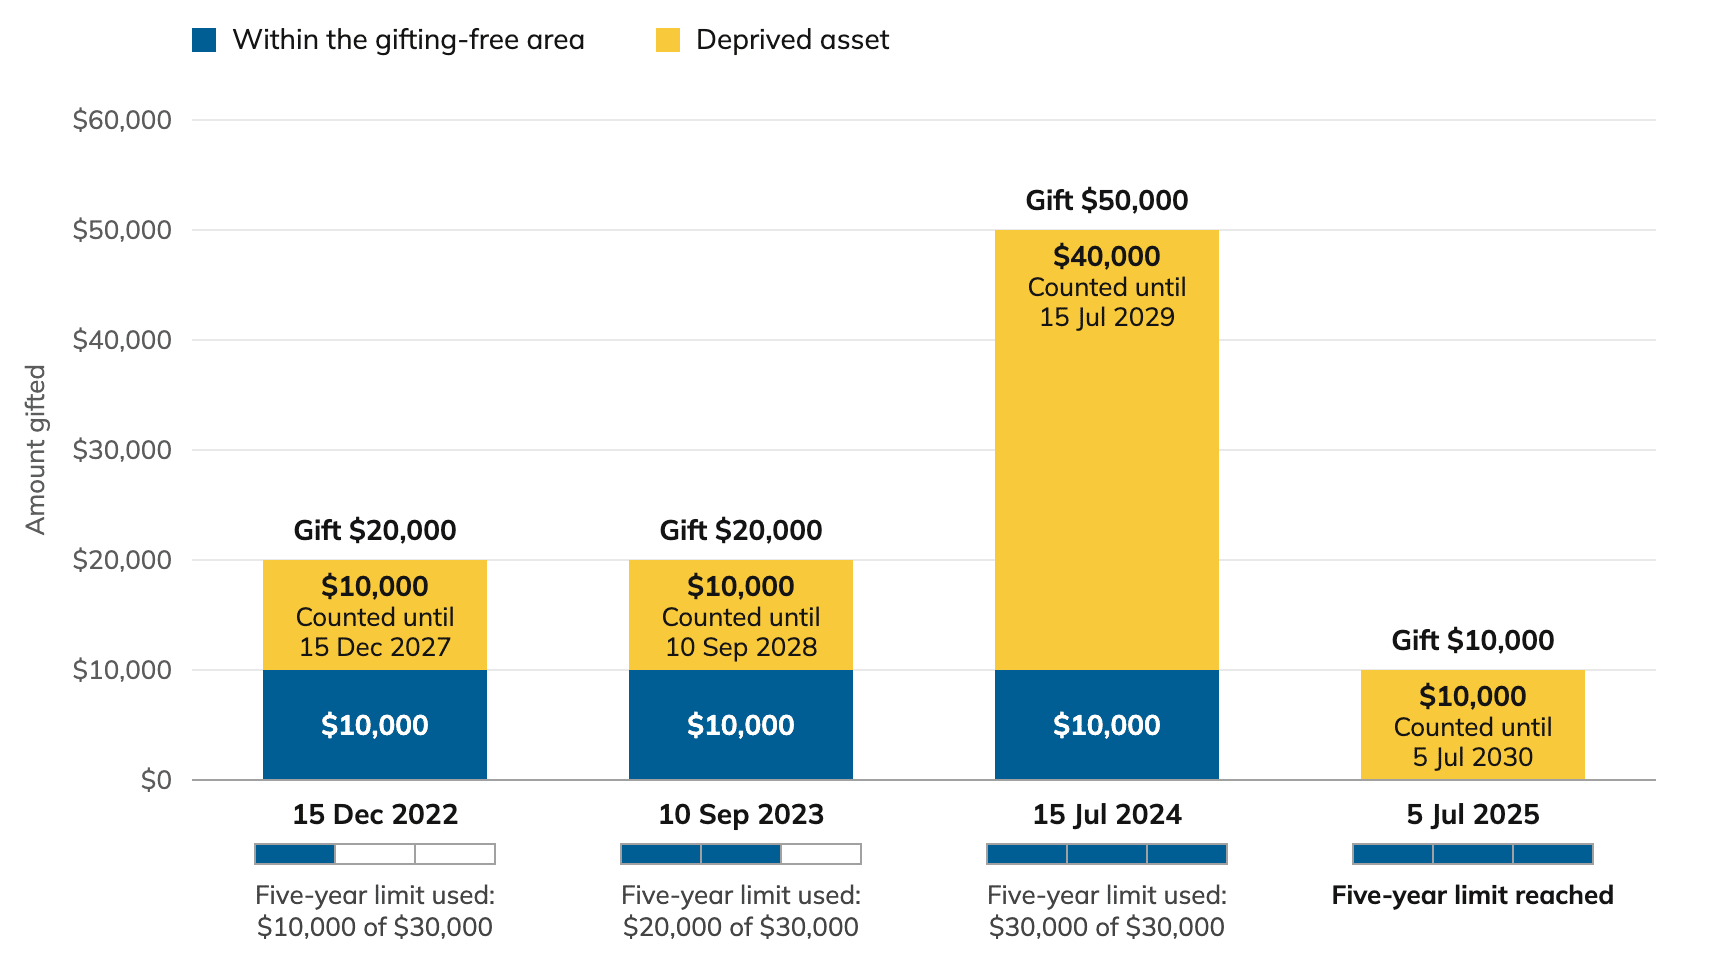
Amounts in the gifting-free area are not counted. Each deprived amount is counted for five years from the date of its gift. By the third gift, Joanne has used her $30,000 five-year limit, so all of her fourth gift is a deprived asset.
Source: Services Australia. SuperGuide calculations
The impact of gifting in practice
So far, we have discussed how and when gifts are assessed by Centrelink. To take things a step further, we need to explore how gifting can impact your overall financial position.
Importantly, giving something away or selling it for less than it is worth means you have less available to support yourself in retirement. You may regret your decision if money is tight later or an expense such as necessary home renovations or a deposit to enter aged care comes up.
Giving away investments for the sole purpose of improving your Age Pension doesn’t make sense if you could generate more income by keeping your savings. Each $10,000 given away increases your Age Pension by a maximum of $780 a year (your personal increase could be lower).
Disposing of assets can also come with other costs like stamp duty, brokerage fees, and tax on capital gains. Giving away an asset is treated the same way as if you sold it at its market value when tax and stamp duty are calculated.
The impact on your Age Pension will vary depending on your personal circumstances. The following case studies demonstrate some possibilities, using the Age Pension rates and thresholds that apply in October 2026.
The gifting rules and granny flat arrangements are complex and consulting a qualified financial adviser or Centrelink directly before acting is recommended.
Common questions about gifting
Q: Centrelink’s website says deprived income is where you “refuse an increase in your income”. When does this apply?
A: In terms of income, deprivation generally refers to where you keep an asset but give away the income it produces. An example could be where you have an investment property and give the rental income to someone else. Other examples include refusing or forfeiting the right to a super pension, or giving it to a third party.
Q: My understanding is that if I lend money to my sibling and expect it to be repaid over time, this is not gifting and I would still be able to receive the Age Pension. Is that right?
A: A loan is not a gift if it is properly documented and is to be repaid.
However, lending money to someone will not reduce your assets for Centrelink means tests, so it cannot increase your Age Pension entitlement. The full amount of the loan is a financial asset, which is counted in the assets test and has income deemed in the income test. You can see that loans are treated as financial investments in Services Australia’s list of asset types.
Q: I understand that I can make a gift of $10,000 a year and therefore increase our Age Pension as a married couple. What do I need to do to prove to Centrelink that I have done this legally, for example a signed receipt or an agreement?
A: Centrelink assesses your money where it is. If you have given your son $10,000 from your bank account, you would provide your bank statement to Centrelink showing the money being transferred out of your account. It will record the resulting balance and a $10,000 gift. The lower bank balance is what increases your pension.
You can give up to $10,000 per financial year and $30,000 over five financial years before the excess amount is counted in the Age Pension means tests. These limits apply to you as a couple combined (you don’t get one each).
Centrelink may ask to see evidence of the money being transferred into your son’s account, but you don’t need a signed agreement.
Q: If we gift our property to our son and continue to live in it under a granny flat arrangement, how will this affect our Age Pension? We would also keep paying off the remaining mortgage on the property.
A: Transferring the title of your home to someone else in return for the right to live there for life can create what Services Australia calls a granny flat interest. When you transfer your whole home this way, the transfer is not treated as a gift, so the deprivation rules don’t apply and you are still treated as a homeowner for the assets test.
There are conditions. If you move out within five years of creating the granny flat interest, and the reason for leaving could have been anticipated when you set it up, the deprivation rules can apply. If you transfer money or other assets on top of the home, a separate reasonableness test applies, and any amount above the reasonableness test amount is treated as a gift.
Services Australia recommends having a legal agreement drawn up as proof of the arrangement. Because you will no longer own the home, the arrangement also affects your estate, aged care and what happens if family circumstances change, so it is worth getting legal advice before you proceed. Centrelink’s Financial Information Service can explain how a proposed arrangement would be assessed.
Q: Our daughter and her husband want to pay for most of a second storey on our house so we can all live together. We would still own the property. We are both over Age Pension age, and my wife intends to contribute $200,000 from her super accumulation account as a lump sum. Because our home is exempt from the assets test, would the $200,000 be treated as an improvement to our home rather than a gift?
A: Generally, your principal home, including any modifications and additions, is exempt from the assets test if it is fully owned by you and not by a third party.
Amounts in a super accumulation account held by a person aged 67 or over are assessable in the income and assets tests. Removing funds from that account and spending them on improvements to your own home would generally reduce the amount being assessed, and your Age Pension may increase as a result. Spending money on your own home is not gifting.
Alternatively, if the withdrawal is used to make a gift, any amount above the gifting-free area would remain assessable for five years before it is no longer counted in the means tests.
For the assets and income test treatment of a specific arrangement, particularly where family members are also contributing to the cost, it is best to speak with Centrelink directly.


Leave a Reply
You must be logged in to post a comment.