


In this guide
- Age Pension eligibility
- How deemed income is calculated
- What are the current deeming rates?
- Example deeming calculations
- How deeming affects means testing for residential aged care
- Deeming rates and thresholds: current and previous periods
- Why does the Australian government use deeming?
- Why does the deeming rate increase if you have more investment assets?
- January 2015 changes
- Common questions about deeming
In recent years, deeming rates shifted from being an arcane concept few people knew or cared about, to a hot button issue for retirees struggling to make ends meet at a time of rising interest rates and cost-of-living pressures.
The reason is this.
Under the deeming rules, you are ‘deemed’ to earn a certain annual rate of return on your financial assets, regardless of the rate of return you actually earn. Your returns could be higher or lower than the deeming rates. In the case of bank deposits, the returns you are earning may be lower than the current deeming rates while returns from superannuation have been higher. Why does this matter? Because it could affect the amount of Age Pension you receive and the amount you pay for residential aged care.
When deeming rates increase, a larger amount of deemed income is counted under the Age Pension income test. For part pensioners assessed under the income test, that can reduce the payment they receive. Full pensioners and people assessed under the assets test are not affected by the rate change.
Age Pension eligibility
Deeming is used to determine your eligibility for the Age Pension under the income test. The other requirements are passing the assets test, reaching Age Pension age and qualifying as an Australian resident.
Deeming rules are used by Services Australia (via Centrelink) for income test calculation purposes. Centrelink also applies the same deeming rates and thresholds when assessing eligibility for the Commonwealth Seniors Health Card (CSHC).
Common types of financial assets that deeming rates apply to include:
- Account-based super pensions
- Savings accounts and term deposits
- Shares
- Managed investment such as managed funds and insurance bonds
- Debentures
Deeming doesn’t apply to the family home and other property assets.
How much Age Pension could you receive?
Enter your income and assets to estimate your Age Pension entitlement.
How deemed income is calculated
The deemed income from your investments is calculated by multiplying their current value by the relevant deeming rates. Different deeming rates apply depending on:
- Your living arrangements (whether you live alone or with a partner)
- The value of your investment assets
- Whether or not you (or your partner) currently get the Age Pension.
Once your deemed income is calculated, the amount is then added to any other income you’ve earned from all other sources as part of the Age Pension income test. If your income exceeds the income test thresholds, your Age Pension entitlement will progressively reduce until it cuts off completely.
What are the current deeming rates?
The deeming rates and thresholds that apply from 20 September 2026 to 19 March 2027 are listed in the table below.
| Situation | Deeming lower rate | Deeming higher rate |
|---|---|---|
| Single | 1.75% on the first $66,800 of your investment assets, plus | 3.75% on your investment assets over the amount of $66,800 |
| Couple | 1.75% on the first $110,600 of your combined investment assets, plus | 3.75% on your combined investment assets over the amount of $110,600 |
Financial investments include:
- Bank, building society and credit union accounts
- Cash
- Term deposits
- Cheque accounts
- Friendly society bonds
- Managed investments
- Assets held in superannuation and rollover funds
- Listed shares and securities
- Shares in unlisted public companies
- Gold, silver or platinum bullion
- Loans and debentures by you (that is, money owed to you).
The following are not included
- Your home
- Home contents
- Cars, boats and caravans
- Investment properties
- Antiques, stamp or coin collections
It is worth noting that an investment property is not counted as a financial investment, so it is not assumed that it achieves an income at the deeming rate, but any income from investment properties is applied as income in the income test.
Deeming rates are set by the Minister for Social Services. The Department of Social Services monitors the rate to ensure that it’s appropriate for market conditions. Any future changes to the deeming rate will coincide with changes to Age Pension rates, which are regularly adjusted based on the consumer price index (CPI), or at any other time if the financial markets fluctuate significantly. The CPI is calculated by the Australian Bureau of Statistics. Any changes to the deeming thresholds are generally made in July each year in line with changes in the CPI.
Example deeming calculations
To illustrate how deeming works, below are tables that show the deeming amount that will apply at a range of different investment asset values for Singles and Couples based on current rates and thresholds (20 September 2026 to 19 March 2027).
Click each deeming table example name to view.
| Investment value | Deemed at 1.75% | Deemed at 3.75% | Deemed income total (per year) |
|---|---|---|---|
| $50,000 | $875.00 | $0 | $875 |
| $100,000 | $1,169.00 | $1,245 | $2,414 |
| $150,000 | $1,169.00 | $3,120 | $4,289 |
| $200,000 | $1,169.00 | $4,995 | $6,164 |
| $250,000 | $1,169.00 | $6,870 | $8,039 |
| $300,000 | $1,169.00 | $8,745 | $9,914 |
| $350,000 | $1,169.00 | $10,620 | $11,789 |
| $400,000 | $1,169.00 | $12,495 | $13,664 |
| $450,000 | $1,169.00 | $14,370 | $15,539 |
| $500,000 | $1,169.00 | $16,245 | $17,414 |
| $550,000 | $1,169.00 | $18,120 | $19,289 |
| $600,000 | $1,169.00 | $19,995 | $21,164 |
| $650,000 | $1,169.00 | $21,870 | $23,039 |
| $700,000 | $1,169.00 | $23,745 | $24,914 |
| $750,000 | $1,169.00 | $25,620 | $26,789 |
| $800,000 | $1,169.00 | $27,495 | $28,664 |
| $850,000 | $1,169.00 | $29,370 | $30,539 |
| $900,000 | $1,169.00 | $31,245 | $32,414 |
| $950,000 | $1,169.00 | $33,120 | $34,289 |
| Investment value | Deemed at 1.75% | Deemed at 3.75% | Deemed income total (per year) |
|---|---|---|---|
| $50,000 | $875.00 | $0 | $875 |
| $100,000 | $1,750.00 | $0 | $1,750 |
| $150,000 | $1,935.50 | $1,477.50 | $3,413 |
| $200,000 | $1,935.50 | $3,352.50 | $5,288 |
| $250,000 | $1,935.50 | $5,227.50 | $7,163 |
| $300,000 | $1,935.50 | $7,102.50 | $9,038 |
| $350,000 | $1,935.50 | $8,977.50 | $10,913 |
| $400,000 | $1,935.50 | $10,852.50 | $12,788 |
| $450,000 | $1,935.50 | $12,727.50 | $14,663 |
| $500,000 | $1,935.50 | $14,602.50 | $16,538 |
| $550,000 | $1,935.50 | $16,477.50 | $18,413 |
| $600,000 | $1,935.50 | $18,352.50 | $20,288 |
| $650,000 | $1,935.50 | $20,227.50 | $22,163 |
| $700,000 | $1,935.50 | $22,102.50 | $24,038 |
| $750,000 | $1,935.50 | $23,977.50 | $25,913 |
| $800,000 | $1,935.50 | $25,852.50 | $27,788 |
| $850,000 | $1,935.50 | $27,727.50 | $29,663 |
| $900,000 | $1,935.50 | $29,602.50 | $31,538 |
| $950,000 | $1,935.50 | $31,477.50 | $33,413 |
| $1,000,000 | $1,935.50 | $33,352.50 | $35,288 |
| $1,050,000 | $1,935.50 | $35,227.50 | $37,163 |
| $1,100,000 | $1,935.50 | $37,102.50 | $39,038 |
| $1,150,000 | $1,935.50 | $38,977.50 | $40,913 |
| $1,200,000 | $1,935.50 | $40,852.50 | $42,788 |
| $1,250,000 | $1,935.50 | $42,727.50 | $44,663 |
| $1,300,000 | $1,935.50 | $44,602.50 | $46,538 |
| $1,350,000 | $1,935.50 | $46,477.50 | $48,413 |
| $1,400,000 | $1,935.50 | $48,352.50 | $50,288 |
| $1,450,000 | $1,935.50 | $50,227.50 | $52,163 |
| $1,500,000 | $1,935.50 | $52,102.50 | $54,038 |
How much income will you be deemed to earn?
Enter the value of your financial investments to see your deemed income for the year and each fortnight.
Below we have also included some example calculations to help illustrate how deeming is calculated:
Example 1
Jane is single and has investment assets valued at $75,000. Her deemed income would be calculated as follows:
$66,800 x 1.75% = $1,169.00
+
$8,200 ($75,000 – $66,800) x 3.75% = $307.50
= $1,476.50 (per year)
= $56.79 (per fortnight)
How Jane’s deemed income is calculated
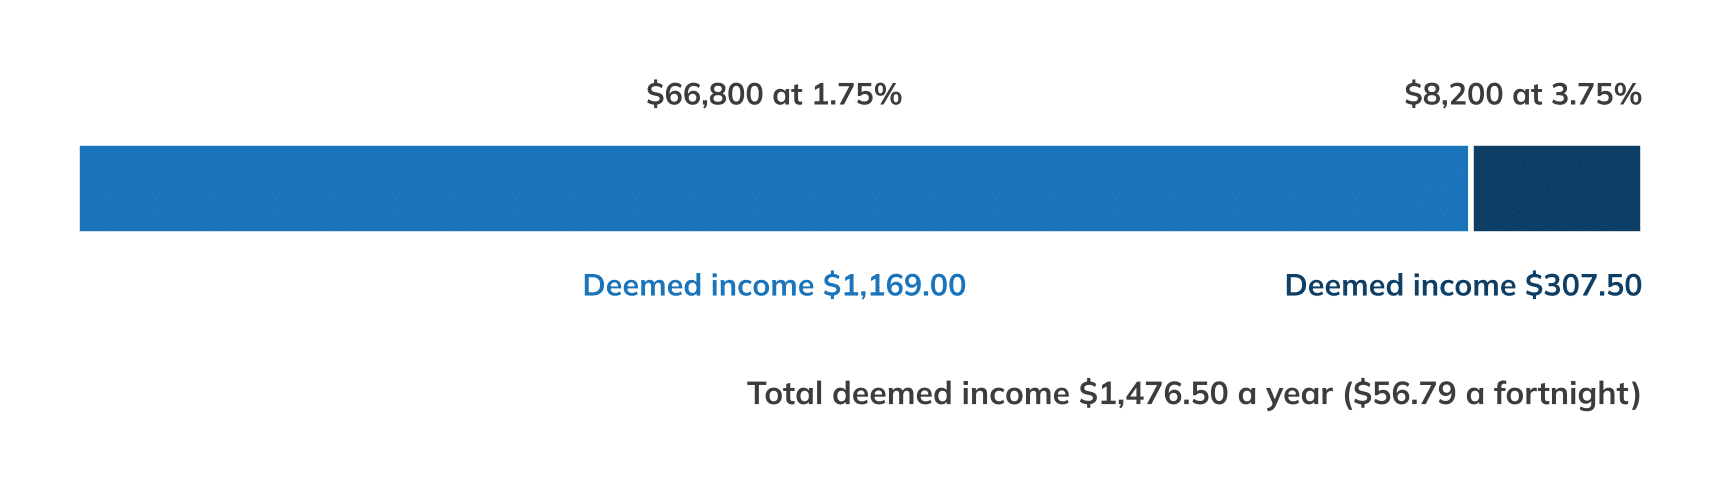
Annual amounts, using the deeming rates from 20 September 2026 and the single lower threshold from 1 July 2026. Source: Services Australia
Example 2
Ray and Sue are a married couple. Ray is currently receiving the Age Pension and Sue is not. They have combined investment assets of $150,000. Their combined deemed income for the purposes of Ray’s Age Pension income test would be calculated as follows:
$110,600 x 1.75% = $1,935.50
+
$39,400 ($150,000 – $110,600) x 3.75% = $1,477.50
= $3,413.00 (per year)
= $131.27 (per fortnight)
How Ray and Sue’s deemed income is calculated
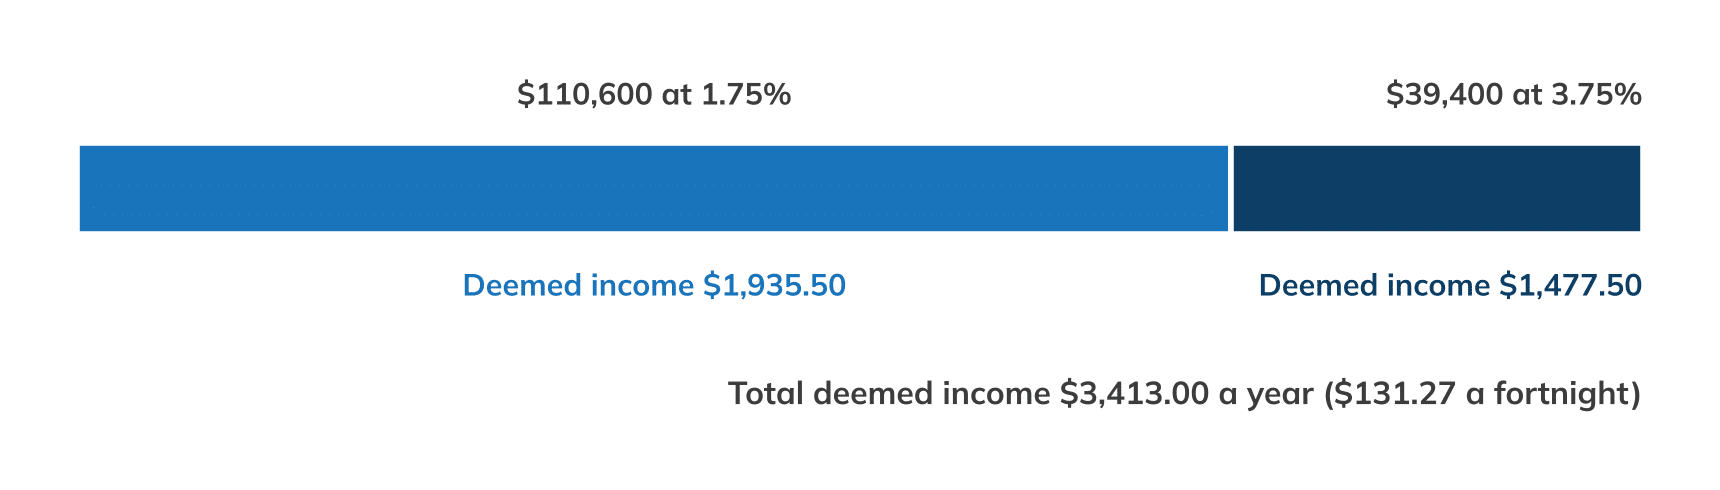
Annual amounts, using the deeming rates from 20 September 2026 and the couple lower threshold from 1 July 2026. Source: Services Australia
How deeming affects means testing for residential aged care
Deeming rates don’t just affect income-tested Age Pensioners. For anyone entering residential aged care, deeming is used to calculate any means-tested contribution they may be required to pay.
Visit the government’s myagedcare for an explanation of how deeming applies to aged care means testing.
Deeming rates and thresholds: current and previous periods
Deeming rates have moved five times since 2019, with a long freeze in the middle.
Before 1 July 2019, the rates were 1.75% (lower) and 3.25% (higher). Retirees were then earning less on their bank deposits than they were deemed to earn, and the resulting pressure led the federal government to cut the rates twice: to 1% and 3% from 1 July 2019, and to 0.25% and 2.25% from 1 May 2020.
Those rates were frozen at 0.25% and 2.25% for more than five years, from 1 May 2020 to 19 September 2025.
Since then the rates have stepped back up three times: to 0.75% and 2.75% from 20 September 2025, to 1.25% and 3.25% from 20 March 2026, and to 1.75% and 3.75% from 20 September 2026.
Deeming rates are meant to rise and fall in line with market interest rates, but in practice there is often a lag. In mid-2020 the higher deeming rate of 2.25% sat 2 percentage points above a cash rate of 0.25%, which is why the freeze drew so much criticism. Today the position is reversed. The Reserve Bank of Australia raised the cash rate to 4.60% on 30 September 2026, while the higher deeming rate is 3.75%, so the higher deeming rate remains below the cash rate.
Deeming rates and the RBA cash rate, 2019 to 2026
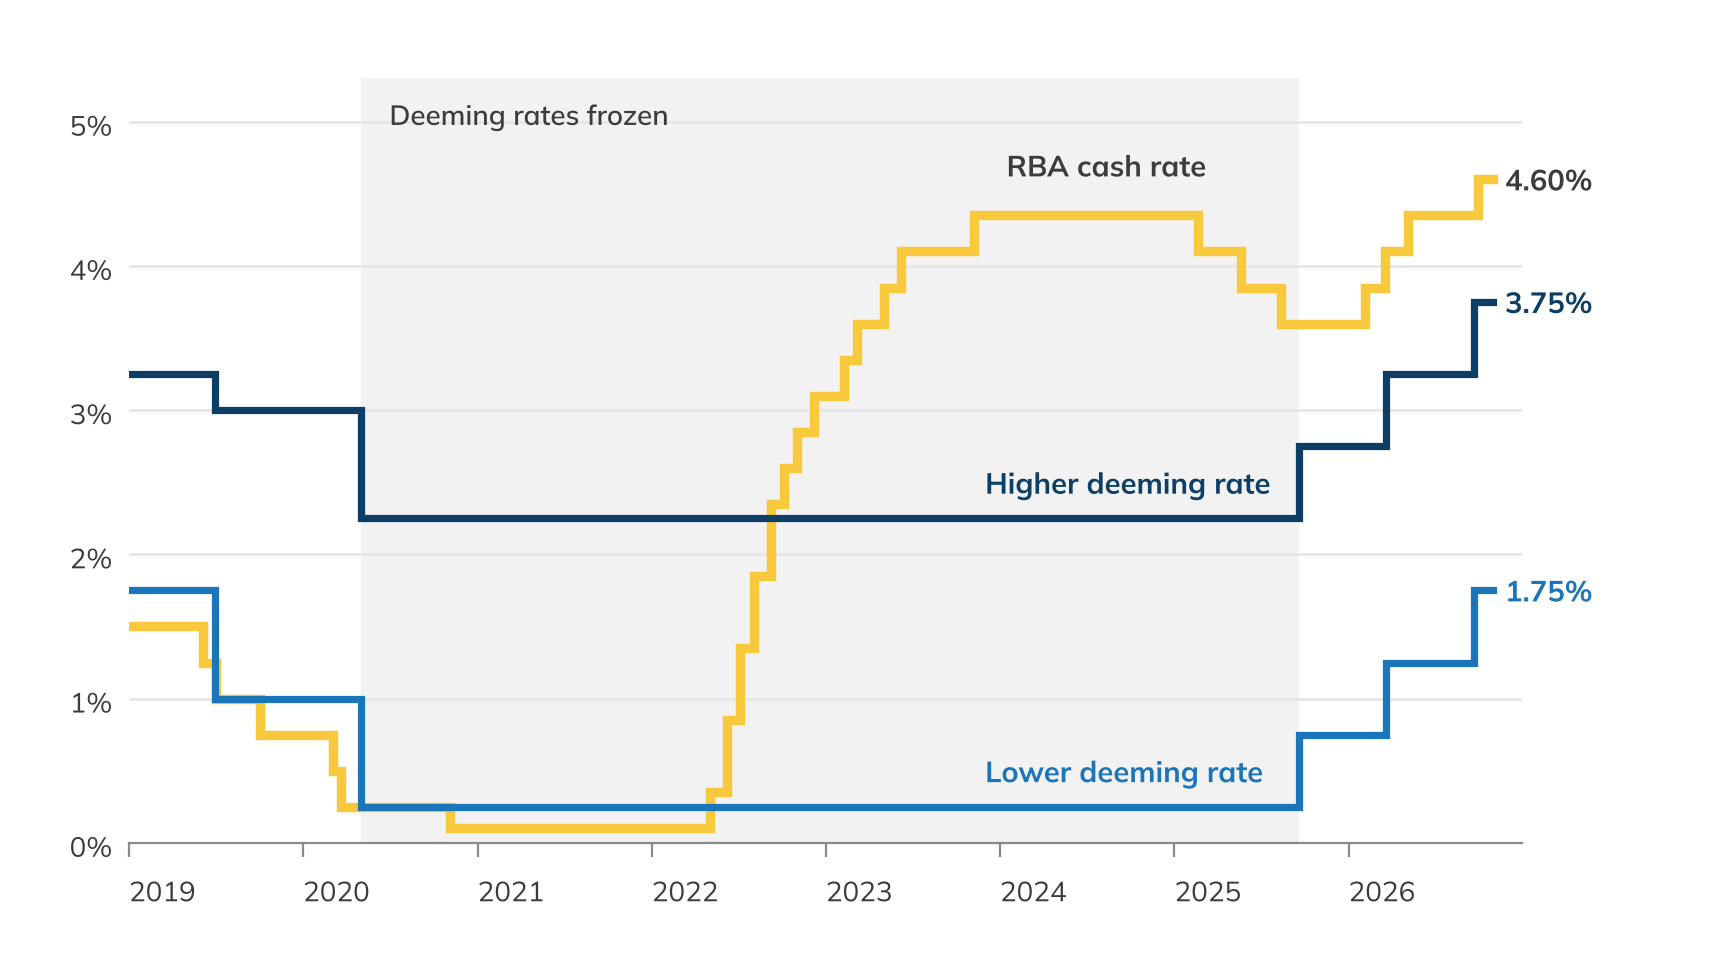
Deeming rates take effect on the dates shown and hold until the next change. Cash rate shown to the RBA decision of 30 September 2026. Source: Services Australia; Reserve Bank of Australia
Thresholds move separately from rates. They are generally indexed each July in line with the CPI, which is why they held at $64,200 and $106,200 through three different rate changes before rising on 1 July 2026.
The deeming rates and thresholds that have applied since 2020-21 are listed in the table below.
| Period | Deeming lower rate | Deeming higher rate | Single lower threshold | Couple lower threshold |
|---|---|---|---|---|
| 2026-27 (20 September 2026 to 19 March 2027) | 1.75% | 3.75% | $66,800 | $110,600 |
| 2026-27 (1 July 2026 to 19 September 2026) | 1.25% | 3.25% | $66,800 | $110,600 |
| 2025-26 (20 March 2026 to 30 June 2026) | 1.25% | 3.25% | $64,200 | $106,200 |
| 2025-26 (20 September 2025 to 19 March 2026) | 0.75% | 2.75% | $64,200 | $106,200 |
| 2025-26 (1 July 2025 to 19 September 2025) | 0.25% | 2.25% | $64,200 | $106,200 |
| 2024-25 | 0.25% | 2.25% | $62,600 | $103,800 |
| 2023-24 | 0.25% | 2.25% | $60,400 | $100,200 |
| 2022-23 | 0.25% | 2.25% | $56,400 | $93,600 |
| 2021-22 | 0.25% | 2.25% | $53,600 | $89,000 |
| 2020-21 | 0.25% | 2.25% | $53,000 | $88,000 |
Why does the Australian government use deeming?
According to the Department of Social Services, some of the benefits of deeming are:
It’s this last point that has many retirees hot under the collar. While returns from assets such as shares and property have indeed been higher than deeming rates in recent years, there is no guarantee this will continue. By their very nature, higher investment returns also come with a higher risk of price fluctuations and years of negative returns. That’s why many risk-averse retirees prefer the safety of capital guaranteed bank deposits to cover their income needs in the short to medium term.
Why does the deeming rate increase if you have more investment assets?
The lower deeming rate is applied to the value of your investment assets up to a threshold amount to reflect the fact that you’ll need a range of low-risk, accessible investments (like savings accounts) to meet your day-to-day living expenses. These types of investments provide lower levels of return.
The higher deeming rate is applied to investment asset values above the threshold amounts to reflect the fact that you can diversify your investment portfolio by chasing higher returns on higher-risk assets (like shares).
January 2015 changes
A major deeming rule change was introduced on 1 January 2015 when the investment balance of all new account-based super pensions were first included in the Age Pension income test. As a result, the deeming rate now applies to these super pensions that retirees can receive tax free, provided they are over 60 years of age and meet a superannuation condition of release.
However, the old rules were ‘grandfathered’ for people who were already receiving account-based super pensions and the Age Pension prior to 1 January 2015, which means their pensions are not deemed. Instead, the payments they receive, less a deductible amount, are counted in the income test, but only while they continue to receive income support without a break.
Below is an example of how the rule worked before 1 January 2015:
Common questions about deeming
Deeming raises plenty of questions, so we’ve answered some common ones from SuperGuide members below.
Q: I have my own home, but with a $200,000 mortgage on it. I also have $375,000 invested in shares. Does the income test assess the deemed income on $375,000 or does it reduce by the home mortgage amount and assess the deemed income on $175,000?
A: The value of the financial assets for deeming purposes in the income test cannot be reduced by the mortgage on the principal place of residence. It seems like you are conflating the issues of assessable assets under the assets test and the value of investments under the income test.
Furthermore, under the assets test, just as the value of a person’s home is not counted, neither are any loans secured against the residence. This means when a person or a couple use their home as security for an investment loan, the full value of the investments is counted under the assets test, and not the net value after deducting the loan balance.
Q: Is income tax calculated on my deemed income, or on the actual income I receive from my investments?
A: Centrelink assessable income and ATO taxable income are two completely separate calculations. Your taxable income is based on the actual income you receive, rather than Centrelink’s deeming rules.
Q: Does deeming apply to the Disability Support Pension, or only to the Age Pension?
Sign up free to read this answer
Access this answer with a free SuperGuide account. You’ll also get access to 100+ free guides.
Q: I have worked out my deemed income. Is that amount deducted from my Age Pension, or is it what I receive?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: Is the regular income I draw from my account-based pension included in the Age Pension income test? Would drawing less from my pension increase my Age Pension?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: My partner is over Age Pension age and I am younger. Is my super counted in the income test, and does it matter whether it is in accumulation or pension phase? Are super pension payments counted as income?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.
Q: Services Australia lists deeming thresholds for a couple where neither partner gets a pension. When does that apply?
This answer is for SuperGuide members
Members can read every answer on our guides, plus access member-only webinars, calculators and tools.


Leave a Reply
You must be logged in to post a comment.